Investment & Financial Planning
NRI Property Sale: How to Calculate Capital Gains TaxNRI Property Sale: How to Calculate Capital Gains Tax
Written by Shubham Jain

GIFT City, or Gujarat International Finance Tec-City, gives Non-Resident Indians (NRIs) access to financial products and services through India’s International Financial Services Centre (IFSC). Depending on the investment, the type of income and the applicable legal conditions, certain transactions through GIFT IFSC may qualify for Indian tax exemptions.
However, GIFT City is not a blanket tax-free investment destination. Tax benefits depend on the specific instrument, eligible investor or fund, transaction structure and statutory conditions. NRIs should also consider tax obligations in their country of residence before investing.
This guide explains the potential tax benefits of GIFT City for NRI investors, which transactions may qualify and what to verify before making an investment.
GIFT City is a financial hub in Gujarat that includes an International Financial Services Centre (IFSC). Financial institutions and eligible entities operating within the IFSC can provide specified financial services under the applicable regulatory framework, overseen by the International Financial Services Centres Authority (IFSCA).
For NRIs, GIFT City may provide access to eligible banking services, investment funds, securities and other financial products designed for international investors. The product, provider and investor eligibility rules differ by activity.
GIFT City’s tax framework is also different from a general claim that all income earned through the centre is tax-free. Indian tax law specifies the income categories, eligible persons and conditions for particular exemptions.
Understand how Indian tax rules apply to your NRI income and investments.
The tax treatment depends on the income and the transaction. Some exemptions previously appeared under Section 10 of the Income-tax Act, 1961. For tax years beginning on or after 1 April 2026, the corresponding IFSC-related exemptions are organised under Schedule VI, read with Section 11 of the Income-tax Act, 2025, subject to the relevant provisions and conditions.
NRIs should use the provision applicable to the tax year and transaction being examined rather than relying only on an older section number.
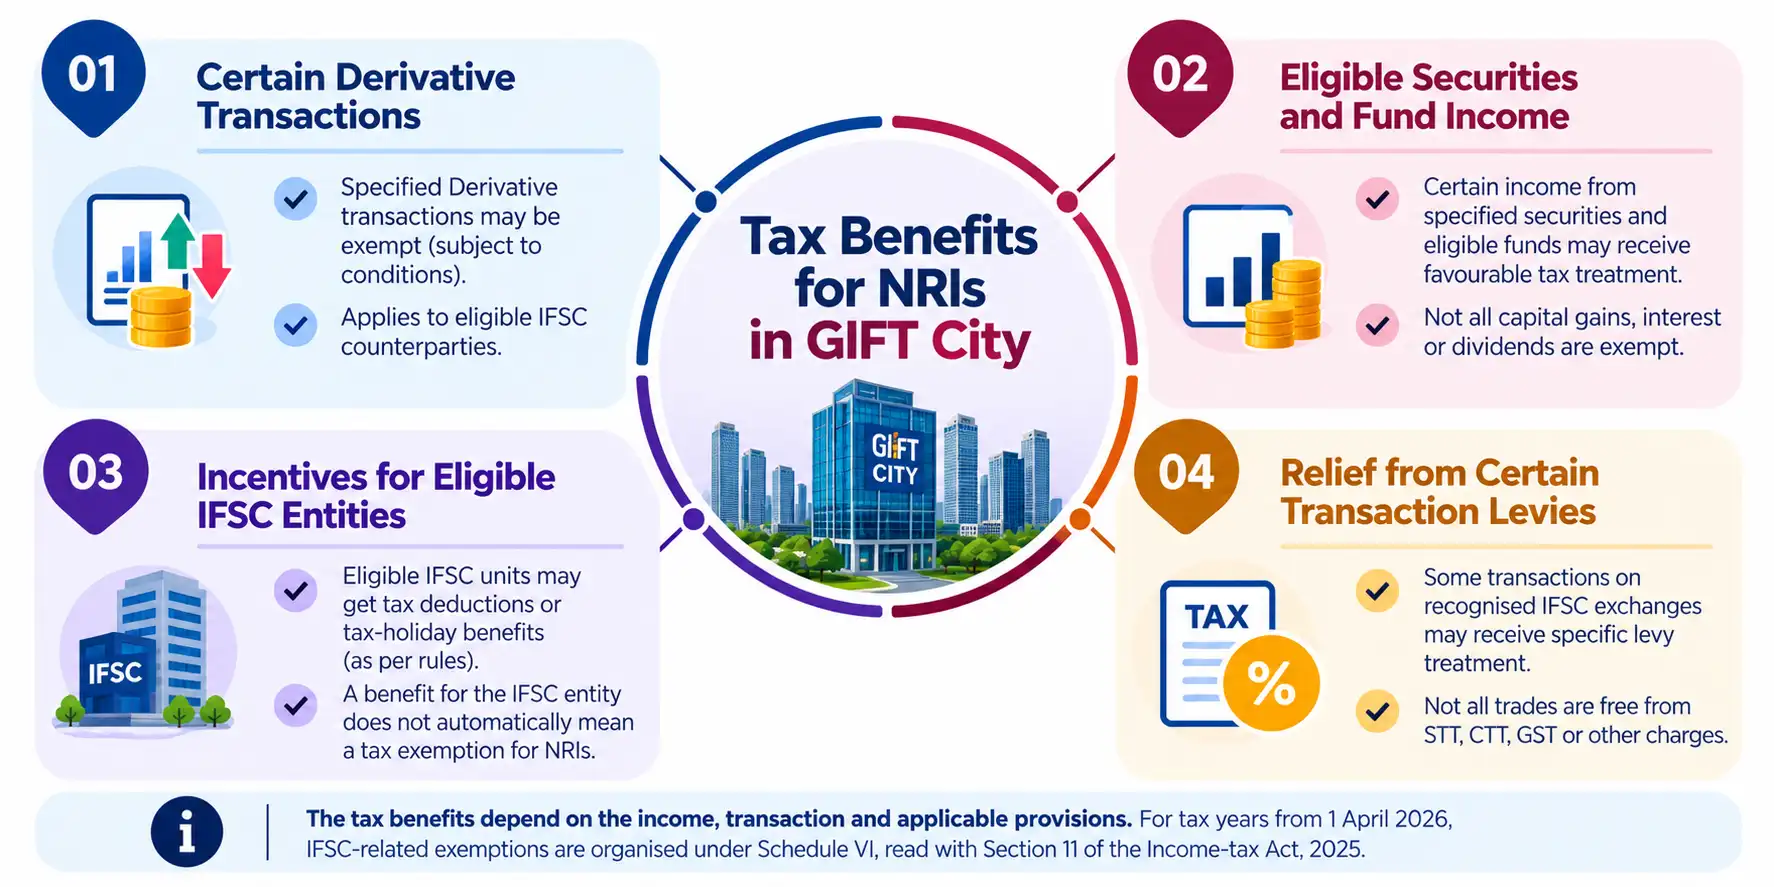
Specified derivative transactions may qualify for an exemption when the statutory conditions are met. Under the earlier Act, Section 10(4E) covered specified income arising to a non-resident from the transfer of non-deliverable forward contracts, offshore derivative instruments and over-the-counter (OTC) derivatives, as well as distributions of income on offshore derivative instruments or OTC derivatives, where the applicable conditions were met for transactions with an eligible IFSC offshore banking unit or qualifying IFSC foreign portfolio investor.
The scope depends on the transaction and the eligible counterparty or arrangement. The exemption should not be interpreted as covering every derivative product traded or arranged through GIFT City.
Before relying on this benefit, an NRI should confirm:
The exemption previously provided under Section 10(4E) should be checked against the corresponding provisions in Schedule VI of the Income-tax Act, 2025 for relevant tax years.
Certain income connected with specified securities and eligible investment funds may receive favourable treatment under the IFSC framework. However, the result depends on the precise category of income, the fund or investor involved, and the statutory conditions.
For example, exemptions under the earlier Section 10(4D) covered specified income associated with eligible funds and securities transactions. Other provisions addressed income connected with specified funds and their units.
This does not mean that all capital gains, interest, dividends or fund distributions from GIFT City are automatically exempt. The treatment of an investor’s return must be determined from the actual investment and applicable law.
If you are comparing fund structures, investment categories and the process of investing, see our separate guide: GIFT City Funds for NRIs: Investment Guide and Tax Benefits.
Certain eligible IFSC units may receive tax incentives under Indian law. These can include deductions or tax-holiday arrangements for qualifying businesses, subject to applicable eligibility requirements and time limits.
However, a tax benefit granted to an IFSC entity is not automatically an exemption for an NRI investing in that entity or its products. The tax treatment of the entity and the investor must be examined separately.
NRIs should assess the tax treatment of the income they actually receive, such as interest, dividends, distributions or gains, instead of assuming that the provider’s tax status determines their personal liability.
Some transactions on recognised IFSC exchanges may receive specific treatment under the applicable tax and levy rules. The result depends on the exchange, instrument, transaction and relevant legal provisions.
Do not assume that every trade conducted through GIFT City is free from securities transaction tax, commodity transaction tax, GST or other charges. Different taxes and fees have different rules, and an exemption from one levy does not establish an exemption from all others.
Ask the provider for a breakdown of applicable taxes, statutory levies, brokerage, fund expenses and other transaction costs before comparing an IFSC investment with an alternative route.
Tax exemptions apply to specified income and eligible transactions—not simply because an investment is associated with GIFT City.
The following table provides a general starting point. Eligibility must be confirmed against the law applicable to the tax year and the investor’s circumstances.
| Investment or income category | What NRIs should verify |
|---|---|
| Specified derivative transactions | Instrument type, counterparty, transaction structure and exemption conditions |
| Securities transactions through an IFSC exchange | Whether the security and transfer fall within the relevant statutory provision |
| Income connected with eligible investment funds | Fund status, type of income, investor eligibility and statutory conditions |
| Income from specified offshore investment or portfolio arrangements | Whether the income and account arrangement meet the applicable requirements |
| Interest or dividends from an IFSC-linked product | The specific tax provision, source of income and any withholding requirements |
The Income-tax Act, 2025 includes Schedule VI for specified income of eligible persons in or having income from an IFSC. The Schedule identifies categories of income, eligible persons and conditions. It should be consulted alongside the applicable rules and amendments rather than treated as a universal exemption for IFSC investments.
Official reference: Income-tax Act, 2025 — Schedule VI.
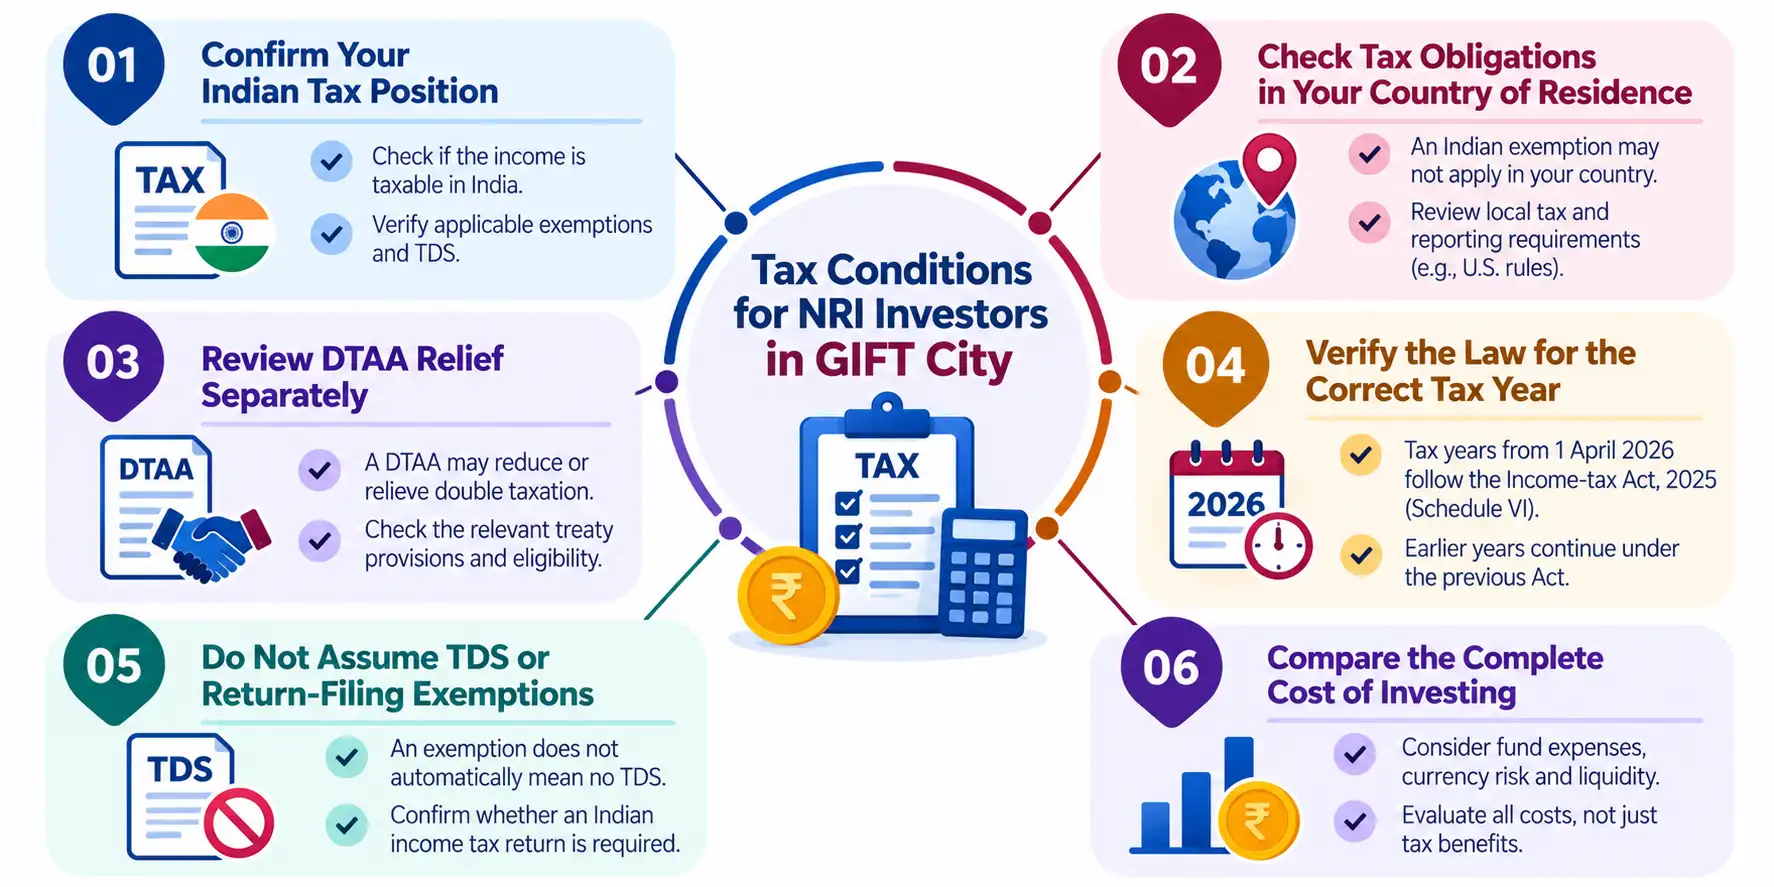
Your Indian tax obligations depend on your residential status under Indian tax law, the nature and source of income, and the provisions applicable to the transaction. Being an NRI does not by itself make every Indian investment income exempt.
Check whether the income is taxable in India, whether an exemption applies and whether tax has been withheld. Keep the investment statements and supporting documents needed to establish the nature of the income.
An exemption in India does not necessarily exempt the same income in the country where you live. For example, an NRI living in the United States may need to examine US tax and reporting requirements even if a particular income category qualifies for relief in India.
The relevant treatment depends on the investor’s tax residence, citizenship where applicable, the income category and local law. Do not assume that an Indian exemption eliminates foreign reporting obligations.
A Double Taxation Avoidance Agreement (DTAA) may affect how particular income is taxed or how double taxation is relieved. Its application depends on the relevant treaty, tax residency, income category and documentation.
A DTAA does not automatically make every GIFT City investment tax-free. Check the treaty provisions and whether relief is available under the facts of your case.
The Income-tax Act, 2025 came into force on 1 April 2026. Tax years beginning before that date continue to be governed by the earlier Act under the transition provisions, while the new Act applies to relevant tax years beginning from that date.
As a result, references to provisions such as Sections 10(4D) and 10(4E) may be relevant when examining earlier tax years. For Tax Year 2026–27 and subsequent years, check the corresponding provisions in the 2025 Act, including Schedule VI, as amended.
Official references:
An exemption from tax on a particular income category does not automatically mean that no tax will be deducted at source or that no Indian income tax return is required. Withholding and return-filing obligations have their own legal conditions.
Before investing, ask the bank, fund or financial service provider for the applicable tax documentation and confirm your personal filing position with a qualified tax professional.
Tax treatment is only one part of an investment decision. NRIs should also compare investment risk, fund expenses, currency exposure, liquidity, redemption conditions, reporting obligations and any charges levied by the provider.
A structure that offers a specific tax exemption may not necessarily be suitable for every investor. Consider the complete financial and tax position before selecting an investment.
Review Indian and overseas tax considerations before making an investment decision.
GIFT City can provide NRIs with access to eligible international financial products and certain tax exemptions. However, the benefit depends on the specific investment, the income earned and the conditions prescribed under Indian tax law. Reviewing the tax position in both India and your country of residence can help you avoid relying on an exemption that may not apply to your circumstances.
Savetaxs can help NRIs review Indian tax obligations, understand cross-border tax considerations and assess relevant return-filing requirements. Before investing, seek advice based on your residential status, income category and the specific GIFT IFSC product under consideration.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Vipul Jain is the Co-Founder of SaveTaxs and a tax expert with experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA, and compliance matters. He focuses on making complex tax concepts simple and helping taxpayers make informed, compliant decisions. See Full Bio
Want to read more? Explore Blogs