NRI Income Tax Compliance
Capital Gains Tax Planning for NRIs Living in the USCapital Gains Tax Planning for NRIs Living in the US
Written by Hatim Dudhiyawala
Living in the United States while maintaining financial connections with India can create tax questions that are difficult to resolve by looking at either country's rules in isolation. You may earn a salary in the US, own property in India, hold Indian investments, receive dividends, or plan to move back to India.
Each situation can involve different tax rules, filing obligations, documentation requirements, and deadlines. The challenge is understanding how these obligations interact before making a financial decision or submitting a tax return. Your Indian residential status and US tax residency are separate determinations and should be assessed independently.
Savetaxs helps NRIs assess India–US tax matters in a coordinated way, bringing together relevant residency considerations, income and asset-related questions, potential double-taxation relief, and compliance requirements.
If your financial life spans India and the US, a structured review can help identify which issues apply to you, which require specialist attention, and what information you should prepare.
Cross-border tax planning is not simply about filing two tax returns. It involves understanding the tax rules that apply to your particular circumstances and coordinating decisions across jurisdictions.
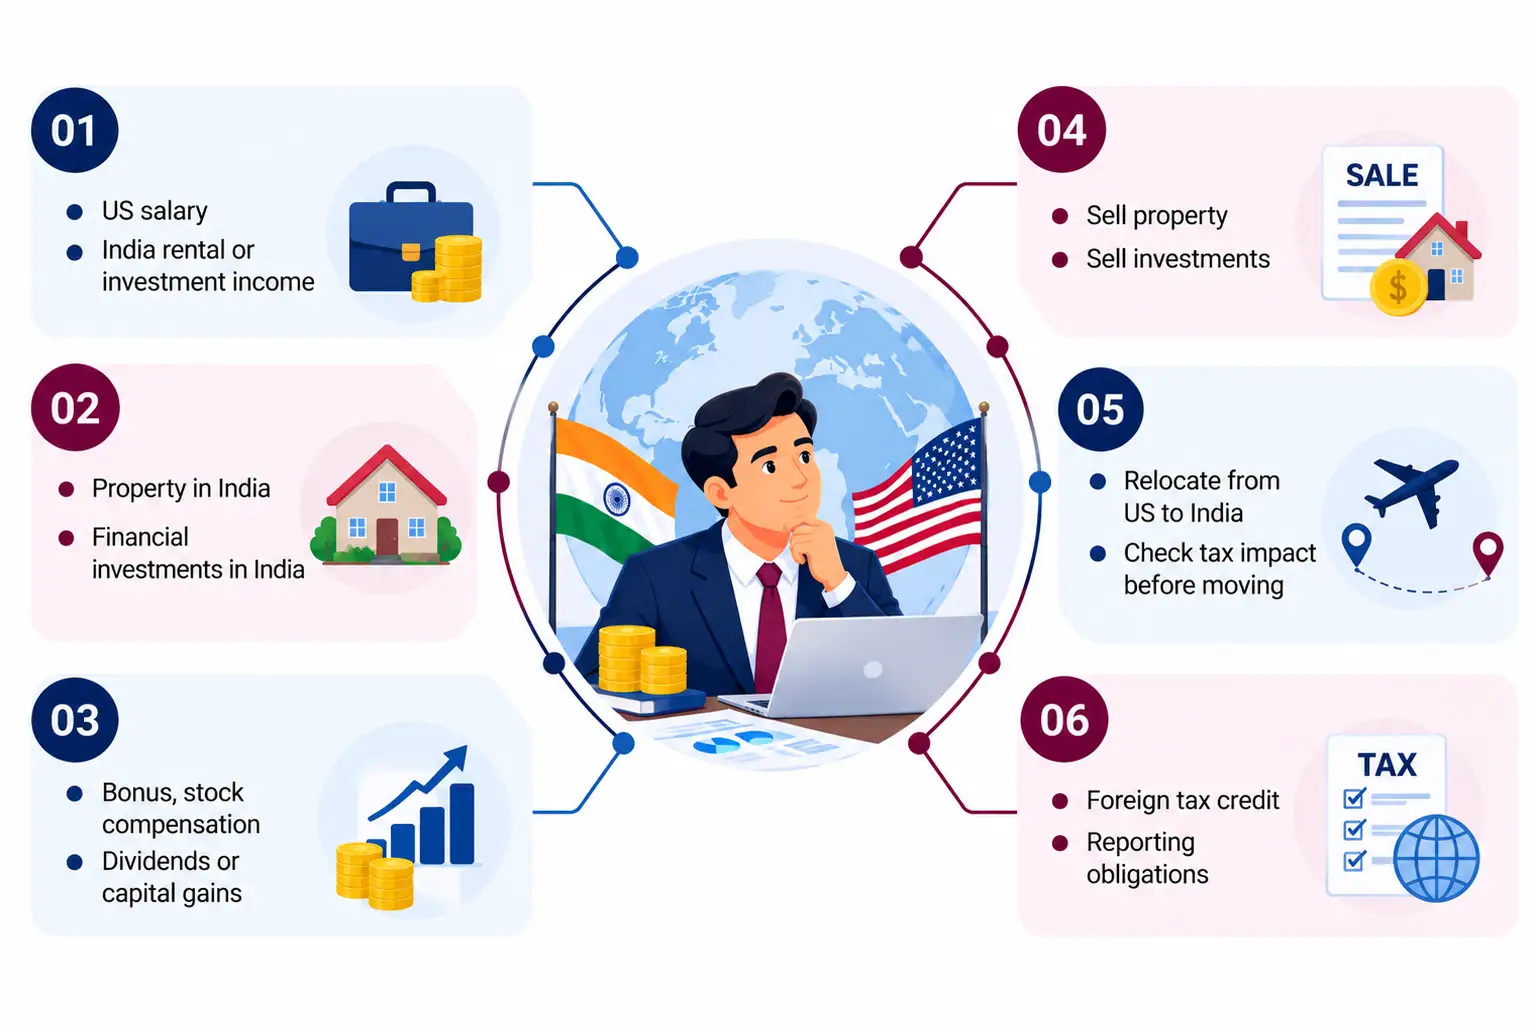
You may need a review if you:
The appropriate approach depends on factors such as citizenship, tax residency, income type, asset ownership, transaction dates, and the tax year involved. Not every requirement applies to every NRI.
Get help identifying cross-border tax questions involving residency, income, investments and compliance.
Savetaxs's cross-border tax-planning approach focuses on identifying relevant tax questions, understanding how they connect, and determining which matters need further review.
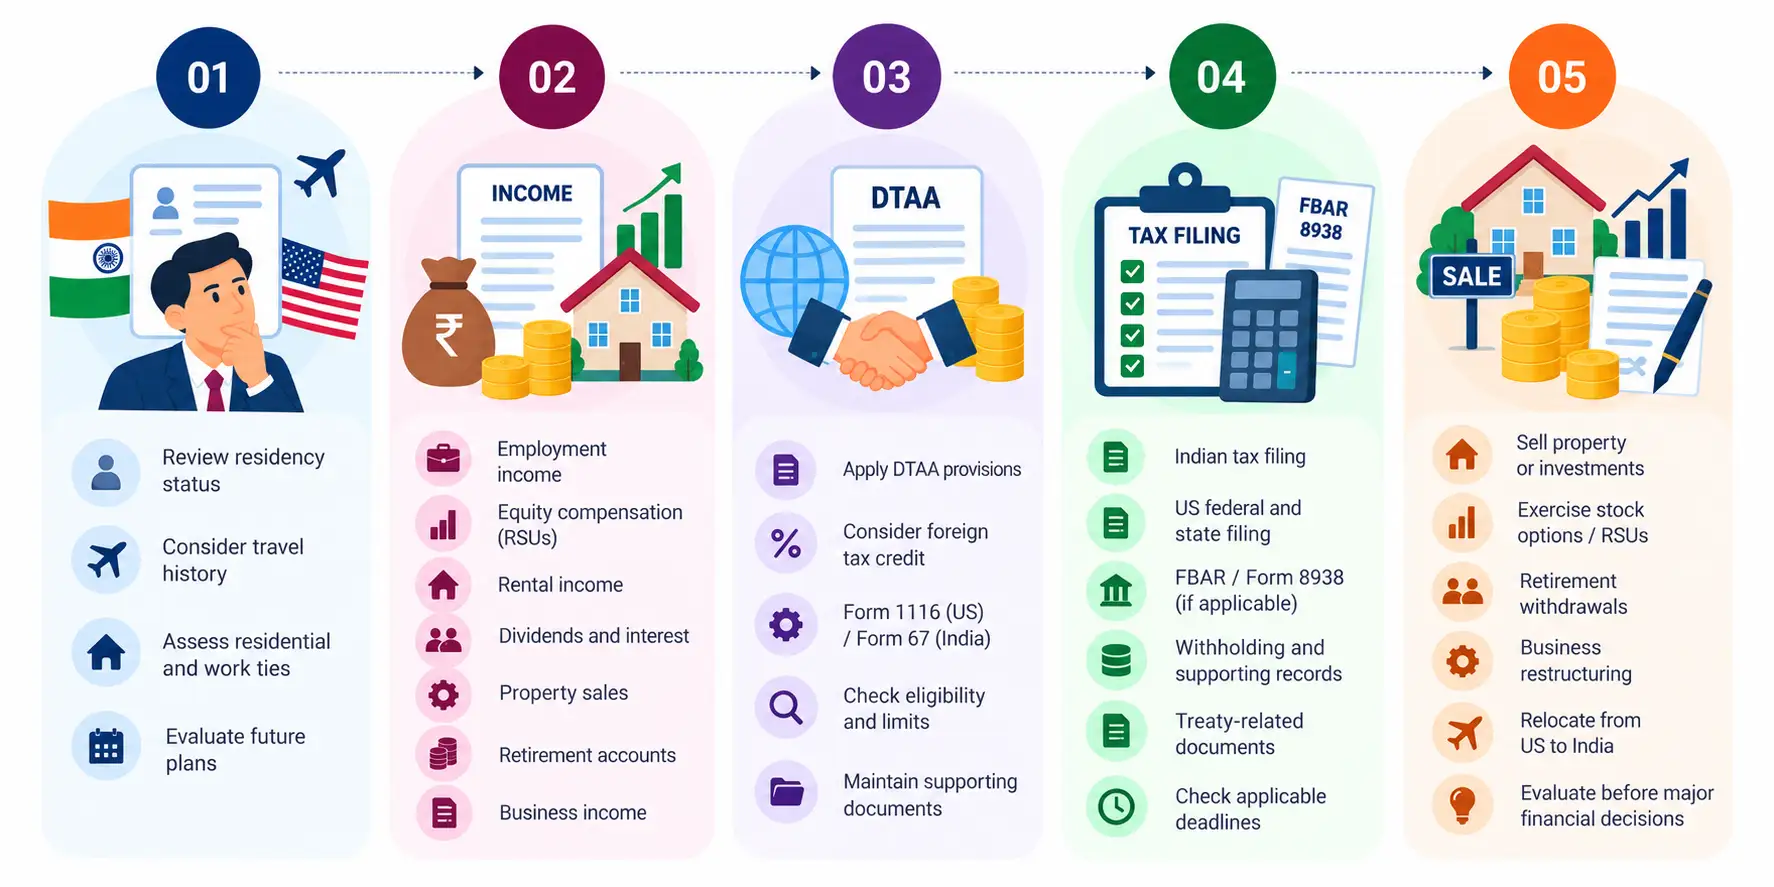
Tax residency is an important starting point because India and the US use their own domestic rules to determine whether an individual is a tax resident.
An individual's status can change from one tax year to another. It can also be possible to meet domestic residency tests in more than one country, requiring further analysis of the applicable treaty provisions.
A review may consider your travel history, residential circumstances, employment, and plans to relocate. Your status should be assessed for the relevant year rather than assumed from a previous year's outcome.
For detailed background on Indian residential status, see our guide to NRI tax-planning strategies.
Different income categories can have different tax treatments. A cross-border review may involve:
The source of income, applicable domestic law, residency, treaty provisions, and transaction details can all affect the outcome.
For example, an NRI living in California who receives rent from an apartment in India may need to examine Indian tax obligations relating to that rent as well as the relevant US reporting and taxation requirements. The correct treatment depends on the individual's circumstances.
Income connected to two countries may raise questions about whether both countries can tax it and whether relief is available.
The India–US Double Taxation Avoidance Agreement (DTAA) contains provisions addressing the taxation of specified categories of income. Foreign tax credit rules may also be relevant, subject to the applicable domestic law, treaty provisions, eligibility requirements, limitations, and documentation. Eligible US individual taxpayers may need to consider Form 1116 when claiming a foreign tax credit, while Form 67 may be relevant to eligible Indian resident taxpayers claiming credit for foreign taxes under the applicable Indian rules.
A coordinated review can help identify which relief mechanisms may be relevant and what evidence may be required.
Relief is not automatic in every situation. The tax treatment must be assessed for the relevant income and taxpayer.
For a detailed explanation of US foreign tax credit rules, see our US Foreign Tax Credit and Form 1116 guide.
Cross-border compliance can involve more than preparing income tax returns. Depending on your circumstances, you may need to review:
Reporting obligations differ according to the taxpayer's status, citizenship, account ownership, income, asset type, and applicable rules. A reporting requirement in one country should not be assumed to apply in the same way in the other. Foreign-account and foreign-asset reporting requirements are separate from income tax return filing, and not every NRI is required to file every reporting form.
The aim of a coordinated review is to identify the requirements that actually apply, rather than relying on a generic checklist for every NRI.
Tax planning may be especially useful before a significant financial event, when the available choices and their consequences can still be assessed.
Examples include:
Consider an NRI who plans to sell a property in India while living in the US. The review may need to address Indian capital gains, applicable withholding, relevant documentation, and the potential US tax treatment. These questions should be assessed using the facts and rules applicable to that transaction.
Planning before a transaction does not guarantee a tax saving, but it can help identify obligations and legitimate options before decisions become difficult to change.
The following examples illustrate situations in which a coordinated review may be useful.
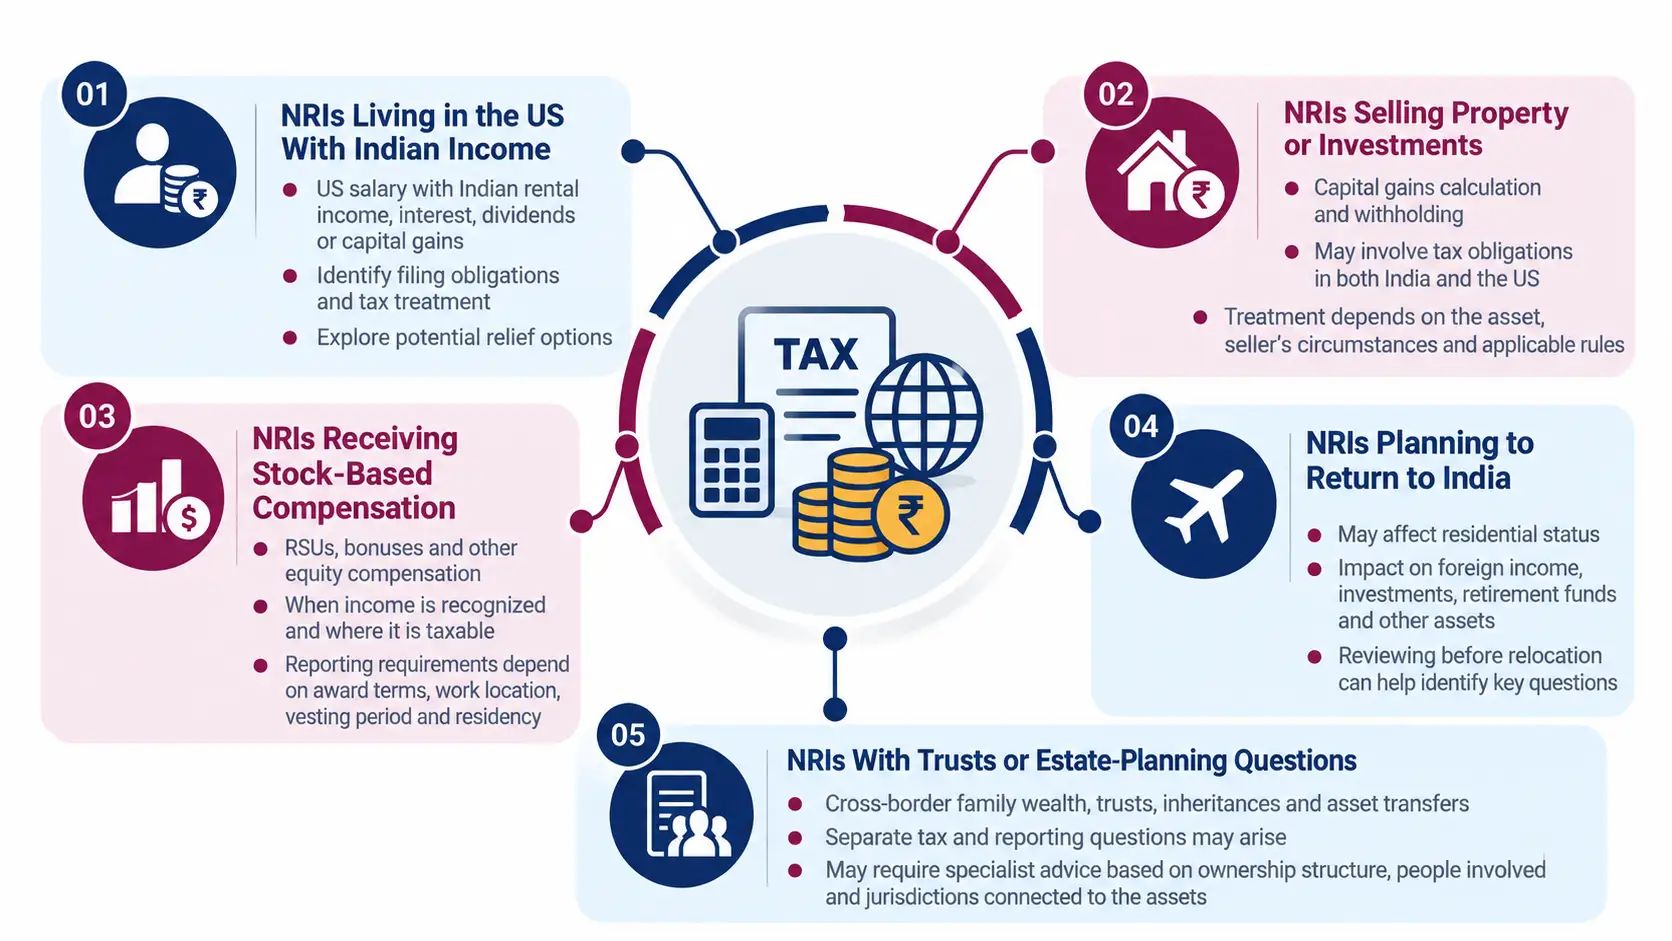
You may receive a US salary while earning rental income, interest, dividends, or capital gains connected to India. A review can help identify the relevant filing obligations, tax treatment, and potential relief mechanisms.
A sale may involve capital gains calculations, withholding, supporting documents, and tax obligations in more than one jurisdiction. The treatment depends on the asset, the seller's circumstances, and the applicable rules.
If your situation involves a US property sale, explore our guide to selling property in the USA as an NRI.
RSUs, bonuses, and other equity compensation can raise questions about when income is recognized, where it is taxable, and which reporting requirements apply. The relevant analysis may depend on the award terms, work location, vesting period, residency, and applicable law.
Moving back to India can affect your residential status and the tax treatment of foreign income, investments, retirement funds, and other assets. Reviewing these issues before relocating can help identify questions that need attention.
For retirement-related considerations, see our retirement tax-planning guide for NRIs returning to India.
Cross-border family wealth, trusts, inheritances, and asset transfers can raise separate tax and reporting questions. These situations may require specialist advice based on the ownership structure, the people involved, and the jurisdictions connected to the assets.
For related background, read our guide to estate planning for NRIs through trusts.
Having relevant information available can make an initial review more efficient. Depending on your situation, useful records may include:
You may not need every document listed above. The required information depends on the questions being reviewed.
Discuss your income, assets and upcoming financial decisions to identify the tax issues that need attention.
A useful starting point is to explain your current country of residence, your financial connections to India, the type of income or assets involved, and any major financial decision you are considering.
This helps identify the main questions that need review and whether they involve Indian taxation, US taxation, treaty relief, reporting obligations, or a combination of these areas.
The scope of support should be clear before any engagement begins. Some situations may require input from a tax professional qualified in a particular jurisdiction or specialist advice on a complex transaction.
Savetaxs can help you identify relevant cross-border tax considerations and the areas that may need further professional attention.
If you live in the US and have income, investments, property, or financial responsibilities connected to India, reviewing these matters together may help you understand your tax position and prepare for upcoming decisions.
Savetaxs provides tax and compliance support for relevant NRI situations. The appropriate scope depends on your circumstances and the services required.
Discuss your India–US tax-planning needs with Savetaxs to identify the questions that should be reviewed for your situation.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Vipul Jain is the Co-Founder of SaveTaxs and a tax expert with experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA, and compliance matters. He focuses on making complex tax concepts simple and helping taxpayers make informed, compliant decisions. See Full Bio
Want to read more? Explore Blogs