US Tax Filing and Compliance
How to Report Multiple 1099 Forms on a U.S. Tax Return: A Guide for NRIsHow to Report Multiple 1099 Forms on a U.S. Tax Return: A Guide for NRIs
Written by Hatim Dudhiyawala

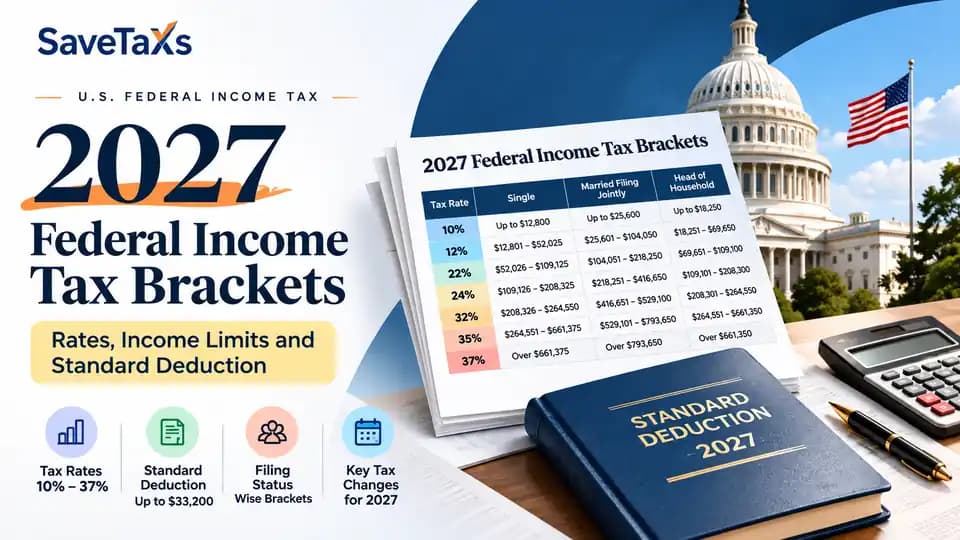
The IRS has announced the 2027 federal income tax brackets, increasing the income thresholds for all seven federal income tax rates to account for inflation. The seven marginal tax rates remain unchanged, but taxpayers can earn more taxable income before moving into a higher tax bracket.
For the 2027 tax year, federal income tax rates range from 10% to 37%. The highest marginal rate of 37% applies to taxable income exceeding $661,375 for single taxpayers and $793,650 for married couples filing jointly.
The IRS has also increased the 2027 standard deduction to $16,600 for single taxpayers, $33,200 for married couples filing jointly and $24,925 for heads of households.
These adjustments apply to income earned from January 1 through December 31, 2027. Most individual taxpayers will report this income when filing their 2027 federal income tax returns in 2028.
For U.S. citizens, Green Card holders, resident aliens, nonresident aliens and NRIs with U.S. tax obligations, understanding these thresholds can help with income tax planning, investment decisions, withholding and estimated tax payments.
This guide explains the 2027 federal income tax brackets, standard deductions, other important tax adjustments and their implications for individuals with income or financial interests in both India and the United States.
The United States follows a progressive federal income tax system. This means different portions of a taxpayer's taxable income are taxed at different rates rather than applying one tax rate to the entire income amount.
For tax year 2027, the IRS has retained seven marginal tax rates:
10%
12%
22%
24%
32%
35%
37%
The following table shows the 2027 federal income tax brackets for the four primary individual filing statuses.
| Tax Rate | Single | Married Filing Jointly | Head of Household | Married Filing Separately |
|---|---|---|---|---|
| 10% | Up to $12,800 | Up to $25,600 | Up to $18,250 | Up to $12,800 |
| 12% | Over $12,800–$52,025 | Over $25,600–$104,050 | Over $18,250–$69,650 | Over $12,800–$52,025 |
| 22% | Over $52,025–$109,125 | Over $104,050–$218,250 | Over $69,650–$109,100 | Over $52,025–$109,125 |
| 24% | Over $109,125–$208,325 | Over $218,250–$416,650 | Over $109,100–$208,300 | Over $109,125–$208,325 |
| 32% | Over $208,325–$264,550 | Over $416,650–$529,100 | Over $208,300–$264,550 | Over $208,325–$264,550 |
| 35% | Over $264,550–$661,375 | Over $529,100–$793,650 | Over $264,550–$661,350 | Over $264,550–$396,825 |
| 37% | Over $661,375 | Over $793,650 | Over $661,350 | Over $396,825 |
Source: IRS Revenue Procedure 2026-35. Qualifying surviving spouses generally use the married filing jointly tax rate schedule.
These thresholds represent taxable income, not gross salary or total household earnings. Taxable income is generally calculated after applicable deductions and adjustments.
The thresholds in this table apply to ordinary federal income tax. State income taxes, Social Security and Medicare taxes, and other applicable federal taxes are calculated separately.
The standard deduction reduces the amount of income subject to federal income tax. Taxpayers generally compare the standard deduction with their eligible itemized deductions and use the deduction permitted under the applicable rules that provides the greater tax benefit.
For the 2027 tax year, the IRS has increased the standard deduction across the four primary individual filing statuses.
| Filing Status | 2026 Standard Deduction | 2027 Standard Deduction | Increase |
|---|---|---|---|
| Single | $16,100 | $16,600 | $500 |
| Married Filing Jointly | $32,200 | $33,200 | $1,000 |
| Married Filing Separately | $16,100 | $16,600 | $500 |
| Head of Household | $24,150 | $24,925 | $775 |
The figures above are the basic standard deduction amounts. Additional deductions may apply to eligible taxpayers based on age, blindness or other provisions.
Example: How the 2027 standard deduction affects taxable income
Consider a single taxpayer with an adjusted gross income of $80,000 who qualifies for the $16,600 standard deduction.
The calculation would be:
| Particulars | Amount |
|---|---|
| Adjusted Gross Income | $80,000 |
| 2027 Standard Deduction | $16,600 |
| Taxable Income | $63,400 |
The taxpayer would generally calculate federal income tax using the 2027 tax brackets on $63,400, assuming no other applicable deductions or adjustments.
The standard deduction is not automatically available to every taxpayer. Nonresident aliens generally cannot claim it, subject to limited exceptions. Certain eligible Indian students and business apprentices may qualify under Article 21(2) of the U.S.-India income tax treaty.
The standard deduction is separate from the additional senior deduction introduced under the Working Families Tax Cuts.
Eligible individuals aged 65 or older may qualify for an additional deduction of up to $6,000 per person for tax years 2025 through 2028. The deduction is subject to income-based phaseouts and other eligibility requirements.
For married couples, the potential deduction can reach $12,000 when both spouses qualify. Taxpayers should review the applicable Social Security number and filing requirements before claiming this benefit.
Federal income tax brackets operate on a marginal basis. This means each portion of taxable income is taxed at the rate assigned to its respective bracket.
Entering a higher tax bracket does not mean that all your income becomes taxable at that higher rate. Only the portion of income within the higher bracket is taxed at the corresponding marginal rate.
Consider a single taxpayer with $100,000 in taxable income for the 2027 tax year.
The federal income tax calculation would be:
| Income Portion | Tax Rate | Federal Income Tax |
|---|---|---|
| First $12,800 | 10% | $1,280 |
| Next $39,225 | 12% | $4,707 |
| Remaining $47,975 | 22% | $10,554 |
| Total Federal Income Tax | $16,541 | |
The taxpayer's regular federal income tax under these brackets would be $16,541 before applicable tax credits and other taxes.
Although the taxpayer falls into the 22% marginal tax bracket, the effective federal income tax rate is approximately 16.54%.
This distinction is important when estimating tax liabilities, evaluating salary increases, planning bonuses or comparing compensation packages.
The IRS adjusts federal income tax thresholds annually to account for inflation. For 2027, the income limits associated with all seven marginal tax rates have increased, while the existing rate structure remains unchanged.
Some important changes for single taxpayers include:
| Tax Bracket | 2026 Threshold | 2027 Threshold |
|---|---|---|
| 10% bracket ends | $12,400 | $12,800 |
| 12% bracket ends | $50,400 | $52,025 |
| 22% bracket ends | $105,700 | $109,125 |
| 24% bracket ends | $201,775 | $208,325 |
| 32% bracket ends | $256,225 | $264,550 |
| 35% bracket ends | $640,600 | $661,375 |
The highest 37% marginal tax bracket now begins above:
Single taxpayers: $661,375 in 2027, compared with $640,600 in 2026.
Married couples filing jointly: $793,650 in 2027, compared with $768,700 in 2026.
The standard deduction has also increased, giving eligible taxpayers a higher deduction against their income.
However, higher tax thresholds do not guarantee that every taxpayer will pay less federal income tax. The final tax liability depends on income changes, filing status, deductions, credits and other applicable tax provisions.
For comparison, see our guide to 2026 federal income tax brackets.
Alongside the ordinary income tax brackets and standard deduction, the IRS has adjusted several other provisions that may affect individuals, families and investors.
These are selected provisions relevant to individual taxpayers; they do not represent every 2027 tax adjustment.
For tax year 2027, the maximum Child Tax Credit increases to $2,300 per eligible qualifying child.
The amount used to determine the refundable portion of the credit also increases to $1,800.
The maximum credit is not automatically available to every taxpayer. Eligibility depends on applicable income limits, qualifying-child requirements, identification rules and other tax provisions.
The Alternative Minimum Tax is a separate federal tax calculation designed to ensure that certain taxpayers with higher incomes and particular tax benefits pay at least a minimum level of federal income tax.
For 2027, the AMT exemption amounts are:
| Taxpayer Category | 2027 AMT Exemption |
|---|---|
| Unmarried Individuals | $93,000 |
| Married Filing Jointly | $144,700 |
| Married Filing Separately | $72,350 |
The AMT exemption begins to phase out at the following income levels:
| Filing Status | Phaseout Begins | Exemption Fully Phased Out |
|---|---|---|
| Unmarried Individuals | $515,950 | $701,950 |
| Married Filing Jointly | $1,031,900 | $1,321,300 |
| Married Filing Separately | $515,950 | $660,650 |
Taxpayers with higher incomes, substantial deductions or certain investment arrangements may need to evaluate both their regular federal income tax and potential AMT liability.
Eligible long-term capital gains generally receive preferential federal tax treatment compared with ordinary income.
Depending on taxable income and filing status, the applicable federal long-term capital gains rates are 0%, 15% or 20%.
For tax year 2027, the income thresholds are:
| Filing Status | Maximum Taxable Income for 0% Rate | Maximum Taxable Income for 15% Rate |
|---|---|---|
| Single | $51,050 | $563,200 |
| Married Filing Jointly | $102,100 | $633,600 |
| Married Filing Separately | $51,050 | $316,800 |
| Head of Household | $68,350 | $598,400 |
The 0% rate may apply to eligible long-term capital gains to the extent total taxable income remains within the applicable threshold.
The 15% rate generally applies to the portion above the 0% threshold and within the next income limit. The 20% rate generally applies to eligible gains above the applicable 15% threshold.
These thresholds relate to total taxable income, including ordinary income and eligible long-term capital gains. They are not separate capital gains allowances.
Short-term capital gains, generally involving assets held for one year or less, are typically taxed at ordinary income tax rates. Additional taxes, such as the Net Investment Income Tax, may also apply to eligible taxpayers.
The Foreign Earned Income Exclusion (FEIE) is particularly relevant to eligible U.S. citizens and resident aliens who live and work outside the United States.
For tax year 2027, the maximum foreign earned income exclusion increases to $137,300, compared with $132,900 for 2026.
However, earning income outside the United States does not automatically make someone eligible for this exclusion.
A qualifying taxpayer must generally:
Have a tax home in a foreign country.
Earn qualifying foreign-source employment or self-employment income.
Meet either the bona fide residence test or the physical presence test.
Under the physical presence test, an eligible taxpayer must generally spend at least 330 full days in a foreign country or countries during a qualifying period of 12 consecutive months. The qualifying period must include part of the relevant tax year.
The bona fide residence test has separate requirements concerning the taxpayer's foreign residence and the period of residence.
The FEIE does not generally apply to passive income such as dividends, interest, rental income or capital gains.
Claiming the exclusion also does not automatically eliminate the requirement to file a U.S. tax return. Eligible taxpayers generally claim the exclusion using Form 2555 with their federal income tax return when required to file.
For individuals with financial interests in both India and the United States, the 2027 federal income tax brackets are only one part of their overall U.S. tax calculation.
An important distinction is that NRI status under Indian tax law and tax residency under U.S. tax law are two different classifications.
A person may qualify as an NRI under Indian tax rules while being classified as a U.S. citizen, resident alien or nonresident alien under U.S. tax law, depending on their individual circumstances.
U.S. citizens and resident aliens are generally subject to U.S. federal income tax on their worldwide income.
This means income from India, including qualifying interest, dividends, rental income, business income and other foreign-source income, may need to be reported on a U.S. tax return.
The applicable treatment depends on the income's classification, source and relevant tax provisions.
Resident aliens generally use the same graduated federal income tax rates as U.S. citizens.
For these taxpayers, the 2027 federal income tax brackets can affect the calculation of their combined taxable income, even when some of that income originates outside the United States.
Nonresident aliens follow different federal income tax rules.
Their U.S. tax obligations generally depend on the source and classification of their income rather than worldwide income.
The two important income categories are:
1. Effectively Connected Income (ECI)
Income effectively connected with a U.S. trade or business is generally taxed at graduated federal income tax rates after allowable deductions.
These rates are the same ordinary income tax rates that apply to U.S. citizens and resident aliens, although nonresident aliens have different filing-status and deduction rules.
2. Fixed, Determinable, Annual, or Periodical (FDAP) Income
U.S.-source FDAP income that is not effectively connected with a U.S. trade or business is generally subject to a 30% tax on its gross amount, or a lower applicable treaty rate.
No deductions are generally allowed against this category of income.
Not every type of U.S.-source income falls under the same treatment. Certain capital gains and other income categories are subject to separate rules.
Generally, no. Nonresident aliens cannot claim the standard deduction when filing Form 1040-NR.
However, an important exception applies to certain eligible Indian students and business apprentices under Article 21(2) of the U.S.-India income tax treaty.
These taxpayers may qualify to claim the standard deduction if they satisfy the relevant treaty requirements.
Nonresident aliens also generally cannot use the head-of-household filing status. Therefore, the filing-status thresholds in the main bracket table should not be assumed to apply to every nonresident alien.
Determining U.S. tax residency and filing eligibility before calculating tax is essential. Applying the standard deduction or ordinary tax brackets without considering these rules can produce an incorrect tax estimate.
NRIs, Green Card holders and U.S. taxpayers with Indian income may also need to evaluate several additional tax and reporting requirements.
These include:
Foreign Tax Credit: May help reduce double taxation on qualifying foreign income taxes, subject to applicable limitations.
U.S.-India Income Tax Treaty: May provide specific treaty benefits depending on the taxpayer's residency and income classification.
FBAR: Reporting foreign financial accounts when the applicable filing requirements are met.
FATCA Form 8938: Reporting specified foreign financial assets when the relevant thresholds and conditions apply.
PFIC Reporting: Evaluating the U.S. tax treatment of certain foreign pooled investments, including potentially applicable Indian mutual fund investments.
These requirements are separate from ordinary federal income tax brackets. A taxpayer may have an income tax liability as well as separate international information-reporting obligations.
The updated tax brackets provide an opportunity for individuals and families to review expected income, deductions and federal tax liabilities before the beginning of 2027.
Consider the following steps when preparing for the upcoming tax year.
1. Review Your Expected Annual Income
Estimate your salary, bonuses, self-employment earnings, investment income, capital gains and other taxable income.
For taxpayers with income from India and the United States, consider the source and classification of each income category.
2. Confirm Your Filing Status
Your filing status determines which tax bracket thresholds and standard deduction may apply.
Evaluate whether you qualify to file as single, married filing jointly, married filing separately or head of household.
Taxpayers with nonresident alien status should also review the special filing-status rules applicable to Form 1040-NR.
3. Evaluate Standard and Itemized Deductions
Compare the 2027 standard deduction with your eligible itemized deductions.
Also review any additional deductions for which you may qualify, including applicable age-related or other deductions introduced under the Working Families Tax Cuts.
Do not assume that every taxpayer, particularly nonresident aliens, is eligible for the standard deduction.
4. Review Estimated Tax Payments and Withholding
Compare your expected federal tax liability with the amount withheld from your salary or paid through estimated tax installments.
This can help identify potential underpayment issues before the end of the tax year.
5. Review International Tax Obligations
If you have income, investments or financial accounts in multiple countries, determine which U.S. reporting rules apply.
For eligible taxpayers, review the Foreign Tax Credit, Foreign Earned Income Exclusion and relevant treaty provisions before making tax-planning decisions.
6. Maintain Supporting Financial Records
Keep records of income, investment transactions, foreign taxes paid, deductions and relevant financial accounts.
Organized documentation can make tax preparation more efficient and help substantiate the information reported on your return.
The IRS's 2027 tax inflation adjustments increase federal income tax bracket thresholds, standard deductions and several other tax limits while retaining the seven existing marginal income tax rates.
For individuals and families, the most important figures to review are expected taxable income, filing status, applicable deductions and potential tax credits.
For NRIs, Green Card holders and individuals with income from India and the United States, additional attention is necessary. U.S. tax residency, worldwide income reporting, foreign tax credits and international financial reporting obligations can significantly influence the final tax position.
Reviewing these factors before the beginning of the 2027 tax year can help taxpayers make informed financial decisions and prepare for their upcoming federal tax obligations.
Need help with your U.S. tax filing?
Whether you are a U.S. citizen living abroad, a Green Card holder with Indian income or an NRI with U.S. tax obligations, understanding your filing requirements is essential.
Savetaxs provides assistance with U.S. individual tax returns, expatriate tax compliance, foreign income reporting and cross-border tax matters.
Explore our U.S. Tax Services to understand the available services and filing support.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Hatim Dudhiyawala is a Certified Public Accountant (CPA) with SaveTaxs and specializes in Indian and NRI taxation. He advises individuals, NRIs, and businesses on income tax filing, capital gains taxation, DTAA benefits, fund repatriation, and tax compliance. With experience in cross-border tax matters, Hatim helps taxpayers understand complex regulations and make informed decisions. Through his articles, he shares practical insights to help readers stay compliant and manage their tax obligations with confidence. See Full Bio

Want to read more? Explore Blogs