Payroll Planning
Payroll Outsourcing vs In-House Payroll for NRI-Owned BusinessesPayroll Outsourcing vs In-House Payroll for NRI-Owned Businesses
Written by Shubham Jain
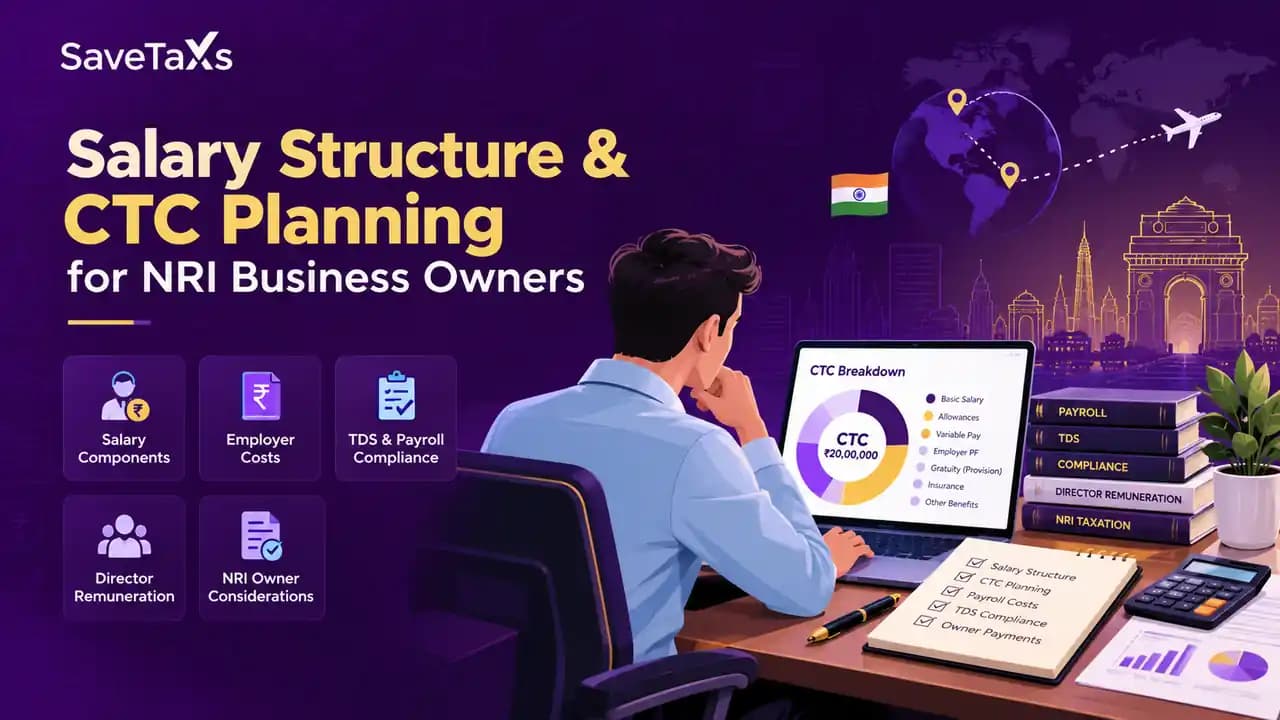
A ₹20 lakh CTC approved by an NRI owner does not mean the employee will receive ₹20 lakh, or that the full amount will be taxable salary. CTC, gross salary, statutory contributions, tax deductions and owner compensation are separate parts of the payroll decision. Confusing them leads to inaccurate budgets, employee disputes and compliance exposure. This guide shows how to build an Indian salary structure, estimate take-home pay and review salary or director remuneration before approving payment.
CTC is the total annual cost that an employer incurs for an employee, while take-home pay is the amount the employee receives after deductions. CTC, or cost to company, includes the employee’s salary and employer-paid items linked to the employment. These items can include basic pay, allowances, bonus, employer contributions, insurance and a provision for gratuity.
Gross salary is the employee’s earnings before deductions from the employee’s pay. It usually includes basic pay, allowances and taxable or non-taxable benefits that form part of the salary package. Employee-side deductions then reduce gross salary to the net or in-hand salary.
The movement is:
CTC → gross salary and employer benefits → employee deductions → estimated take-home pay
For example, an employee may have a CTC of ₹15 lakh, gross earnings of ₹13.5 lakh and annual deductions of ₹2 lakh. The employee’s bank credit would then be close to ₹11.5 lakh, subject to the actual payroll design and tax withholding. The employer’s cost remains ₹15 lakh because the employer contributions and benefits are part of CTC even though they are not paid as monthly cash.
A common mistake is advertising a CTC as though it were the employee’s annual income in hand. That creates dissatisfaction when the appointment letter shows a much lower monthly credit. State the CTC, fixed gross pay, variable pay, employer benefits and expected deductions separately.
Accurate CTC planning lets you budget the real employment cost and communicate the employee’s expected pay before the contract is signed. An NRI owner may approve a salary from abroad while an Indian finance manager handles payroll locally. The owner therefore needs a structure that is clear enough to review without treating every payroll line as take-home salary.
A correct structure answers four questions:
Poor planning causes three common problems. First, the business underestimates the cost because employer contributions, insurance, gratuity and bonus are left out. Second, the employee expects a higher monthly credit because the offer letter describes only CTC. Third, payroll staff apply deductions or reimbursements without the supporting records needed for tax and labour compliance.
The problem is more serious when the owner is also a director, shareholder, partner or overseas resident. A payment that is described as salary must relate to actual employment or services and must be recorded through payroll. A shareholder distribution or withdrawal must not be disguised as salary merely because it is convenient.
An Indian CTC commonly combines fixed salary, variable pay, employer contributions, statutory benefits and selected employment benefits. The exact mix depends on the role, entity, payroll policy, employee location and the conditions attached to each component.
Basic pay is the core salary component. Many other calculations use basic pay or a defined wage base, so setting an unusually low basic salary and shifting the balance into allowances needs careful review.
Allowances can include house rent allowance, conveyance-related amounts, communication support, meal benefits or role-based allowances. An allowance is not automatically tax-free. Its tax treatment depends on the law, the employee’s facts, the purpose of the payment and the records supporting it.
Performance bonuses, sales incentives and annual bonuses form part of CTC when the employer includes them in the package. A variable amount should state whether it is guaranteed, formula-based, discretionary or payable only after a performance review.
Calling a variable amount “fixed” creates a budgeting and employee-relations problem. Calling a guaranteed amount “discretionary” can also lead to disputes.
Employer provident-fund contributions, insurance premiums, gratuity provisions and other employer-paid benefits may be included in CTC. They increase the employer’s cost but do not always increase the employee’s monthly bank credit.
Benefits such as medical insurance, meal support, company-provided equipment and relocation support need clear rules. The payroll team should record whether the item is cash, reimbursement, a benefit in kind or an employer cost that does not pass through the employee’s payslip.
You calculate take-home pay by removing employer-only costs from CTC and then subtracting employee-side deductions from gross salary. Start with the annual CTC and identify each item that the employer pays but does not credit as salary.
A practical calculation has four stages:
The result is an estimate, not a promise of monthly cash flow. Bonus timing, unpaid leave, reimbursement claims, tax declarations and changes in the employee’s income affect the amount credited each month.
Suppose an NRI-owned company approves ₹18 lakh CTC for an employee. The package includes ₹1 lakh of employer-paid insurance and benefits, ₹1.2 lakh of employer contributions, ₹1.8 lakh of annual variable pay and ₹14 lakh of fixed gross salary. The question is whether the employee receives ₹18 lakh. No. The ₹18 lakh is the employer’s maximum planned cost, while monthly salary is based on fixed gross pay after employee deductions and TDS. The payroll team should issue an offer showing each part separately rather than describing the whole package as salary.
The following example is hypothetical and uses simplified assumptions. It is not a calculation of current tax rates or statutory contribution limits.
| Annual component | Amount |
|---|---|
| Fixed gross salary | ₹12,00,000 |
| Annual performance bonus | ₹1,50,000 |
| Employer retirement contribution | ₹72,000 |
| Employer insurance and benefits | ₹48,000 |
| Gratuity provision | ₹30,000 |
| Total CTC | ₹15,00,000 |
If the bonus is not paid every month, the employee’s regular monthly gross salary is based on ₹12 lakh rather than the full CTC. The employee-side deductions then reduce that gross amount. If employee deductions total ₹1.2 lakh for the year and salary TDS totals ₹1.8 lakh, estimated annual in-hand pay would be ₹9 lakh, with the bonus paid separately if the performance conditions are met.
The business should not use this example as a payroll template without inserting the employee’s actual tax declarations, statutory deductions, benefit values and state requirements.
A sound salary structure separates fixed pay, variable pay, benefits, reimbursements and statutory costs in the appointment documents and payroll system. The structure should be commercially justified and easy for the employee, finance team and owner to understand.
Use fixed pay for the amount the employee receives for ordinary service. Use variable pay for compensation tied to measurable conditions. State the payment period, performance measure, approval authority and treatment when the employee joins or leaves during the year.
Reimbursements should repay an actual business expense supported by bills or other records. Do not label a regular monthly cash payment as a reimbursement when the employee receives it without proof of expenditure. That approach can create a tax and payroll dispute.
Benefits should state who pays, who receives the benefit and how the payroll will record it. Insurance, company accommodation, cars, loans, travel and equipment may have different tax and accounting treatment from cash salary.
The 50% salary rule is not a rule that gives every employee half of CTC as take-home pay. It concerns how the wage base is identified for certain statutory calculations when allowances form a large part of the package. Do not design a low-basic, high-allowance structure solely to reduce statutory costs; the payroll team should apply the current wage definition and employment rules to the actual package.
Keep the following documents together:
An employer must review PF, ESI, gratuity, bonus, leave, professional tax and minimum-wage requirements before finalising CTC. The applicable rule depends on the establishment, employee category, wage base, location and current law.
Provident fund is administered through the Employees’ Provident Fund Organisation. Check whether the establishment and employee fall within coverage, which wage base applies, how employee and employer contributions are recorded and whether the payroll system has separate lines for both. Employer PF is part of CTC but employee PF reduces take-home pay.
Employee state insurance is administered by the Employees’ State Insurance Corporation. Check coverage, employee eligibility, contribution treatment and the establishment’s registration obligations before excluding ESI from a package. A payroll team should not assume that a high-level annual CTC alone answers the ESI question.
The Payment of Gratuity Act, 1972 provides a statutory gratuity framework for covered establishments and eligible employees. Gratuity is an employer cost that may be shown as a CTC provision, but a provision in the offer letter does not replace the legal calculation when gratuity becomes payable. Keep service records and salary records that support the calculation.
Bonus, leave and minimum-wage rules also affect the cost. Minimum wages are location- and category-sensitive, so an NRI owner with employees in different Indian states should not use one national salary template without checking the relevant state and employment category.
Professional tax is a state-level payroll matter. Registration, deduction, payment and return requirements vary by state. The payroll register should identify the employee’s work location and show the deduction and payment trail where professional tax applies.
State shops-and-establishments requirements, wage-payment rules, holidays and leave records can also affect the payroll process. These are separate from income-tax deductions and should be reviewed by the local payroll team.
Salary TDS is an employer withholding process, while the employee’s final tax depends on the applicable tax regime, income, declarations and eligible deductions. The employer estimates tax from the information available and deducts it through payroll; the employee reconciles the final position in the annual tax return.
The old and new tax regimes treat deductions, exemptions and salary benefits differently. Do not call an allowance tax-free merely because it appears in a CTC template. The payroll team should collect the employee’s declarations, apply the chosen regime and retain the supporting records.
Salary paid for services should be processed and reported using the applicable payroll and tax procedures. The employee should receive the annual salary certificate issued by the employer and use it for annual reporting. An employee who also has rent, investment, business, foreign or other income needs to consider the complete tax position rather than relying only on payroll TDS.
The Income Tax Department’s salary TDS guidance states that, with effect from 1 October 2024, a person who deducts TDS and fails to pay it to the Central Government can face rigorous imprisonment of three months to seven years and a fine, unless the payment is made by the deadline for filing the relevant TDS statement. This is why an NRI owner should monitor the payroll deposit and reporting process rather than treating TDS as an accounting entry.
For a wider view of the employee or director’s Indian income, read How Indian income is taxed for NRIs and Tax filing for NRIs in India.
An NRI owner should pay salary or director remuneration only for documented services and keep shareholder distributions separate from payroll. Ownership of an Indian business and residential status are separate questions, and neither one automatically decides whether a payment is salary.
A person working as an employee receives salary under an employment arrangement. A director may receive remuneration under the company’s constitutional documents, approvals and applicable company-law requirements. The business should record the role, duties, amount, approval and payment method.
Dividends are paid because of share ownership, not because the shareholder worked a certain number of hours. Drawings are withdrawals relevant to the entity and owner structure, while partner remuneration follows the partnership or LLP agreement and applicable tax rules. A proprietorship does not create a separate employee relationship between the proprietor and the proprietorship in the same way as a company-employer relationship.
For example, Meera lives in Dubai and owns shares in an Indian private company. She travels to India to manage sales and signs an employment or director agreement approved through the company’s required process. The question is whether every payment to her should be processed as salary. No. Payment for her documented services can be processed as salary or director remuneration, while a payment made because she owns shares belongs in the shareholder-distribution analysis. Mixing the two can lead to incorrect TDS, accounting treatment and company records.
Read Who is an NRI for Indian tax purposes? before treating the owner’s residence as the answer to the compensation question. Salary, dividends, rent and other income can have different treatment; the NRI income-tax guide covers that distinction at a broader level.
A legitimate owner payment should also be commercially reasonable, supported by work performed and recorded in the accounts. Related-party approvals, disclosures, transfer-pricing considerations and cross-border rules need separate review where the owner or director is connected with an overseas business.
The owner should approve CTC only after the role, entity, statutory costs, tax treatment, documents and payment route have been reviewed together. A payroll approval should not rely on a single spreadsheet prepared without supporting records.
Use this workflow:
Maintain a clear audit trail. The appointment document, salary annexure, payslips, attendance records, reimbursement bills, approval minutes, tax declarations and deposit evidence should tell the same story.
Before transferring legitimate owner compensation or other personal funds after the payroll and accounting records are complete, read Repatriating money from India.
An NRI-owner payroll checklist should confirm the entity, role, approval, documentation, TDS, statutory payments and cross-border review. Use it before the first payment and again when the compensation changes.
Ask the payroll professional to validate the structure against the entity, employee role, work location, current statutory rules and supporting documents. Give them the proposed CTC sheet, employment or appointment agreement, employee location, benefit details, bonus policy and ownership relationship.
Ask which items belong in CTC, which items pass through gross salary, and which items are employer-only costs. Ask how the old and new tax regimes affect payroll withholding for the employee. Ask whether the proposed salary structure satisfies PF, ESI, gratuity, bonus, leave, professional tax, and minimum-wage requirements.
For an owner or director, ask what professional tax, closures, related-party records and service evidence are needed. Ask how the business will reconcile payroll with the general ledger and annual tax reporting. You can also review the wider Indian business tax-compliance checklist.
Review the salary structure at least annually and whenever tax, payroll, employee-location or statutory rules change. A review should also follow a promotion, relocation, new benefit, change in entity status or change in the owner’s role.
Keep the original CTC sheet beside the revised version. Record why each component changed, who approved it and how the payroll and accounting entries were updated.
Start with the employee’s role and the business entity, then build the CTC from fixed pay, variable pay, employer costs and documented benefits. Keep salary or director remuneration separate from dividends, drawings and partner payments. Before the first payroll run, have the CTC sheet, employment documents, approvals, tax declarations and statutory calculations in front of you. The fact most likely to change the answer is whether the person is being paid for actual services or receiving money because of ownership.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Hatim Dudhiyawala is a Certified Public Accountant (CPA) with SaveTaxs and specializes in Indian and NRI taxation. He advises individuals, NRIs, and businesses on income tax filing, capital gains taxation, DTAA benefits, fund repatriation, and tax compliance. With experience in cross-border tax matters, Hatim helps taxpayers understand complex regulations and make informed decisions. Through his articles, he shares practical insights to help readers stay compliant and manage their tax obligations with confidence. See Full Bio
Want to read more? Explore Blogs