NRI Income Tax Compliance
Income Tax Forms Renamed in 2026: Old vs New Form NumbersIncome Tax Forms Renamed in 2026: Old vs New Form Numbers
Written by Vipul Jain

The DTAA between India and the USA is a tax treaty that coordinates taxing rights when income has a connection with both countries. For NRIs living in the USA, the treaty can affect how Indian rent, interest, dividends, salary, pensions, business income and capital gains are taxed.
However, a DTAA does not automatically make Indian income tax-free. The result depends on your tax residence, the type and source of income, the relevant treaty article, each country's domestic tax rules, and any available foreign tax credit.
The India–USA DTAA can provide relief when the same income is taxed in both countries.
Treaty treatment depends on residence, income type, source and the applicable treaty provision.
Being an NRI under Indian tax law does not automatically determine your treaty residence.
US citizens and resident aliens must consider US worldwide-income rules and the treaty's saving-clause provisions.
Different income types can have different treaty treatment.
Foreign tax credits generally require the income and related foreign tax to be properly reported and documented.
Indian and US filing obligations may continue even when treaty relief is available.
The India–USA Double Taxation Avoidance Agreement (DTAA) is an income-tax treaty between the two countries. It establishes rules for determining how certain categories of income are taxed when they are connected with both India and the USA.
The treaty does not replace domestic tax law. You generally need to determine your position under the applicable domestic rules first and then examine the treaty provisions that apply to your circumstances.
The treaty can, depending on the income and taxpayer, allocate taxing rights, restrict source-country taxation, or provide a mechanism for relief from double taxation. The official treaty text is published by the US Internal Revenue Service.
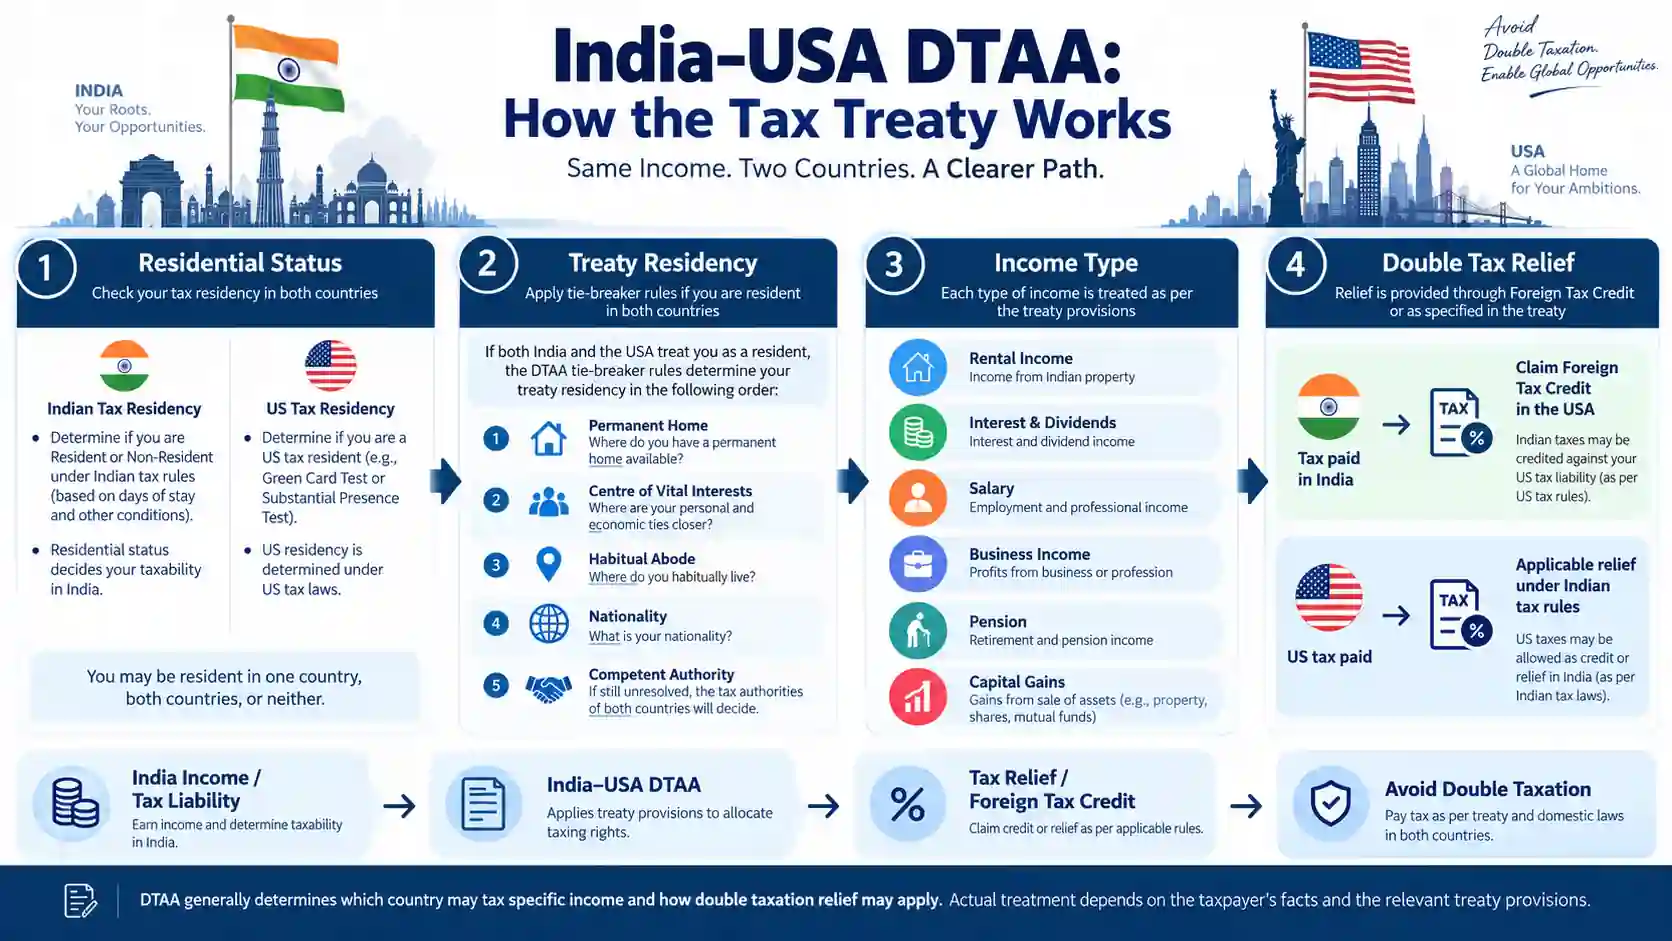
Treaty residence and Indian NRI status are related but are not the same concept.
Your residential status under Indian domestic tax law is determined separately for the relevant tax year. For FY 2025–26, the Income-tax Act, 1961 rules apply; from FY 2026–27, the Income-tax Act, 2025 applies under the new tax-law framework. The current Indian tax authority guidance sets out the applicable residence tests and the transition between the two laws.
After determining domestic residence, a person who may be resident under both countries' rules may need to consider the treaty's residence provisions.
Therefore, do not assume that the statement "I am an NRI" by itself determines your treaty residence.
For a dual-residence situation, keep records such as:
Dates of travel and days spent in India
Permanent home information
Employment and business records
Relevant family and economic connections
Tax-residence documentation
These records can help establish which treaty residence rules apply.
Article 4 of the India–USA treaty contains residence rules for individuals who may be treated as residents of both countries.
The treaty's individual tie-breaker considers factors including:
Permanent home
Closer personal and economic relations
Habitual abode
Nationality
Mutual agreement where the earlier tests do not resolve the position
These treaty tests are considered after the relevant domestic residence rules have been examined.
This means a person should not determine treaty residence simply by looking at the number of days spent in India.
For FY 2025–26, the Indian residential-status rules under the Income-tax Act, 1961 generally use the 182-day test or the 60-day plus 365-day test, subject to specific exceptions and conditions for certain Indian citizens and persons of Indian origin.
For FY 2026–27, the Income-tax Act, 2025 continues the core 182-day or 60-day-plus-365-day framework, with specific provisions and transition rules applying to the new tax year.
Because residential status can affect the scope of Indian taxation, use the rules applicable to the specific tax year rather than relying on an older day-count rule.
The treaty does not apply one tax rule to every type of income. The relevant treaty article and domestic law must be considered for each income source.
Income from immovable property situated in India can be subject to Indian taxation because the property is located in India.
A US tax resident may also need to consider the income under US tax rules and determine whether Indian tax may qualify for foreign tax credit treatment.
Indian-source interest and dividends can be subject to Indian taxation under domestic law. Treaty provisions may affect the taxing rights or applicable withholding treatment depending on the circumstances.
The same income may also need to be included in the US tax analysis for a US tax resident.
Salary requires analysis of factors such as where the services are performed, the employee's residence, the employer and the applicable treaty conditions.
Do not assume that the country paying the salary is automatically the only country that can tax it.
Business income requires consideration of the taxpayer's residence, where the business is conducted and whether the business has a taxable presence in the other country.
A person providing services independently should not automatically apply rules designed for employment income.
Pension and retirement payments require classification before the applicable treaty provision can be determined.
The treatment can differ depending on the nature of the payment and the taxpayer's circumstances. US citizens and resident aliens must also consider applicable US domestic reporting rules.
Capital gains require separate analysis under the treaty and domestic laws.
For example, a US resident selling property situated in India needs to consider Indian taxation of the property transaction as well as the corresponding US tax treatment and potential foreign-tax-credit consequences.
The India–USA treaty contains specific capital-gains provisions, including rules relating to immovable property and specified transportation activities.
The saving clause is particularly important for US citizens and certain US resident taxpayers.
It generally preserves the USA's ability to apply its domestic tax rules to its citizens and residents, subject to specific treaty exceptions. Therefore, being treated as a treaty resident of the USA does not by itself mean that US tax on worldwide income disappears.
For example, a US citizen living in the USA who receives Indian rent cannot assume that the India–USA DTAA makes that income exempt from US taxation.
Instead, the taxpayer should:
Identify the income.
Determine where it is sourced.
Apply the relevant Indian rules.
Apply the relevant US rules.
Check the applicable treaty provision.
Determine whether foreign tax credit relief is available.
A foreign tax credit (FTC) can provide relief when qualifying foreign income taxes have been paid or accrued and the same income is also subject to tax in the other country.
The credit is not simply a refund of every foreign tax payment. The tax must satisfy the applicable country's credit rules and be matched with the relevant income.
For an Indian resident claiming credit for eligible foreign tax, Form 67 and supporting documentation may be relevant. The Indian Income Tax Department provides specific guidance on foreign-tax-credit claims and supporting evidence.
A US individual may generally use Form 1116 to claim a foreign tax credit for qualifying foreign taxes, subject to the applicable rules and limitations. The IRS's current Form 1116 instructions explain which foreign taxes may qualify and how the credit is calculated.
For example, if Indian tax is paid on Indian-source income that is also taxable in the USA, the taxpayer must determine whether that Indian tax qualifies for the US foreign tax credit and apply the applicable limitation rules. The credit is not automatically equal to the entire amount of Indian tax paid.
A Tax Residency Certificate (TRC) is evidence of tax residence issued by the relevant foreign tax authority.
For an individual seeking DTAA relief in India, the Income Tax Department states that a certificate of residence from the relevant foreign country is required. Form 10F provides prescribed information where the required details are not already contained in the TRC. Form 10F is linked to Section 90 and Section 90A of the Income-tax Act and Rule 21AB.
The exact documentation required depends on the taxpayer and the treaty claim, so retain the relevant residency and supporting records.
Keep records that allow the income, tax payment and treaty position to be verified, including:
India and US tax returns
Travel and residence records
Rental agreements and property records
Bank interest and dividend statements
Salary and pension documents
Property-sale documents
Indian tax-payment records
Withholding certificates
Foreign-tax statements
TRC and Form 10F documentation, where applicable
Foreign-tax-credit calculations
Keeping the same income amounts and supporting documents consistent across both countries can make the reporting and credit process easier to review.
Avoid these common errors:
Treating NRI status as the same as treaty residence
Using an outdated residential-status rule
Applying a treaty provision without checking eligibility
Assuming all Indian tax automatically qualifies for US foreign tax credit
Ignoring the US savings clause
Treating every type of income in the same way
Claiming a foreign tax credit without matching the tax to the relevant income
Failing to retain supporting documents
The applicable rule can change based on your tax residence, income type, citizenship, filing status and tax year.
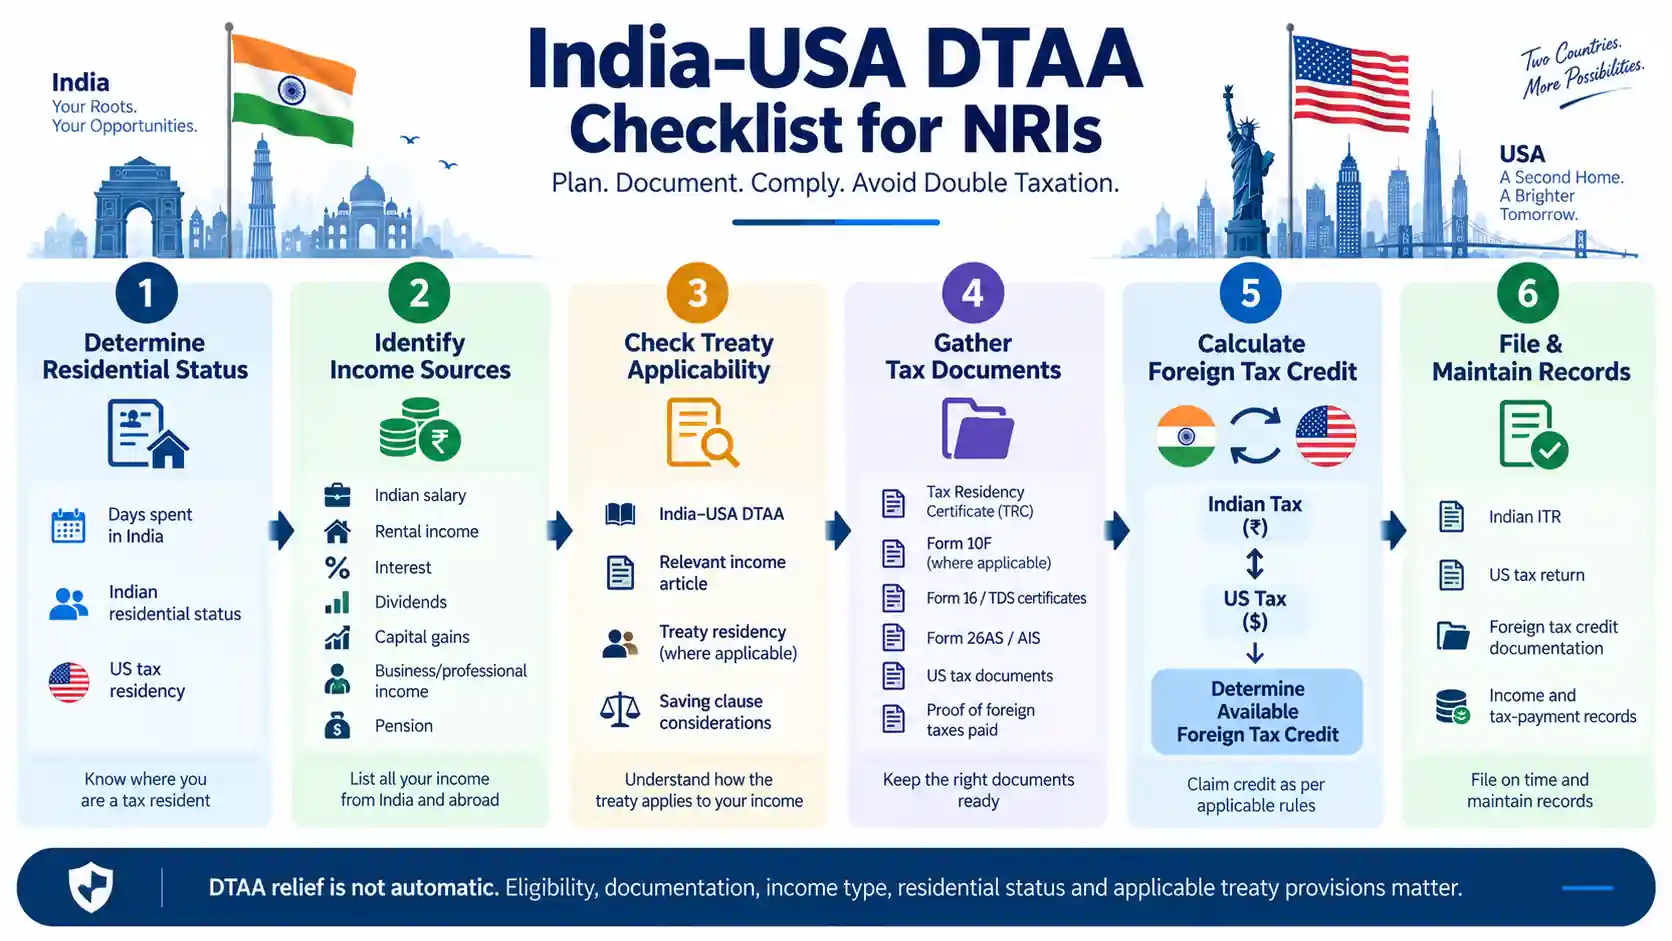
Before claiming treaty relief, work through these steps:
Determine your Indian residential status for the relevant tax year.
Determine your US tax status.
Check whether dual residence needs to be considered.
Classify each India-linked income source.
Identify the relevant treaty article.
Determine each country's taxing rights.
Calculate the tax paid or payable on the same income.
Check whether foreign tax credit or another form of treaty relief is available.
Collect the required forms and supporting documents.
Report the income correctly in the applicable return.
If you would rather not work this out yourself, SaveTaxs can help with filing an Indian income-tax return for NRIs
The India–USA DTAA can help coordinate taxation when income has connections with both countries, but it does not create one universal tax rule for every NRI.
Your result depends on your residential status, the tax year, income type, source of income, treaty provision, domestic tax rules and available foreign-tax-credit mechanism.
For an accurate position, start with your residence status and then analyse each India-linked income separately. Keep your travel records, tax statements, withholding documents and supporting evidence together before claiming treaty relief.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio
Want to read more? Explore Blogs