NRI Income Tax Compliance
TDS on Payments to NRI FreelancersTDS on Payments to NRI Freelancers
Written by Vipul Jain

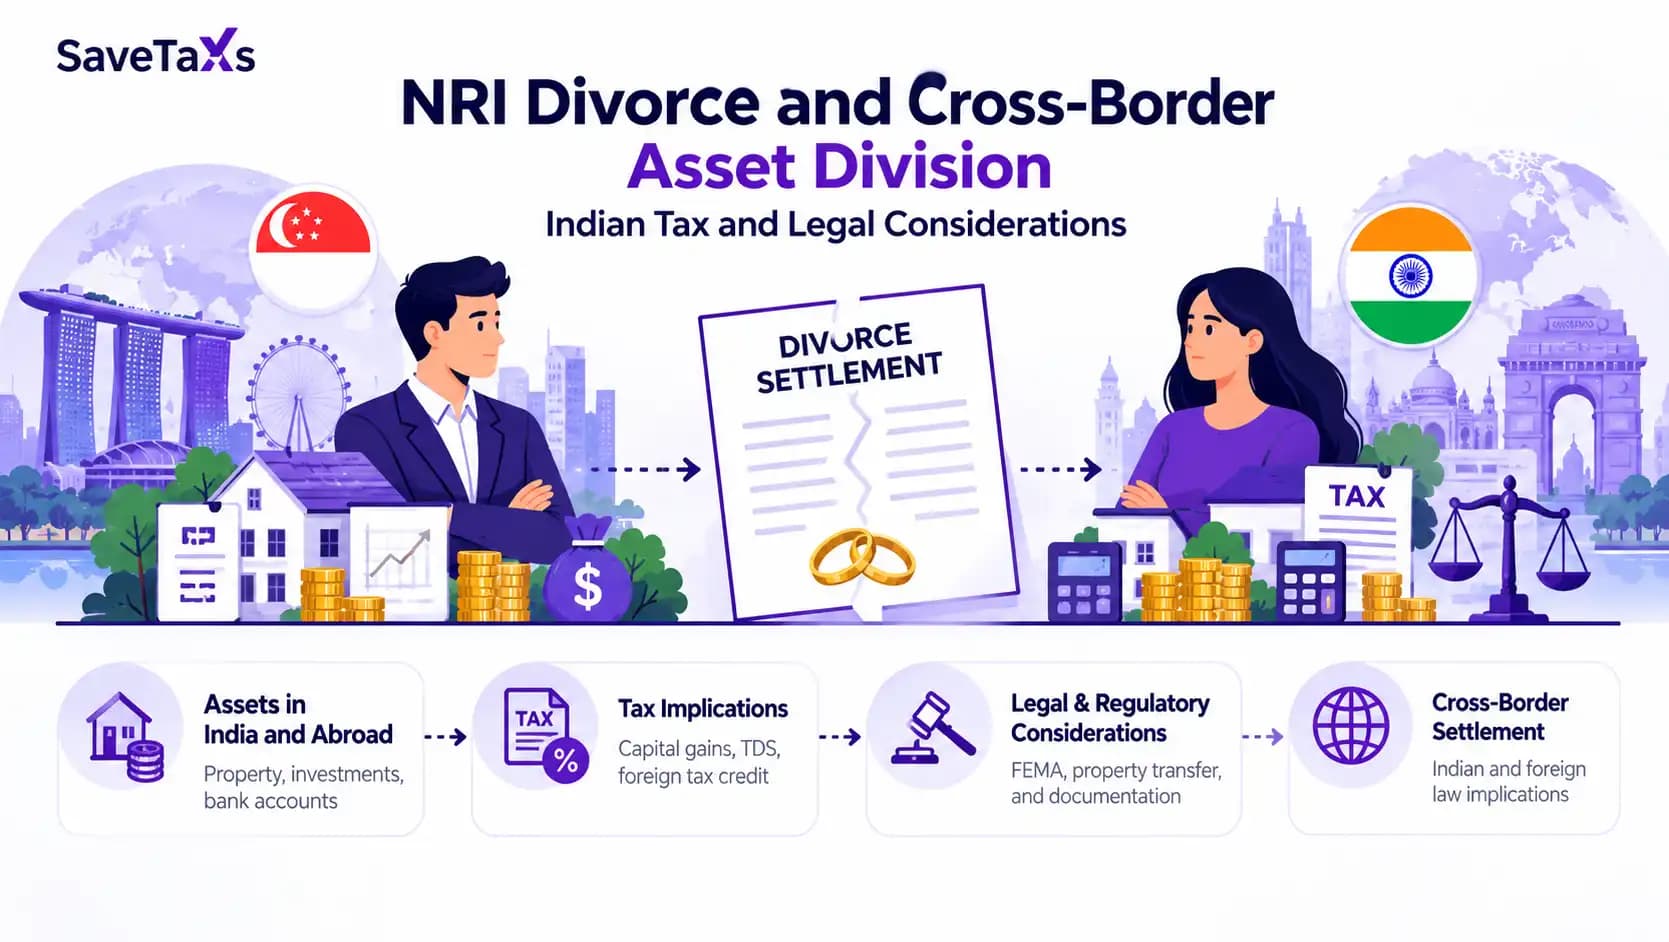
Divorce becomes more complicated when you are an NRI and you and your spouse own assets in India and abroad. An overseas divorce settlement may decide who receives a property, investment, or settlement amount, but that does not automatically resolve the Indian tax, FEMA, registration, or legal requirements.
For example, an NRI couple living in the US may jointly own a flat in India, maintain NRE/NRO accounts, and hold investments in both countries. Dividing these assets requires more than simply assigning a value to each spouse.
This guide explains the main Indian tax and legal considerations involved in NRI divorce and cross-border asset division.
A cross-border divorce involving Indian assets may involve several types of assets:
Each significant asset should be considered separately.
Suppose an NRI couple living in Dubai jointly owns an apartment in Mumbai. They also have investments in the UAE. Under their settlement, one spouse keeps the UAE investments while the other takes full ownership of the Mumbai property.
Although the values may be similar, transferring ownership of Indian real estate is legally different from allocating foreign investments.
For each asset, determine who currently owns it, where it is located, its value, the residential status of both spouses, the proposed method of transfer, and how ownership will change after divorce.
This asset-by-asset analysis is particularly important for NRI divorce settlements involving Indian assets because different jurisdictions can apply different legal and tax rules to the same settlement.
From calculation to compliance, we ensure your gains are tax-optimized
One of the biggest misconceptions about NRI property division after divorce is that any transfer mentioned in a divorce settlement is automatically exempt from Indian tax.
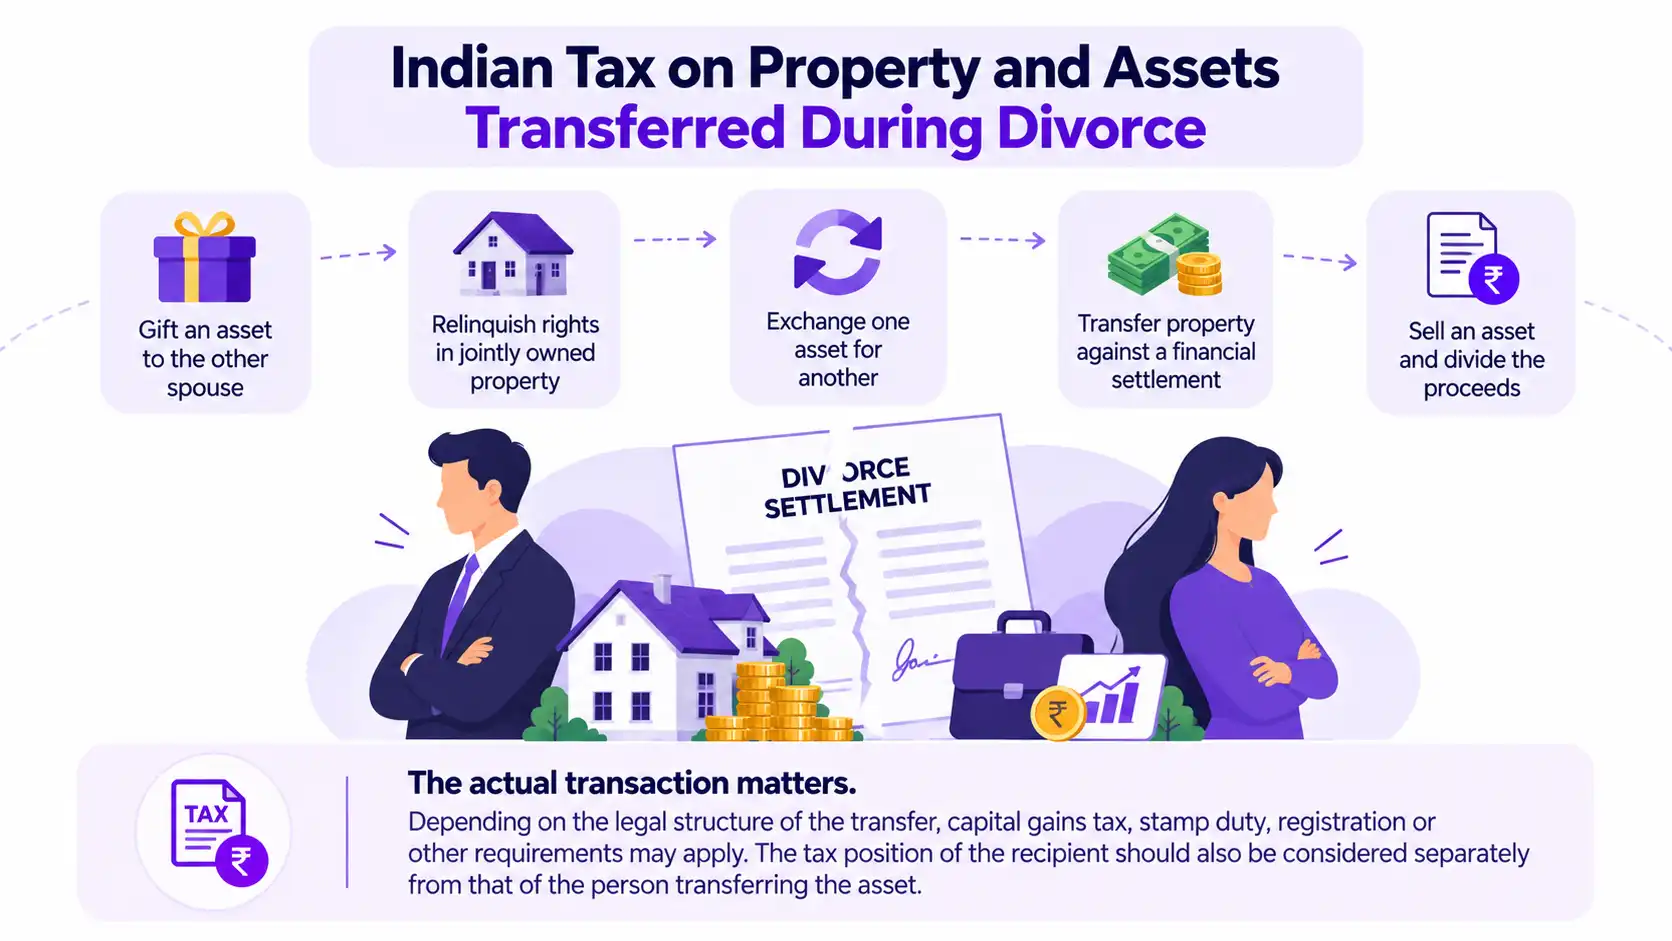
The actual transaction matters.
A spouse might:
These arrangements can have different tax consequences.
Indian income-tax rules provide specific treatment for money or property received without consideration from specified relatives, and a spouse falls within the relevant relationship category while the marriage subsists. However, a divorce settlement should first be examined based on its legal structure, because the transfer may involve a gift, exchange, relinquishment of rights, consideration, or settlement of matrimonial claims. The timing of the transfer also matters, particularly where the marriage has legally ended.
The tax position of the recipient should also be considered separately from that of the person transferring the asset.
For example, assume an NRI husband gives up his 50% interest in a Bengaluru apartment and receives investments under the divorce settlement.
The transaction needs to be examined to determine whether it represents a gift, exchange, relinquishment of rights, or another form of transfer. Depending on its legal structure, capital gains, stamp duty, registration, or other requirements could become relevant.
Therefore, do not assume that the tax on divorce settlement in India can be determined simply because a transfer forms part of a divorce agreement.
Alimony and asset division should not be treated as the same thing.
An NRI divorce settlement might provide for:
Indian judicial decisions have distinguished certain one-time alimony settlements from recurring maintenance.
A notable example is Princess Maheshwari Devi of Pratapgarh v. CIT, where the Bombay High Court distinguished lump-sum alimony from recurring monthly payments. The lump-sum alimony in that case was treated as a capital receipt rather than taxable income.
However, this does not mean every lump-sum payment received after divorce is automatically tax-free.
The purpose and terms of the payment remain important.
Recurring maintenance can have a different tax character. In Princess Maheshwari Devi of Pratapgarh v. CIT, the recurring monthly alimony was held to be income on the facts of that case.
Therefore, when considering the Indian tax treatment of alimony for an NRI, the settlement should clearly identify whether a payment represents lump-sum alimony, recurring maintenance, consideration for property rights, or another type of settlement.
FEMA [Foreign Exchange Management Act] is one of the main reasons an NRI divorce differs from a domestic divorce.
FEMA rules for divorce settlement can become relevant when Indian property, investments, or money are transferred between a resident and a non-resident.
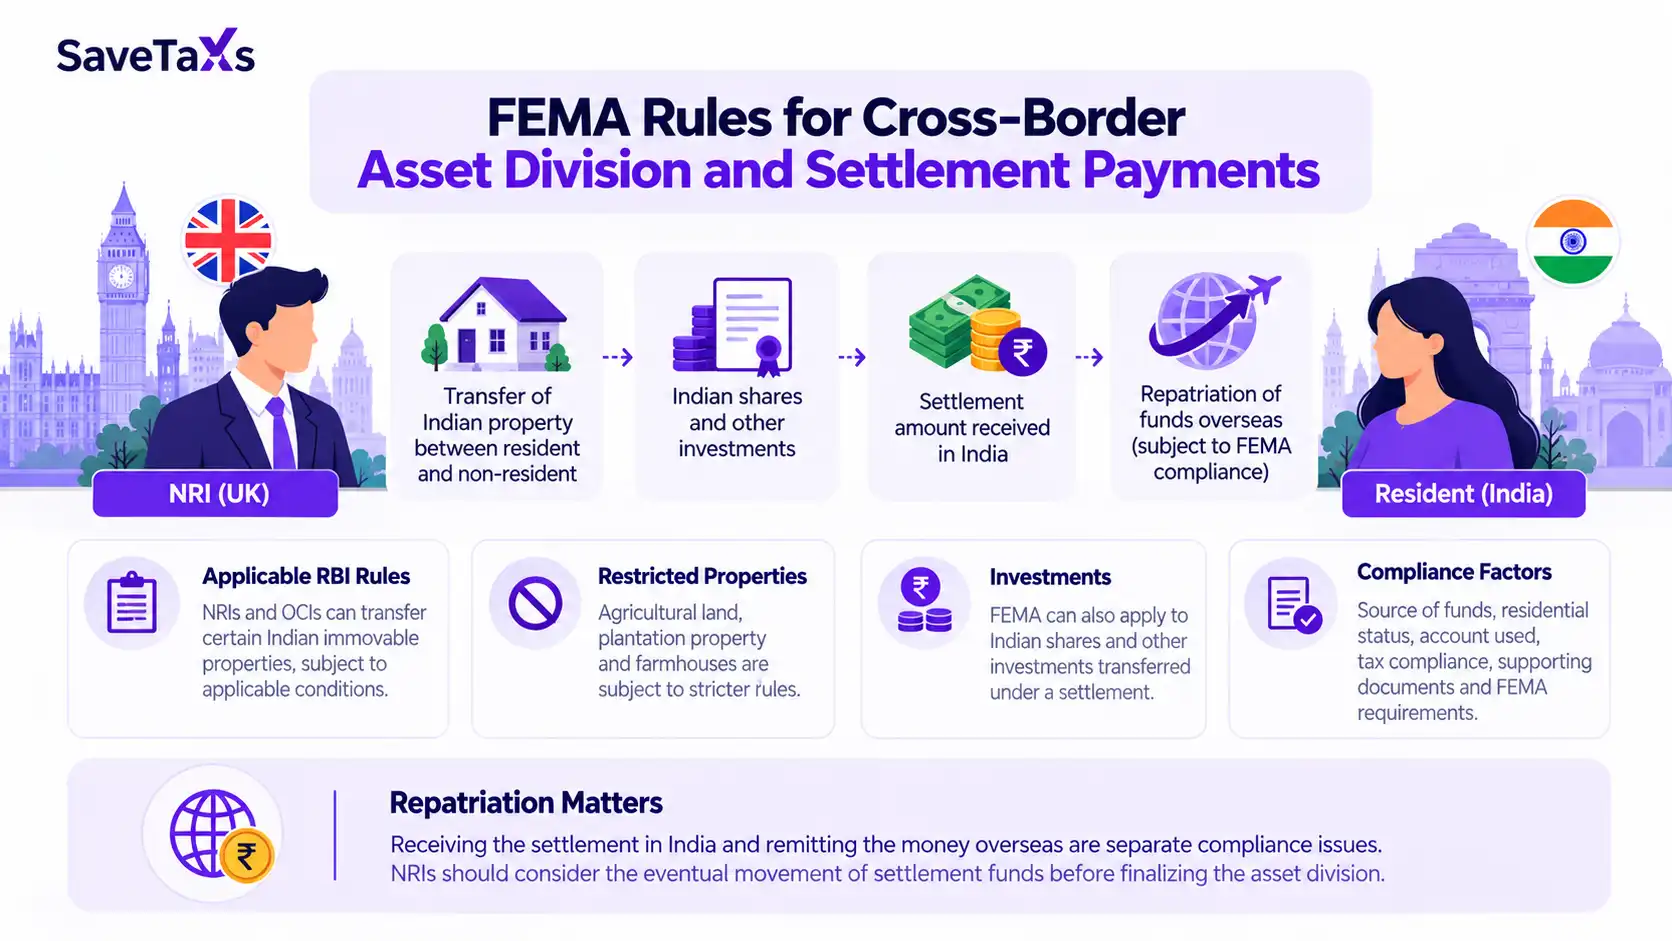
For example, an NRI husband living in the UK may agree to transfer his interest in an Indian apartment to his wife, who has permanently returned to India.
The transaction must be checked against the FEMA rules applicable to the parties and the property.
RBI rules permit NRIs and OCIs to transfer certain Indian immovable properties subject to applicable conditions, including the residential status of the transferor and transferee. Agricultural land, plantation property, and farmhouses are subject to more restrictive rules.
FEMA can also matter when the settlement involves Indian shares or other investments.
Another important issue is repatriation.
Suppose an NRI living in Canada receives ₹50 lakh in India under a divorce settlement and wants to transfer the money to Canada.
Receiving the settlement and remitting the money overseas are separate compliance issues.
The applicable route can depend on the source of funds, residential status, account used, tax compliance, supporting documents, and FEMA requirements.
NRIs should therefore consider the eventual movement of settlement funds before finalizing the asset division.
An NRI may obtain a divorce decree in the US, UK, UAE, Canada, or another country while continuing to own assets in India.
However, a foreign divorce or asset-division order should not automatically be assumed to transfer ownership of Indian property.
Indian law contains rules governing when foreign judgments are considered conclusive. Under Section 13 of the Code of Civil Procedure, 1908, issues such as the foreign court's jurisdiction, whether the decision was on the merits, natural justice, fraud, and consistency with Indian law can become relevant.
Even where the foreign divorce itself is recognized, implementing an asset-division order may require additional steps in India.
For Indian real estate, these could include appropriate transfer documentation, registration, stamp duty, FEMA compliance, and updating ownership records.
For example, if a US divorce order states that one spouse should receive an apartment in Delhi, the couple should not assume that the foreign order alone has completed every Indian property-transfer requirement.
The foreign judgment and the implementation of the Indian asset transfer should therefore be examined separately.
Get CA-approved NRI investment strategies tailored to your financial goals.
NRI divorce and cross-border asset division require more than deciding which spouse receives each asset.
Indian property, foreign investments, lump-sum alimony, recurring maintenance, and settlement money can have different tax and legal consequences. FEMA adds another layer when a resident and non-resident transfer assets or when settlement money needs to leave India.
Before finalizing a significant cross-border divorce settlement, NRIs should identify each asset separately and check its ownership, location, proposed transfer method, Indian tax treatment, FEMA implications, and foreign-country consequences.
Planning these issues before transferring assets can help prevent a settlement that works on paper but creates tax, remittance, or ownership problems when it is implemented.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Hatim Dudhiyawala is a Certified Public Accountant (CPA) with SaveTaxs and specializes in Indian and NRI taxation. He advises individuals, NRIs, and businesses on income tax filing, capital gains taxation, DTAA benefits, fund repatriation, and tax compliance. With experience in cross-border tax matters, Hatim helps taxpayers understand complex regulations and make informed decisions. Through his articles, he shares practical insights to help readers stay compliant and manage their tax obligations with confidence. See Full Bio
Want to read more? Explore Blogs