NRI Income Tax Compliance
Income Tax Forms Renamed in 2026: Old vs New Form NumbersIncome Tax Forms Renamed in 2026: Old vs New Form Numbers
Written by Vipul Jain
If you earn income from India while living abroad, you may already know that Indian-source income can create an Indian tax liability. However, NRI tax deductions and exemptions depend on the specific provision, your income type, and the tax regime you choose. In this guide, you will learn which deductions and capital-gains exemptions may apply for AY 2026–27, what limits matter, and how to avoid common NRI tax-claim mistakes.
NRIs can claim eligible Indian tax deductions, but each deduction has its own eligibility conditions and cannot be assumed to apply simply because it is available to residents.
Section 80C allows a combined deduction of up to ₹1.5 lakh for qualifying payments and investments under the old tax regime. — Source: Income Tax Department, 2026.
Sections 80D, 80E, 80G, 80CCD and 80TTA can provide additional deductions to eligible NRIs under the applicable provisions.
Section 24(b) can provide a deduction for eligible home-loan interest, with different treatment for self-occupied and let-out property.
Sections 54, 54F and 54EC can provide capital-gains exemptions when their specific conditions are satisfied.
The new tax regime is the default regime for AY 2026–27, while eligible taxpayers can opt for the old regime and claim deductions that are unavailable under the new regime.
NRIs should compare both regimes using their actual income and eligible deductions instead of assuming that the old or new regime is automatically better.
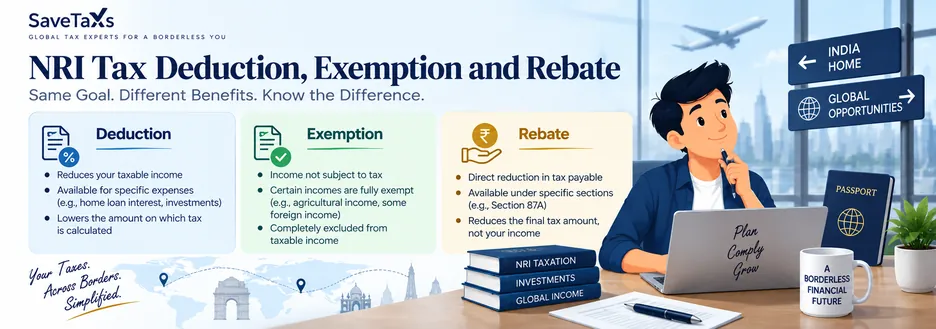
Tax deductions and exemptions for NRIs are provisions under Indian tax law that can reduce taxable income or exclude qualifying income from taxation. An NRI can claim a tax benefit only when the relevant provision applies and all prescribed conditions are satisfied.
First, a tax deduction reduces taxable income after the relevant income is considered. For example, an eligible NRI using the old tax regime may claim qualifying Section 80C payments up to the statutory combined limit.
Second, a tax exemption excludes qualifying income or gains from taxation when the conditions of the applicable provision are met. For example, an eligible long-term capital gain may qualify for relief under Section 54 when the prescribed reinvestment conditions are fulfilled.
At the same time, deductions and exemptions are not the same as a tax rebate. A deduction generally reduces taxable income, while a rebate reduces tax payable after the tax calculation.
The Income Tax Department's AY 2026–27 guidance specifically lists deductions applicable to Non-Resident Individuals, including Section 80C, Section 80D, Section 80E, Section 80G, Section 80TTA and other provisions. — Source: Income Tax Department, 2026.
Tax deductions and exemptions are important for NRIs because they can reduce Indian taxable income or qualifying capital gains when the legal conditions are met. This becomes particularly relevant when you receive rent, salary, interest, investment income or capital gains from India.
Moreover, the tax regime directly affects which deductions you can use. For AY 2026–27, the new tax regime is the default regime, but eligible taxpayers can opt for the old regime. — Source: Income Tax Department, 2026.
For example, an NRI with qualifying 80C investments and 80D insurance premiums may find that those deductions materially affect the old-regime calculation, while they generally cannot be claimed under the new regime.
Most importantly, a deduction does not represent an equal amount of tax saving. A ₹1 lakh deduction reduces taxable income by up to ₹1 lakh; the actual tax saving depends on the applicable tax rate and other factors.
NRIs can claim several deductions under Indian tax law, subject to the relevant conditions and tax regime. The principal provisions include Sections 80C, 80CCD, 80D, 80E, 80G, 80TTA and Section 24(b).
| Section | Main benefit | Important limit or rule | Availability |
|---|---|---|---|
| 80C | Specified investments and payments | Combined limit of ₹1.5 lakh | Old regime |
| 80CCD(1B) | Additional NPS contribution | Up to ₹50,000 | Old regime |
| 80CCD(2) | Eligible employer NPS contribution | Subject to salary-based limits | Subject to regime |
| 80D | Health insurance and eligible medical expenditure | Depends on age and category | Old regime |
| 80E | Education-loan interest | Eligible interest paid | Old regime |
| 80G | Qualifying charitable donations | Depends on donation category | Old regime |
| 80TTA | Savings-account interest | Up to ₹10,000 | Old regime |
| 24(b) | Home-loan interest | Depends on property and regime | Old and specified new-regime cases |
The Income Tax Department's AY 2026–27 NRI guidance confirms these provisions and the relevant limits. — Source: Income Tax Department, 2026.
Section 80C provides a deduction for specified investments and payments, subject to a combined maximum deduction of ₹1.5 lakh under the old regime. — Source: Income Tax Department, 2026.
First, qualifying payments can include life-insurance premiums, provident-fund contributions, specified equity investments, tuition fees, National Savings Certificates and eligible housing-loan principal repayment. The exact eligibility depends on the conditions attached to each item. — Source: Income Tax Department, 2026.
For example, an NRI who repays the principal component of an eligible home loan for an Indian property may be able to include that amount within the Section 80C limit.
Importantly, the ₹1.5 lakh amount is a combined ceiling, not ₹1.5 lakh for each qualifying investment.
Section 80CCD covers qualifying contributions to the National Pension System. Section 80CCD(1B) allows an additional deduction of up to ₹50,000 for qualifying NPS contributions under the old regime. — Source: Income Tax Department, 2026.
For example, if an eligible NRI contributes ₹50,000 to NPS and satisfies the applicable conditions, the contribution can potentially qualify for the additional deduction under Section 80CCD(1B).
Section 80CCD(2) operates differently because it concerns eligible employer contributions to the pension scheme. For AY 2026–27, the Income Tax Department lists a deduction of 14% of salary for specified employer contributions under the new-regime NRI guidance. — Source: Income Tax Department, 2026.
Section 80D provides deductions for eligible health-insurance premiums, preventive health check-ups and specified medical expenditure. The applicable limit depends on whether the payment relates to the taxpayer and family or to parents, and whether the relevant person is a senior citizen. — Source: Income Tax Department, 2026.
For AY 2026–27, the official guidance provides a ₹25,000 limit for self/spouse/dependent children, increasing to ₹50,000 where the relevant person is a senior citizen. A separate ₹25,000 or ₹50,000 limit applies for eligible parents, depending on age. — Source: Income Tax Department, 2026.
For example, an NRI paying ₹23,000 for qualifying health insurance for self and ₹48,000 for an eligible senior-citizen parent may have potentially deductible amounts of ₹23,000 and ₹48,000, subject to the provision's conditions.
Section 80E provides a deduction for eligible interest paid on a qualifying higher-education loan taken for the taxpayer or a relative. — Source: Income Tax Department, 2026.
For example, an NRI repaying interest on a qualifying education loan can claim the eligible interest under the old regime if the loan and education satisfy the statutory requirements.
Unlike Section 80C, Section 80E is focused on interest paid on the qualifying loan, rather than the principal repayment.
Section 80G provides deductions for qualifying donations made to prescribed funds and charitable institutions, with the applicable percentage depending on the category of donation. — Source: Income Tax Department, 2026.
For example, a qualifying donation may receive a 50% or 100% deduction depending on the recipient and statutory category.
Importantly, cash donations exceeding ₹2,000 do not qualify for a Section 80G deduction. — Source: Income Tax Department, 2026.
Section 80TTA provides an eligible individual who is not a senior citizen with a deduction of up to ₹10,000 on interest received from qualifying savings-bank accounts. — Source: Income Tax Department, 2026.
For example, if qualifying savings-account interest is ₹8,000, the deduction can be up to ₹8,000. If qualifying interest is ₹15,000, the deduction is capped at ₹10,000, subject to the section's conditions.
Importantly, the official AY 2026–27 NRI guidance lists Section 80TTA for Non-Resident Individuals, so it should not be incorrectly described as a resident-only deduction. — Source: Income Tax Department, 2026.
However, 80TTA applies to qualifying savings-account interest, not every type of bank interest. Fixed-deposit and recurring-deposit interest should not automatically be treated as eligible 80TTA income.
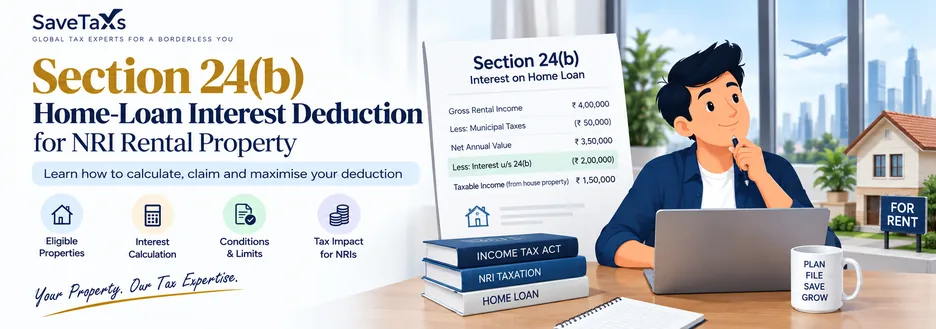
NRIs can claim eligible home-loan interest under Section 24(b), but the treatment depends on the property type, loan purpose and tax regime. — Source: Income Tax Department, 2026.
First, for an eligible self-occupied property under the old regime, the interest deduction can be available up to ₹2 lakh, subject to the applicable conditions. — Source: Income Tax Department, 2026.
Second, for a let-out property, the official guidance permits the actual eligible interest under Section 24(b). Under the old regime, house-property loss can be set off against other heads up to ₹2 lakh in the assessment year, with eligible unabsorbed loss carried forward subject to the applicable rules. — Source: Income Tax Department, 2026.
For example, an NRI earning rent from an Indian property and paying substantial qualifying home-loan interest should calculate the house-property income first, rather than simply subtracting the entire interest from total income.
Under the new regime, interest on a let-out property can still be considered under Section 24(b), but the resulting house-property loss cannot be set off against other heads or carried forward under the stated new-regime rules. — Source: Income Tax Department, 2026.
Capital-gains exemptions are provisions that can reduce qualifying capital gains when the taxpayer reinvests in specified assets or satisfies other statutory conditions. NRIs can potentially use provisions such as Sections 54, 54F and 54EC when their individual circumstances satisfy the requirements.
Section 54 can provide relief where an eligible taxpayer has a qualifying long-term capital gain from the transfer of a residential house and makes the prescribed investment in another residential house. The purchase and construction timelines must be satisfied.
For example, an NRI selling an eligible Indian residential property and reinvesting the qualifying capital gain in another residential property within the prescribed period may claim the applicable exemption.
The exemption is not automatic merely because the seller is an NRI. The nature of the original asset, type of capital gain, new property and reinvestment timing must all be checked.
Section 54F can provide relief on eligible long-term capital gains arising from assets other than a residential house when the taxpayer invests in a qualifying residential house and satisfies the section's conditions.
For example, an NRI selling a qualifying long-term asset such as shares may potentially consider Section 54F if the prescribed residential-property and ownership conditions are satisfied.
The exemption under Section 54F can be proportionate when the required investment does not cover the full qualifying consideration, so the calculation should not be treated as identical to Section 54.
Section 54EC can provide an exemption for eligible long-term capital gains from qualifying land or building when the taxpayer invests in specified bonds within the prescribed period.
For AY 2026–27, the ITR validation rules continue to recognize Section 54EC claims and apply a ₹50 lakh investment ceiling for the relevant claim. — Source: Income Tax Department, 2026.
For example, an NRI with an eligible long-term capital gain from an Indian property may consider specified Section 54EC bonds instead of purchasing another residential property, provided all statutory conditions are met.
The old and new tax regimes differ mainly in their tax rates and availability of deductions and exemptions. For AY 2026–27, the new regime is the default, but eligible taxpayers can opt for the old regime. — Source: Income Tax Department, 2026.
| Tax benefit | Old regime | New regime |
|---|---|---|
| Section 80C | Available | Generally not available |
| Section 80D | Available | Generally not available |
| Section 80E | Available | Generally not available |
| Section 80G | Available | Generally not available |
| Section 80TTA | Available | Generally not available |
| Section 80CCD(1B) | Available | Generally not available |
| Section 80CCD(2) | Available subject to conditions | Available subject to conditions |
| Section 24(b), self-occupied property | Up to ₹2 lakh, subject to conditions | Not available under the new-regime rules |
| Section 24(b), let-out property | Eligible interest subject to rules | Eligible interest, but house-property loss restrictions apply |
The Income Tax Department's NRI guidance specifically identifies Section 24(b) for qualifying let-out property and Section 80CCD(2) among deductions available under the new regime. — Source: Income Tax Department, 2026.
For non-business income, an eligible taxpayer can generally exercise the option to change from the default new regime through the ITR by the applicable filing deadline. Taxpayers with business or professional income have additional Form 10-IEA requirements. — Source: Income Tax Department, 2026.
The better tax regime is therefore the one that produces the lower compliant tax liability after your actual income and eligible deductions are considered.
NRI tax benefits should not be claimed simply because the same expense or investment receives a deduction for another taxpayer. Eligibility must be checked against the relevant section and tax regime.
First, deductions such as 80C, 80D, 80E, 80G and 80TTA generally belong to the old-regime calculation and should not be deducted when calculating taxable income under the new regime.
Second, a capital-gains exemption requires the taxpayer to satisfy the specific reinvestment and asset conditions. Owning an Indian property or investing money after a sale does not automatically create an exemption.
Third, an expense must qualify under the relevant provision. For example, not every bank-interest payment qualifies for 80TTA, and not every charitable payment qualifies for 80G.
An NRI should verify the tax section, eligibility condition, monetary limit and selected regime before entering any deduction in the ITR.
Tax documents help establish the amount and eligibility of deductions reported in an Indian income-tax return. Keeping these records before filing can make the calculation and reconciliation process significantly easier.
For Section 80C, retain relevant investment or payment records and policy or document identification details. For Section 80D, retain the insurer name, policy number and premium information required for the return. — Source: Income Tax Department, 2026.
For NPS deductions, maintain contribution details and the PRAN where required. For Section 80E, retain lender and loan-account details and the interest amount. — Source: Income Tax Department, 2026.
For house-property deductions, keep the loan account information, lender details, outstanding loan amount and eligible interest certificate.
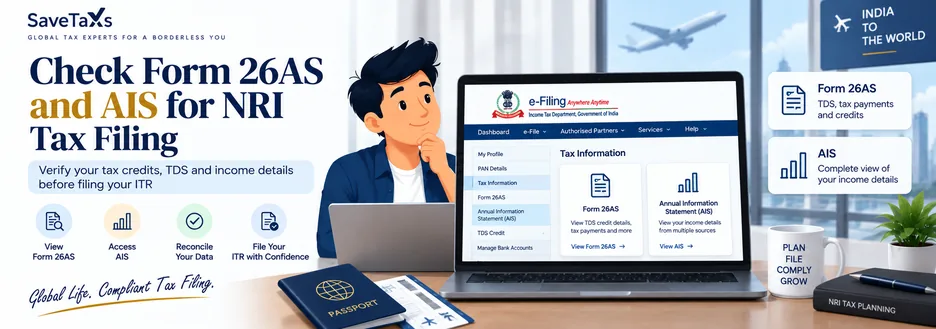
Also reconcile your income and TDS information using Form 26AS and the Annual Information Statement (AIS) before filing. The Income Tax Department identifies both as sources of tax and transaction information available to taxpayers through the e-Filing portal. — Source: Income Tax Department, 2026.
An NRI should choose the tax regime by comparing the actual tax liability under both regimes after applying only the deductions legally available under each.
First, calculate all taxable Indian income. Second, identify deductions available under the old regime. Third, calculate the new-regime liability without deductions that are prohibited under Section 115BAC. Finally, compare the results.
For example, an NRI with significant Section 80C, 80D and 80TTA benefits may have a different outcome from an NRI whose income mainly consists of rental income with substantial home-loan interest.
The Income Tax Department also provides an Income and Tax Estimator that can help taxpayers compare tax calculations using applicable income and deduction information. — Source: Income Tax Department, 2026.
The next step is to match your Indian income with the deductions and exemptions that legally apply to that income.
Use this checklist before filing your AY 2026–27 return:
Confirm your residential status for FY 2025–26.
List every Indian income source, including salary, rent, interest and capital gains.
Identify your applicable tax regime.
Calculate eligible deductions under Sections 80C, 80D, 80E, 80G, 80CCD, 80TTA and Section 24(b), where applicable.
Check capital-gains exemptions under Sections 54, 54F or 54EC when relevant.
Collect supporting documents for every deduction.
Reconcile Form 26AS and AIS with your income and TDS.
Compare the final tax liability under both regimes before filing.
Select the appropriate ITR form based on your income sources.
For AY 2026–27, the Income Tax Department states that ITR-2 is applicable to NRIs without business or professional income, while ITR-3 applies where business or professional income is involved. — Source: Income Tax Department, 2026.
Tax deductions and exemptions can help NRIs reduce their Indian tax liability, but the benefit depends on the specific provision, income type, eligibility conditions and tax regime. For AY 2026–27, important deductions include Sections 80C, 80D, 80E, 80G, 80CCD, 80TTA and Section 24(b), while capital-gains provisions such as Sections 54, 54F and 54EC can provide separate relief when their conditions are met.
Ultimately, the right approach is not to claim every tax benefit mentioned online. Identify your Indian income, verify your eligibility, compare both tax regimes, maintain supporting documents and then file the appropriate ITR.
If your tax situation involves multiple properties, substantial capital gains, business income or complex cross-border transactions, professional NRI tax advice can help ensure that deductions and exemptions are claimed correctly.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Vipul Jain is the Co-Founder of SaveTaxs and a tax expert with experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA, and compliance matters. He focuses on making complex tax concepts simple and helping taxpayers make informed, compliant decisions. See Full Bio

Want to read more? Explore Blogs