NRI Income Tax Compliance
Income Tax Forms Renamed in 2026: Old vs New Form NumbersIncome Tax Forms Renamed in 2026: Old vs New Form Numbers
Written by Vipul Jain

Section 80D of the Income-tax Act, 1961 allows eligible individuals and Hindu Undivided Families (HUFs) to claim a deduction for qualifying health insurance premiums and certain medical expenses, and individuals may also claim preventive health check-ups. The deduction can reduce taxable income when the taxpayer meets the applicable conditions.
For NRIs who earn taxable income in India, understanding Section 80D can help when planning eligible health insurance payments for themselves, their family, or their parents. However, the deduction depends on the applicable tax regime, the tax year, and the nature of the payment.
Important for 2026: Section 80D applies to the earlier-law framework, including returns for Assessment Year (AY) 2026–27. For Tax Year 2026–27 onward, refer to Section 126 of the Income-tax Act, 2025 and the applicable tax-regime rules.
Section 80D provides a deduction for specified health-related payments made by eligible individuals and HUFs. These may include:
The deduction reduces taxable income; it is not a direct refund of the amount spent. The amount you can claim depends on the eligible expense, the age of the insured person, the relevant limit, and the Applicable tax regime.
Under the Income-tax Act, 1961, the usual limits for an individual are as follows:
| Eligible payment | Maximum deduction |
|---|---|
| Self, spouse, and dependent children | ₹25,000 |
| Self and family, where the relevant insured person is a resident senior citizen | ₹50,000 |
| Parents below 60 years | Additional ₹25,000 |
| Parents who are resident senior citizens | Additional ₹50,000 |
| Preventive health check-up | ₹5,000, included within the applicable overall limit |
| Eligible medical expenses for a senior citizen without health insurance | Up to ₹50,000, subject to the applicable aggregate limit and conditions |
The maximum deduction can reach ₹1,00,000 where both the self-and-family group and the parents' group qualify for the higher ₹50,000 limits.
Important: The ₹5,000 preventive health check-up limit is part of the overall Section 80D limit. It cannot be claimed over and above the relevant limit.
Understand eligible deductions and file your Indian taxes with confidence.
Under the earlier-law provision, eligible taxpayers include:
An individual may claim qualifying expenses for:
The parents do not have to be dependent on the taxpayer for the parent-related deduction, but the payment and other statutory conditions must be satisfied.
A HUF may claim a deduction for qualifying health insurance premiums paid for its members, subject to the applicable limits and conditions.
An NRI may be eligible to claim a deduction under the earlier Section 80D framework when filing an Indian tax return under a regime that permits it, provided the applicable statutory conditions are satisfied.
For example, an NRI who earns taxable rental income in India and pays a qualifying health insurance premium for themselves or their parents should check whether they can claim the deduction under the old tax regime. Their NRI status alone does not establish eligibility or disqualify them.
For this purpose, a senior citizen means an individual who is resident in India and aged 60 or more, so a senior NRI cannot claim the higher limit for themselves, though the higher limit may apply for resident parents who are 60 or more.
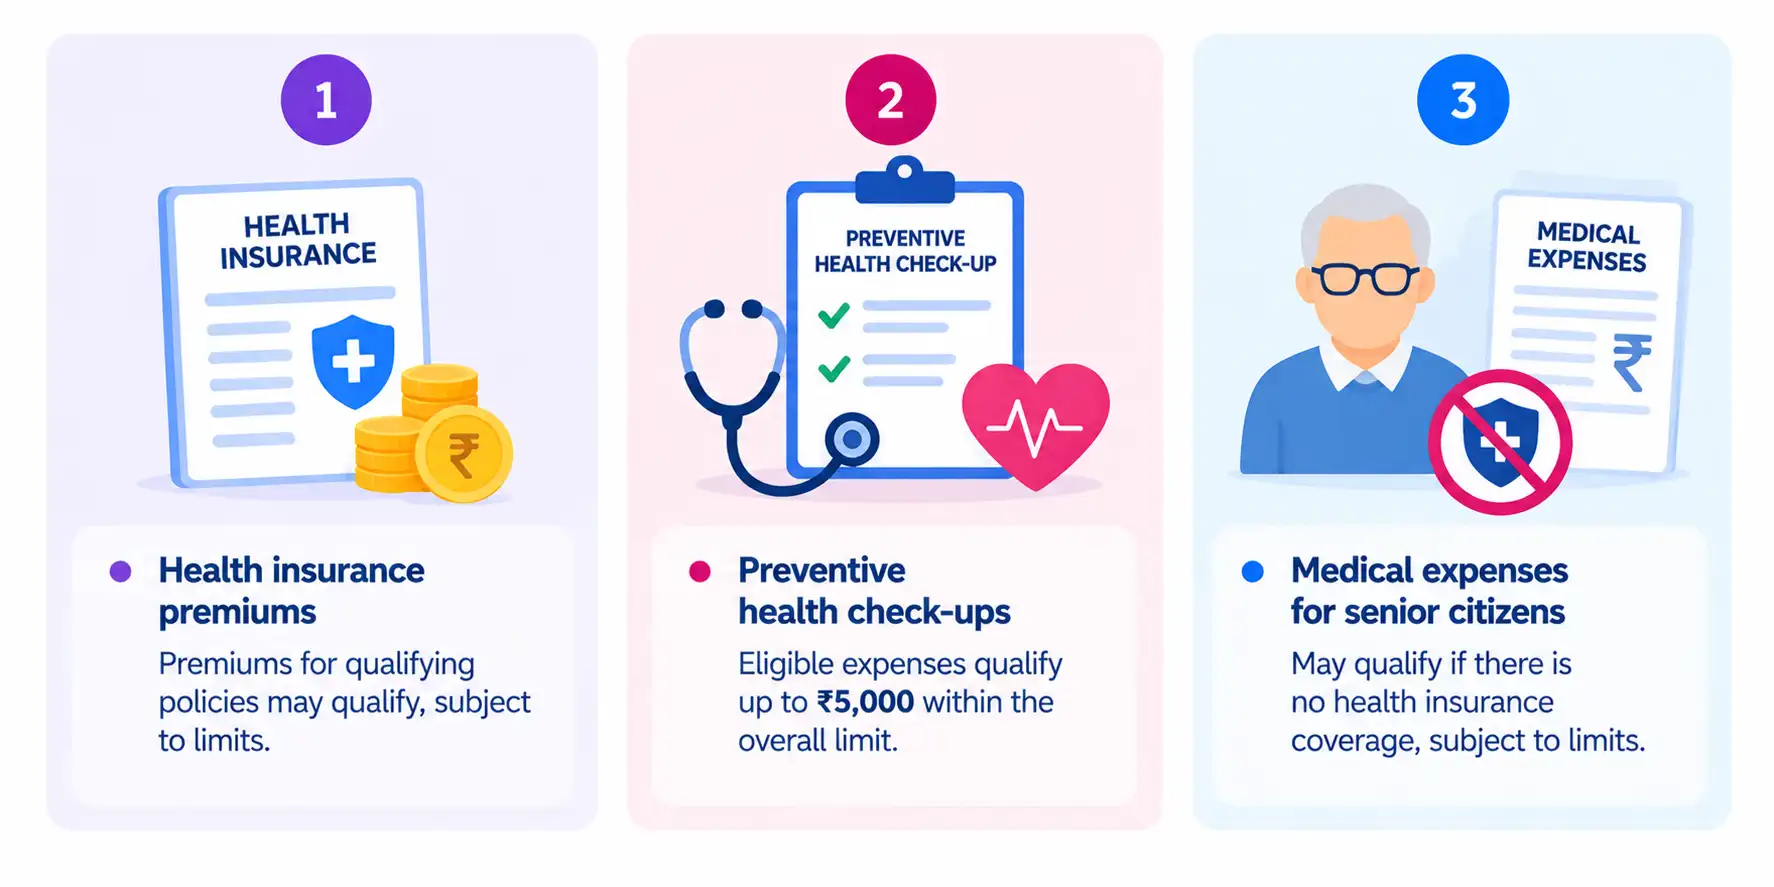
Premiums paid for qualifying health insurance policies may qualify, subject to the statutory requirements and applicable deduction limits.
Eligible preventive health check-up expenses qualify up to ₹5,000 in aggregate within the relevant overall limit. Payment for a preventive health check-up may be made in cash; other qualifying payments generally must be made through a non-cash mode under the earlier Section 80D rules.
Where a senior citizen has no health insurance coverage, certain medical expenses may qualify for deduction, subject to the applicable statutory conditions and limits. Medical expenses cannot automatically be claimed merely because the person is elderly; the no-insurance condition and other requirements must be met.
Under the Income-tax Act, 1961, Section 80D is generally not available to individuals and HUFs who are taxed under the default new tax regime under Section 115BAC. Eligible taxpayers who choose the old tax regime may claim Section 80D if they satisfy its conditions.
For Tax Year 2026–27 onward, the Income-tax Act, 2025 applies. Section 126 contains the corresponding deduction provision for health insurance premiums and certain medical expenses. However, taxpayers must also consider the new Act's tax-regime provisions before claiming the deduction.
Do not assume that a deduction listed in the Act is available under every tax regime. Verify the applicable rules for the relevant tax year before including the amount in your return.
Keep relevant records to substantiate your claim, including:
The Income Tax Department may require information about the insurer, policy number, and premium amount when the deduction is claimed.
Get expert guidance on eligible deductions and NRI tax filing.
Section 80D can help eligible taxpayers reduce taxable income through qualifying health insurance premiums, preventive health check-ups, and certain senior-citizen medical expenses. The amount depends on the relevant limits, the insured persons' ages, the payment type, and the applicable tax regime.
For NRIs, it is particularly important to check the Indian tax year, taxable income, and eligibility before claiming a deduction.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio
Want to read more? Explore Blogs