US Tax Filing and Compliance
J-1 Visa Tax Filing for Indian Researchers: Form 8843 and Treaty
Written by SaveTaxs Editorial Team
If you are a U.S. citizen or qualifying U.S. resident alien living outside the United States, you may still have to report your worldwide income to the IRS. If you also pay income tax in your country of residence, the same income may be subject to tax in two countries.
To reduce this potential double-tax burden, the U.S. tax system provides two important tax-relief provisions: the Foreign Earned Income Exclusion (FEIE) and the Foreign Tax Credit (FTC).
Although both can reduce your U.S. federal income tax, they work differently. FEIE allows eligible taxpayers to exclude qualifying foreign earned income from U.S. taxable income, while FTC provides a credit for qualifying foreign income taxes, subject to limitations.
For NRIs and other U.S. taxpayers living in India, choosing between FEIE and FTC requires more than comparing Indian and U.S. tax rates. Your income type, U.S. tax status, foreign tax payments, eligibility and long-term tax plans all matter.
Important for NRIs: Being classified as a Non-Resident Indian under Indian tax law does not automatically make you eligible for FEIE or FTC. Your U.S. citizenship or tax-residency status and the applicable U.S. tax rules determine your eligibility.
The main difference between FEIE and FTC is how each provision reduces your U.S. federal income tax.
The Foreign Earned Income Exclusion allows eligible U.S. citizens and qualifying resident aliens living abroad to exclude a certain amount of qualifying foreign earned income from U.S. gross income.
For tax year 2026, the maximum FEIE is $132,900 per qualifying taxpayer. You may qualify for the exclusion if you:
The exclusion is generally claimed using IRS Form 2555, attached to your applicable U.S. individual income tax return.
FEIE generally covers compensation for personal services performed in a foreign country, such as:
Important: FEIE may reduce federal income tax on qualifying self-employment income, but it does not reduce net earnings used to calculate U.S. self-employment tax. Separate Social Security and Medicare tax obligations may still apply, subject to applicable exceptions.
It generally does not cover interest, dividends, capital gains, pensions or other passive income.
For detailed eligibility conditions and calculations, see the Foreign Earned Income Exclusion Guide.
Understand your U.S. tax position and evaluate the tax-relief options available for your foreign income.
The Foreign Tax Credit allows eligible U.S. taxpayers to claim a credit for qualifying income taxes paid or accrued to a foreign government.
Unlike FEIE, the FTC does not exclude income from U.S. gross income. Instead, it can reduce your U.S. federal income tax liability.
For individuals, IRS Form 1116 is generally used to calculate the allowable credit. Certain taxpayers may qualify for an exception that allows them to claim a limited credit without filing Form 1116.
The FTC is subject to limitations. In general, the allowable credit cannot exceed the smaller of:
The calculation also depends on the applicable foreign-income category.
For more details, read the Foreign Tax Credit Guide
| Comparison | Foreign Earned Income Exclusion (FEIE) | Foreign Tax Credit (FTC) |
|---|---|---|
| How it works | Excludes qualifying foreign earned income from U.S. gross income | Reduces U.S. tax through a credit for qualifying foreign income taxes |
| Main eligibility | Foreign tax home and Physical Presence Test, or Bona Fide Residence Test where eligible; additional nationality conditions apply to resident aliens | Qualifying foreign-source income and creditable foreign income taxes |
| Income covered | Qualifying foreign earned income | Income associated with qualifying foreign taxes, subject to source and category rules |
| 2026 limit | Up to $132,900 per qualifying taxpayer, subject to eligibility and applicable adjustments | No equivalent fixed annual exclusion cap; subject to FTC limitations |
| Main IRS form | Form 2555 | Form 1116, in most cases |
| Passive income | Generally not eligible | May qualify, depending on source and tax-credit rules |
| Unused benefit | Unused FEIE cannot be carried forward | Eligible unused FTC may generally be carried back one year and forward ten years |
| Tax on excluded income | Foreign taxes attributable to excluded income cannot also be claimed as FTC or deduction | Cannot be claimed on taxes attributable to income excluded under FEIE |
| Election consequences | Revoking the FEIE election can restrict re-election for five tax years without IRS approval | No equivalent general five-year FTC re-election rule |
| Tax calculation | Excludes qualifying earned income, but the tax on remaining taxable income is generally calculated using the Foreign Earned Income Tax Worksheet | Reduces U.S. income tax through the allowable credit |
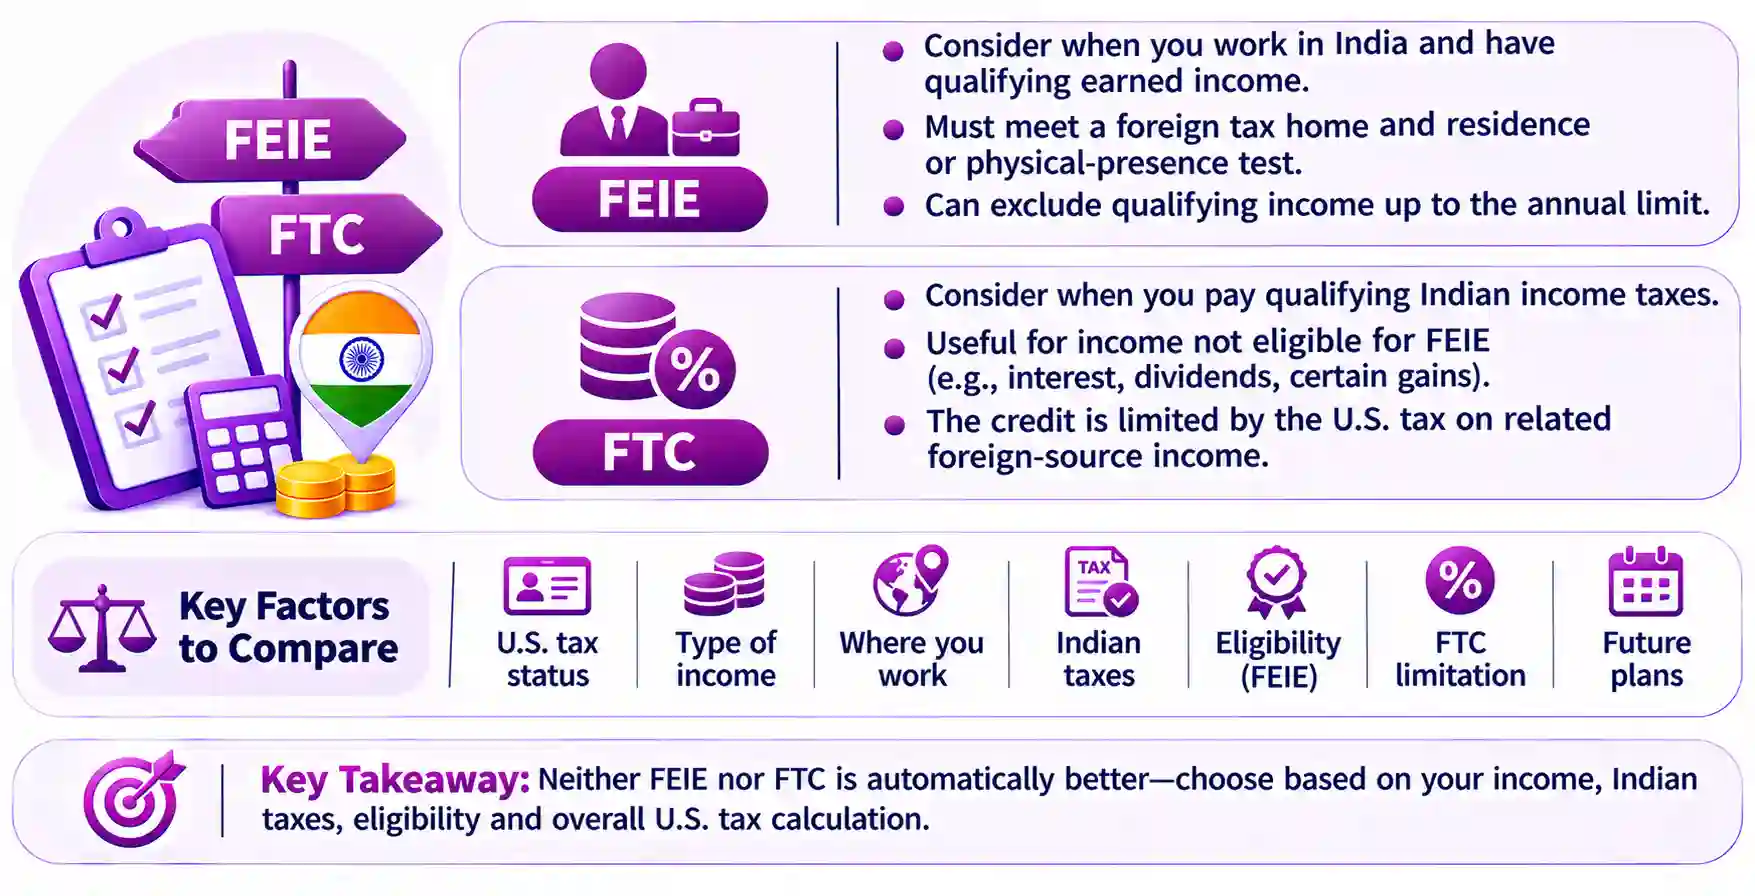
For Americans living and working in India, neither FEIE nor FTC is automatically better. The appropriate option depends on the type of income, qualifying Indian income taxes, U.S. tax liability and the taxpayer's eligibility.
A U.S. citizen working in India may have Indian salary income, bank interest, dividends, rental income and capital gains. Each type of income must be evaluated separately under U.S. tax rules.
FEIE may be worth considering when you:
For example, consider an American citizen who moves to India for a full-time employment assignment. The individual performs services in India, establishes a qualifying foreign tax home and meets the applicable residence or physical-presence requirements.
The individual's salary for services performed in India may qualify as foreign earned income. If the eligibility requirements are met, FEIE may help exclude some or all of that qualifying income, subject to the annual limit and other applicable rules.
However, FEIE does not automatically eliminate U.S. tax on other income, such as interest, dividends, capital gains or income from U.S. sources.
FTC may be worth considering when you:
For example, an American living in India may receive interest from an Indian bank and dividends from an Indian company. These income items are generally not foreign earned income for FEIE purposes.
However, qualifying Indian income taxes associated with foreign-source income may potentially be considered for FTC, subject to the applicable sourcing, creditability and limitation rules.
The amount of Indian tax paid is not automatically the amount of FTC available.
Before deciding between FEIE and FTC, consider these factors:
| Factor | Why it matters |
|---|---|
| U.S. tax status | Determines your U.S. filing and worldwide-income obligations |
| Type of income | FEIE generally applies to qualifying earned income, while FTC can apply to qualifying taxes on different income categories |
| Location where services are performed | Helps determine whether compensation may qualify as foreign earned income |
| Indian income taxes | Only qualifying foreign income taxes may be considered for FTC |
| FEIE eligibility | You must meet the applicable foreign tax home and residence or physical-presence requirements |
| FTC limitation | The credit is limited by the U.S. tax attributable to relevant foreign-source income |
| Future plans | Moving countries, returning to the United States or changing income sources may affect the tax strategy |
Important: Do not choose FEIE simply because Indian tax rates appear lower or FTC simply because Indian tax rates appear higher. The actual U.S. tax calculation and eligibility rules determine which approach may be more beneficial.
For a detailed explanation of how Indian salary, interest, dividends and other income are reported in the United States, read How U.S. Citizens in India Report Indian Income to the IRS.
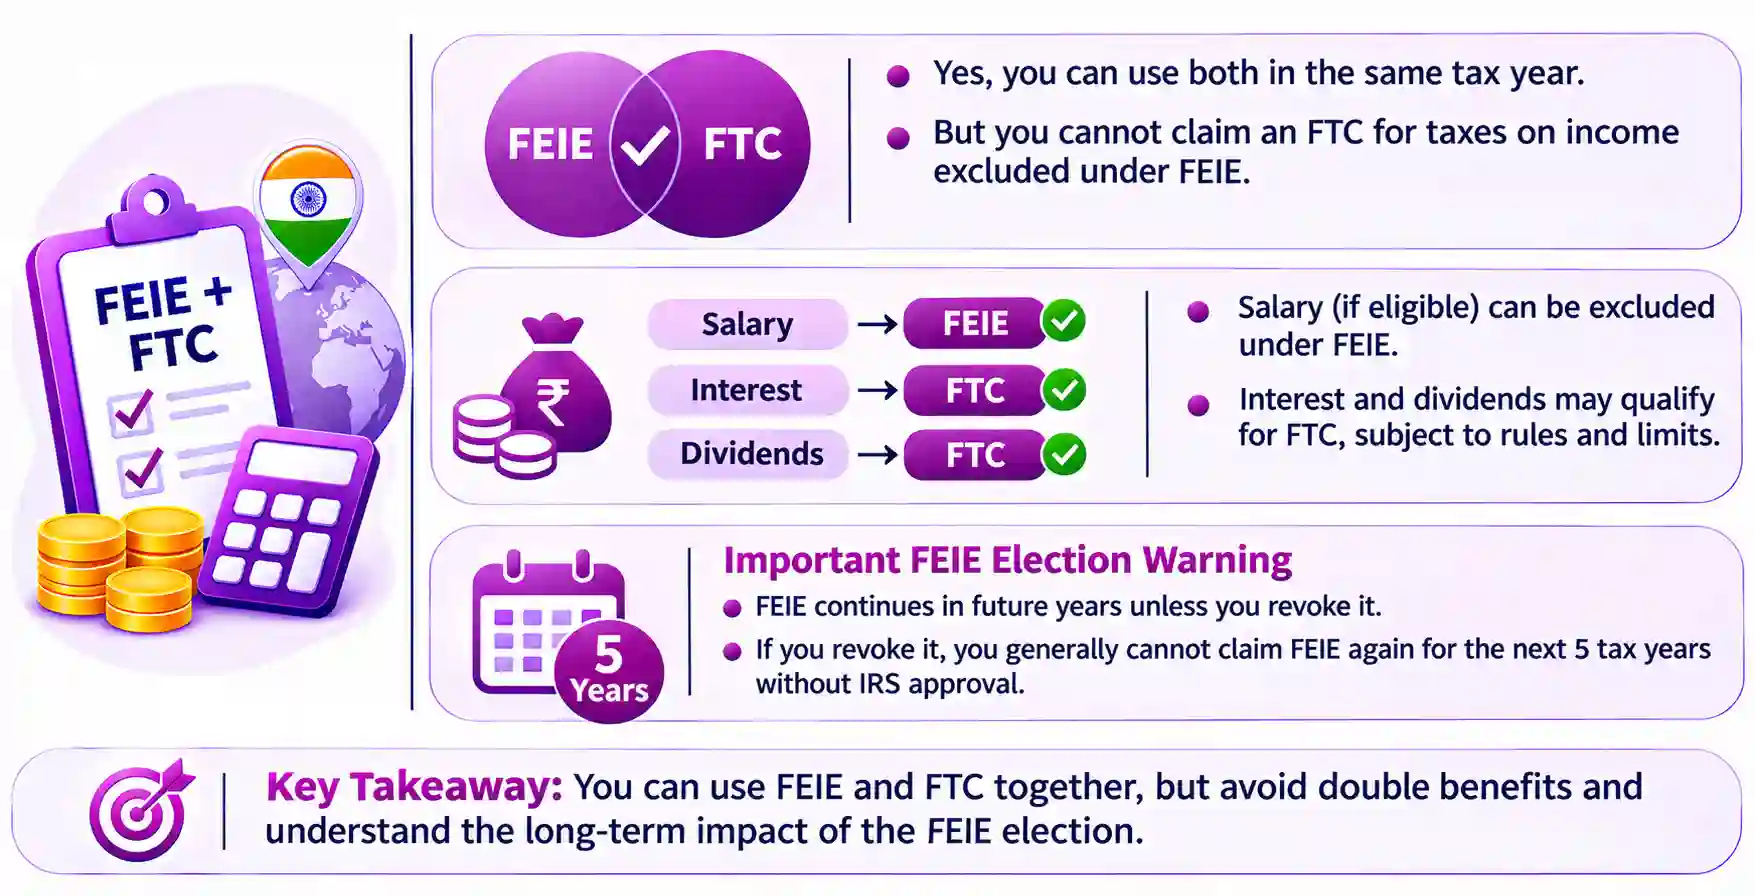
Yes, FEIE and FTC may both be relevant in the same tax year, but you cannot claim an FTC for foreign income taxes attributable to income excluded under FEIE.
The important distinction is that the two provisions cannot provide duplicate tax relief on the same excluded income.
For example, an American living in India may have:
If the salary qualifies for FEIE, the taxpayer may be able to exclude the eligible amount under the applicable rules.
The interest and dividend income must be evaluated separately. If they are foreign-source income and qualifying Indian income taxes apply, FTC may potentially be available, subject to the relevant category and limitation rules.
The foreign taxes attributable to the excluded salary cannot also be claimed as an FTC or deduction.
The FEIE election has a long-term consequence that taxpayers should understand before changing their tax strategy.
Once you elect FEIE, the election generally continues for subsequent years unless you revoke it.
If you revoke the election, you generally cannot claim FEIE again for the next five tax years without IRS approval.
Claiming a foreign tax credit or deduction for foreign taxes attributable to income that could have been excluded under an existing FEIE election may result in revocation of that election under the applicable IRS rules.
Therefore, do not revoke an existing FEIE election or switch strategies without reviewing the effect on future tax years.
For detailed Form 1116 calculations and filing requirements, see IRS Form 1116 for NRIs.
Connect with SaveTaxs experts for assistance with cross-border tax planning, FEIE, FTC and U.S. tax filing.
Choosing between the Foreign Earned Income Exclusion and Foreign Tax Credit requires an understanding of your U.S. tax status, income sources, Indian tax payments and long-term financial plans.
FEIE may help eligible Americans living in India exclude qualifying foreign earned income, while FTC may reduce U.S. tax through credits for qualifying foreign income taxes that remain available for credit. In some situations, both provisions may be relevant, but the same excluded income cannot receive duplicate tax relief.
For NRIs, U.S. citizens and qualifying Green Card holders living in India, the right approach requires reviewing both countries' tax rules and the interaction between the available U.S. tax provisions.
SaveTaxs helps U.S. taxpayers and NRIs understand their cross-border tax obligations, evaluate FEIE and FTC eligibility, and plan their U.S. tax filings with India-related income in mind. Connect with our tax experts before choosing or changing your tax strategy.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Want to read more? Explore Blogs
Potentially, yes. An NRI who is a U.S. citizen or qualifying U.S. resident alien may claim FEIE on qualifying salary for services physically performed in India if the foreign tax home and applicable residence or physical-presence requirements are met.
Indian NRI status alone does not establish FEIE eligibility.