US Tax Filing and Compliance
S Corporation Late Election Relief: Form 2553 RulesS Corporation Late Election Relief: Form 2553 Rules
Written by Shubham Jain
Head of Household tax filing is a U.S. federal income tax filing status that can provide a higher standard deduction and more favorable tax brackets than filing as Single.
However, being the primary earner in your home does not automatically qualify you for this status. The IRS has specific rules concerning marital status, household expenses, and qualifying family members.
For example, a single parent who pays most household expenses and lives with an eligible child may qualify. A taxpayer supporting a dependent parent living elsewhere may also qualify under special conditions.
This guide explains the Head of Household requirements, tax benefits, and how to claim the filing status correctly.
Head of Household (HOH) is one of the five federal income tax filing statuses recognized by the IRS.
It is designed for eligible taxpayers who maintain a home for a qualifying person, such as a child or dependent parent.
Compared with Single or Married Filing Separately, HOH generally offers a higher standard deduction and more favorable income tax brackets.
However, taxpayers must meet all applicable requirements before selecting this status.
The IRS generally requires three conditions:
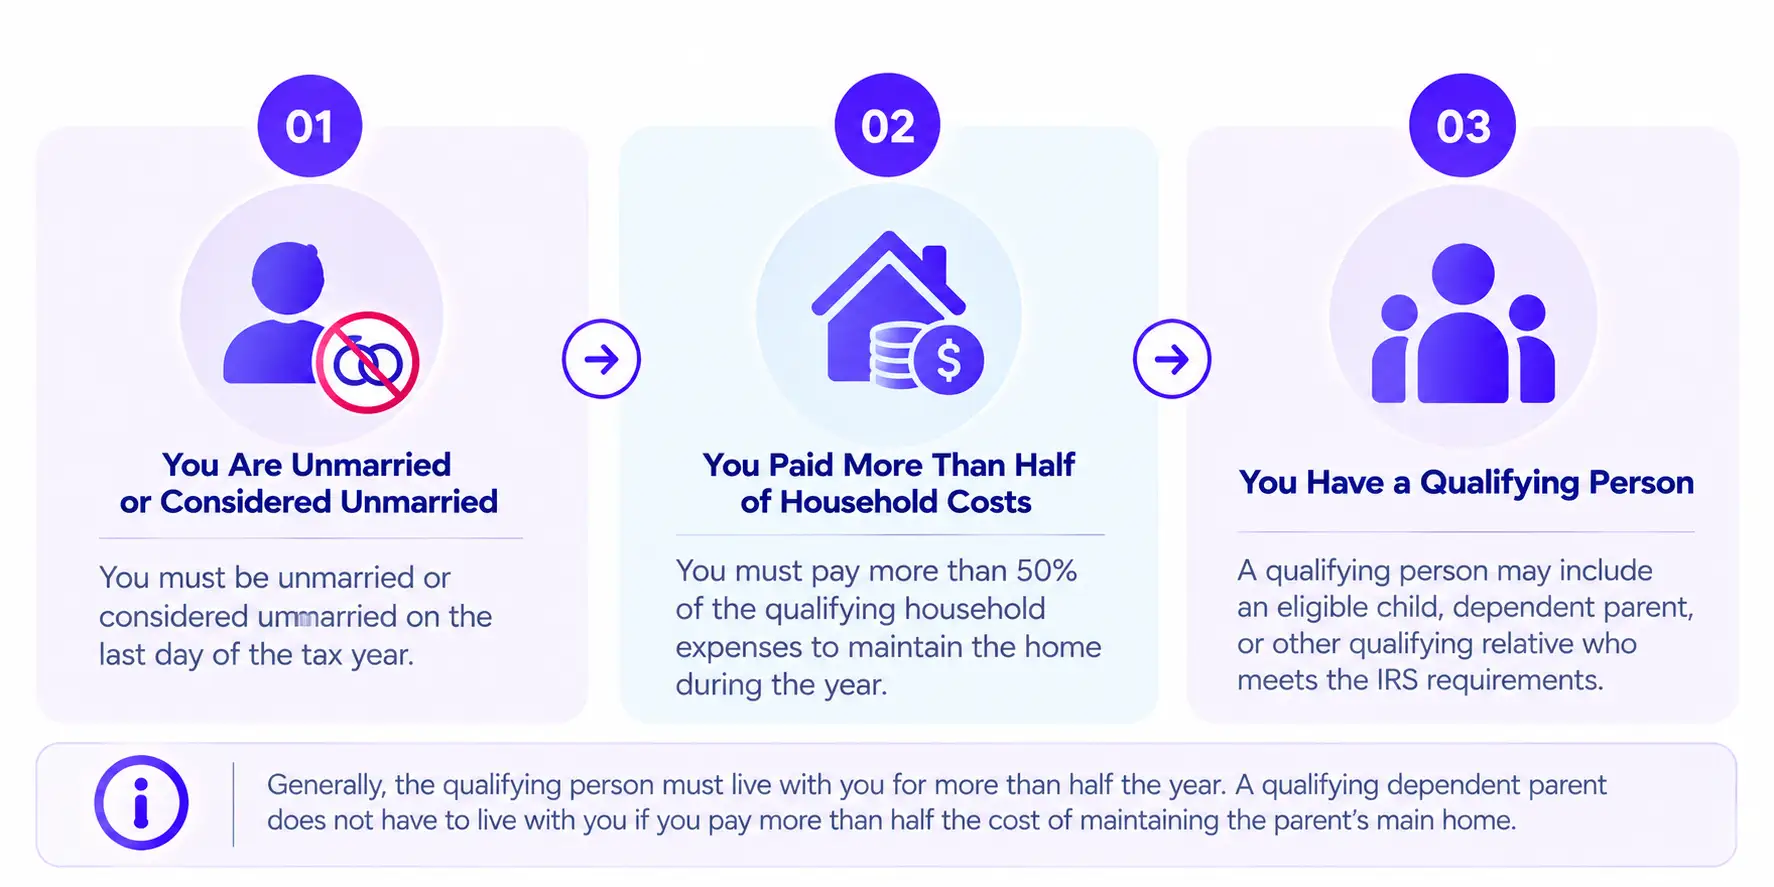
You must be unmarried or considered unmarried on the last day of the tax year.
A married taxpayer may qualify as considered unmarried if specific requirements are met, including living apart from their spouse during the final six months of the year and maintaining a home for an eligible child.
Simply filing a separate tax return does not automatically establish HOH eligibility.
You must pay more than 50% of the qualifying expenses required to maintain the home during the year.
Example: If the total qualifying household expenses are $24,000 and you pay $15,000, you satisfy the household-cost requirement.
However, you must also meet the marital-status and qualifying-person tests.
A qualifying person may include an eligible:
Generally, the qualifying person must live with you for more than half the year.
Exception: A qualifying dependent parent does not have to live with you if you pay more than half the cost of maintaining the parent's main home and satisfy the other requirements.
Not every person who qualifies as a dependent automatically qualifies someone for HOH status.
Check your eligibility and claim applicable tax benefits with expert filing support.
The IRS distinguishes qualifying household expenses from personal expenses.
| Expenses That Count | Expenses That Do Not Count |
|---|---|
| Rent | Clothing |
| Mortgage interest | Education |
| Property taxes | Medical expenses |
| Home insurance | Transportation |
| Utilities | Vacations |
| Repairs and maintenance | Life insurance |
| Food consumed at home | Mortgage principal payments |
Example: Suppose your qualifying household expenses total $30,000. You contribute $18,000, while other household members contribute $12,000.
You have paid 60% of the qualifying costs and therefore satisfy this particular HOH requirement.
Keep rent receipts, mortgage statements, utility bills, and other relevant documents to support your calculation.
One major advantage of HOH status is its higher standard deduction.
| Filing Status | Tax Year 2025 | Tax Year 2026 |
|---|---|---|
| Head of Household | $23,625 | $24,150 |
| Single | $15,750 | $16,100 |
| Married Filing Separately | $15,750 | $16,100 |
For tax year 2025, an eligible HOH filer receives a standard deduction that is $7,875 higher than the basic Single standard deduction.
This can reduce taxable income, although the actual tax savings depend on the taxpayer's circumstances.
HOH also generally provides wider lower-income tax brackets than Single filing.
Important: Taxpayers cannot choose HOH simply because it produces a lower tax bill. They must satisfy the eligibility requirements.
In certain circumstances, yes.
A custodial parent may qualify for HOH even when the other parent claims the child as a dependent under the special rules for divorced or separated parents.
For example, a child lives with their mother for most of the year. The mother pays more than half the cost of maintaining the home but allows the noncustodial father to claim the child as a dependent under the applicable IRS rules.
The mother may still qualify for HOH if all filing-status requirements are met.
However, supporting a boyfriend, girlfriend, or unrelated roommate does not by itself establish HOH eligibility, even when that person qualifies as a dependent under other rules.
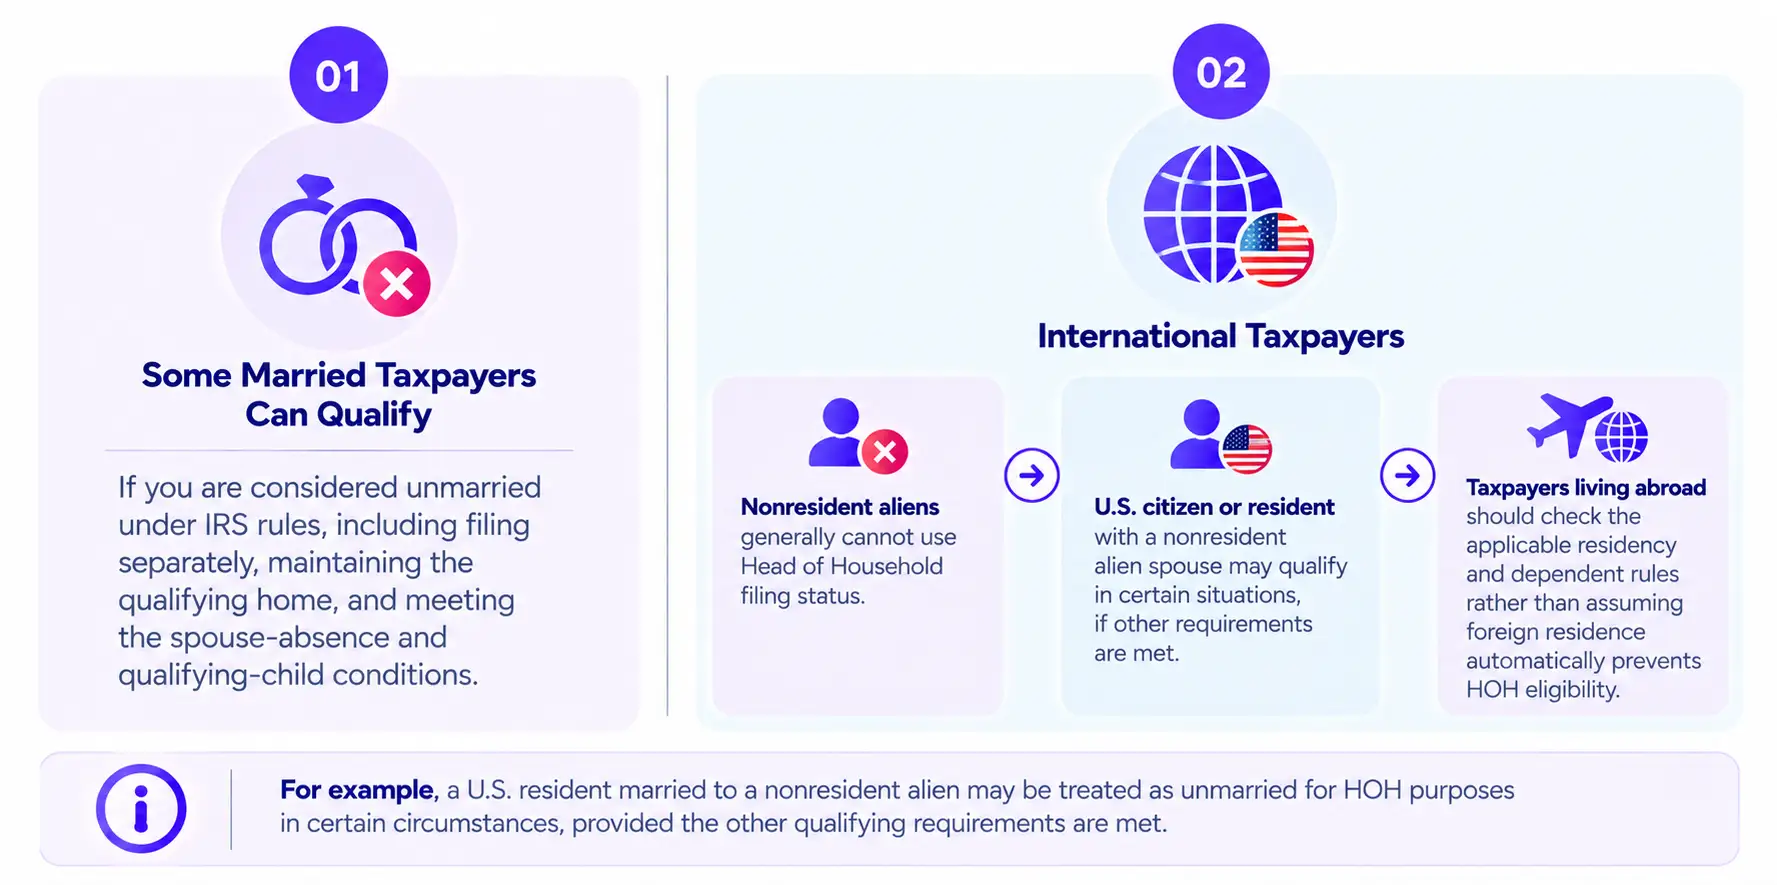
Some married taxpayers can qualify if they are considered unmarried under IRS rules.
Generally, this requires filing separately, maintaining the qualifying home, and meeting the spouse-absence and qualifying-child conditions.
International taxpayers must also consider U.S. tax residency.
Nonresident aliens generally cannot use Head of Household filing status. However, special situations involving a nonresident alien spouse may allow an eligible U.S. citizen or resident taxpayer to qualify.
For example, a U.S. resident married to a nonresident alien may be treated as unmarried for HOH purposes in certain circumstances, provided the other qualifying requirements are met.
Taxpayers living abroad should also check the applicable residency and dependent rules rather than assuming foreign residence automatically prevents HOH eligibility.
Eligible taxpayers can claim HOH status when preparing their federal income tax return.
If a qualifying child is not claimed as a dependent because of the applicable special rules, follow the Form 1040 instructions for identifying that child.
Our tax experts can help you understand IRS eligibility rules and choose the correct filing status.
Head of Household tax filing can provide meaningful federal tax advantages, but eligibility depends on more than paying most household bills.
Before selecting this status, verify your marital status, qualifying household expenses, and the person who makes you eligible.
If your family or residency circumstances are complicated, review the IRS requirements carefully or seek professional tax guidance before filing.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio
Want to read more? Explore Blogs