US Tax Filing and Compliance
S Corporation Late Election Relief: Form 2553 RulesS Corporation Late Election Relief: Form 2553 Rules
Written by Shubham Jain

If you are self-employed in the United States, you may be able to deduct eligible business expenses from your business income, reducing the amount of income subject to tax. Common examples include home office costs, business travel, advertising, insurance, professional fees, and certain retirement contributions.
However, not every expense is tax-deductible, and some deductions have specific eligibility requirements, percentage limits, or reporting rules.
This guide explains 20 tax deductions that self-employed people, freelancers, independent contractors, and sole proprietors should review when preparing their federal tax returns for the 2025 tax year. The rules and limits can differ for other tax years and business structures.
Self-employed individuals generally report eligible business income and expenses on Schedule C (Form 1040), unless a different form or reporting method applies to their business.
You may qualify if you operate as a:
An LLC or corporation may follow different tax rules depending on its classification. In addition, an expense must generally be ordinary and necessary for the business, appropriately documented, and not a personal expense.
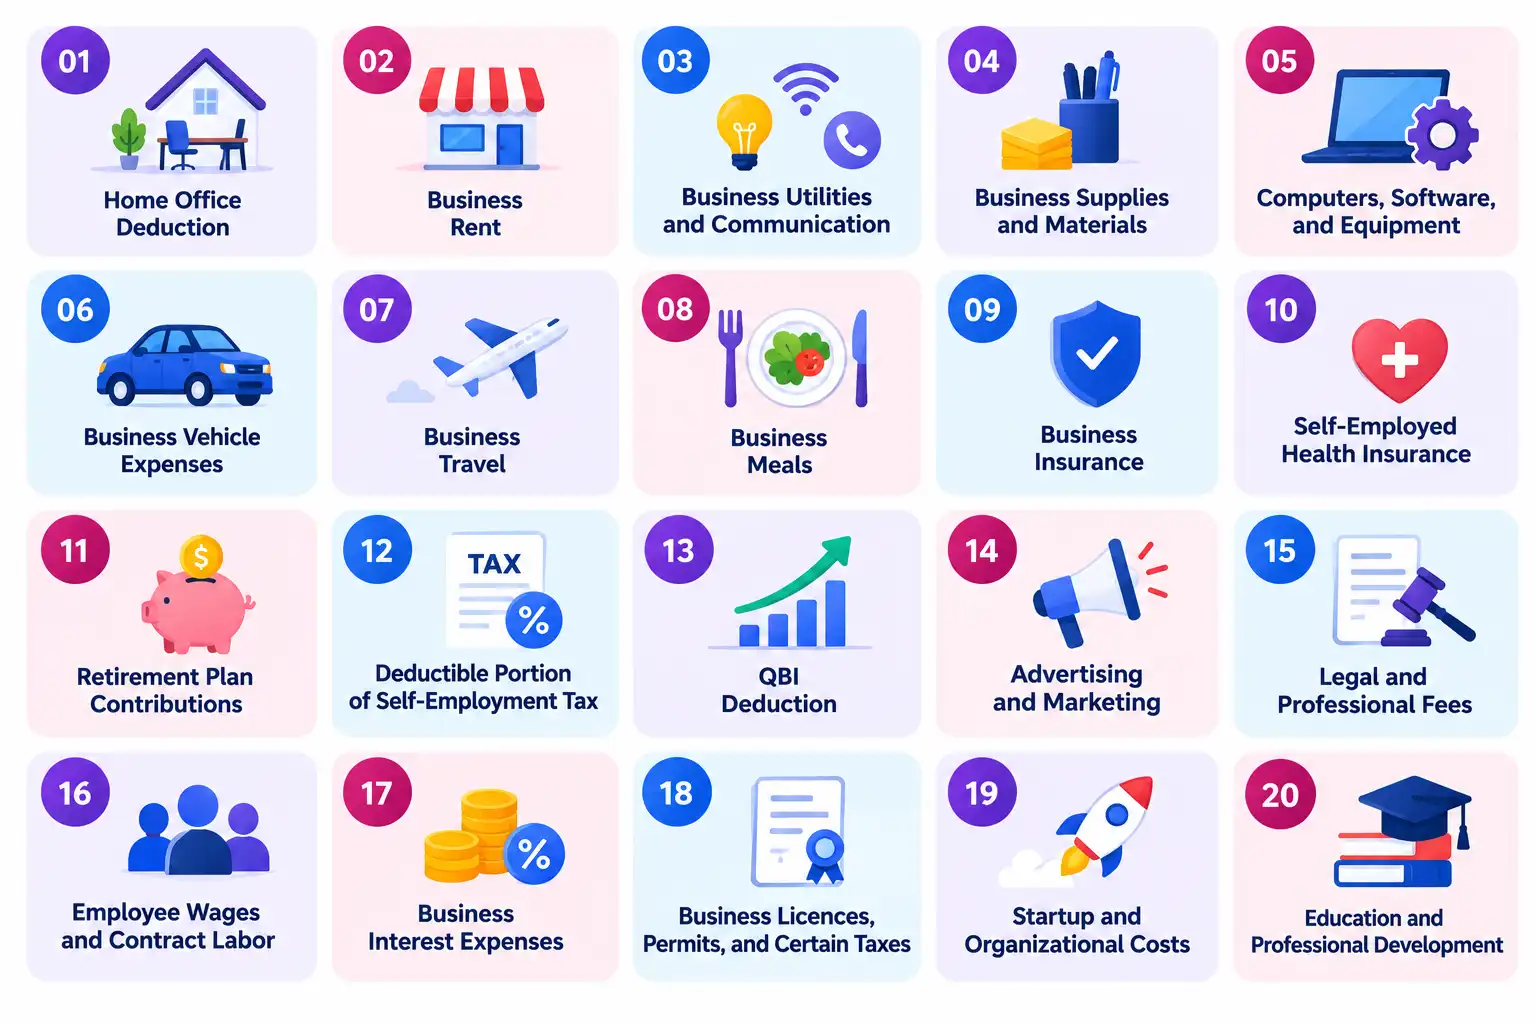
If you use part of your home regularly and exclusively for qualifying business purposes, you may be able to claim a home office deduction.
You can generally choose between:
For example, a freelancer with 150 square feet of qualifying office space could potentially claim $750 using the simplified method. Eligibility rules apply, and employees generally cannot claim this deduction for employee work.
With SaveTaxs, understand your self-employed tax deductions and manage your U.S. tax obligations with confidence, accuracy, and ease.
If you rent an office, studio, workshop, or other property for your business, the qualifying rent may be deductible.
The rented space should be used for business, and the expense must meet the applicable requirements. Personal rent is not deductible simply because you sometimes work from home.
If you pay rent in advance, the deduction generally follows the period to which the payment applies.
Utilities and communication services may be deductible to the extent they are used for business.
Examples include:
If a service is used for both business and personal purposes, deduct only the eligible business portion. The basic cost of the first telephone line in a personal residence generally cannot be deducted as a business expense.
Office supplies and materials used in your business may qualify as deductions.
Examples include paper, pens, envelopes, printer ink, packaging materials, and small consumable supplies.
Inventory and materials used to produce goods may instead be included in the cost of goods sold. Equipment that has a useful life extending beyond one year may need to be capitalized, depreciated, or treated under an applicable expensing election rather than deducted as an ordinary supply.
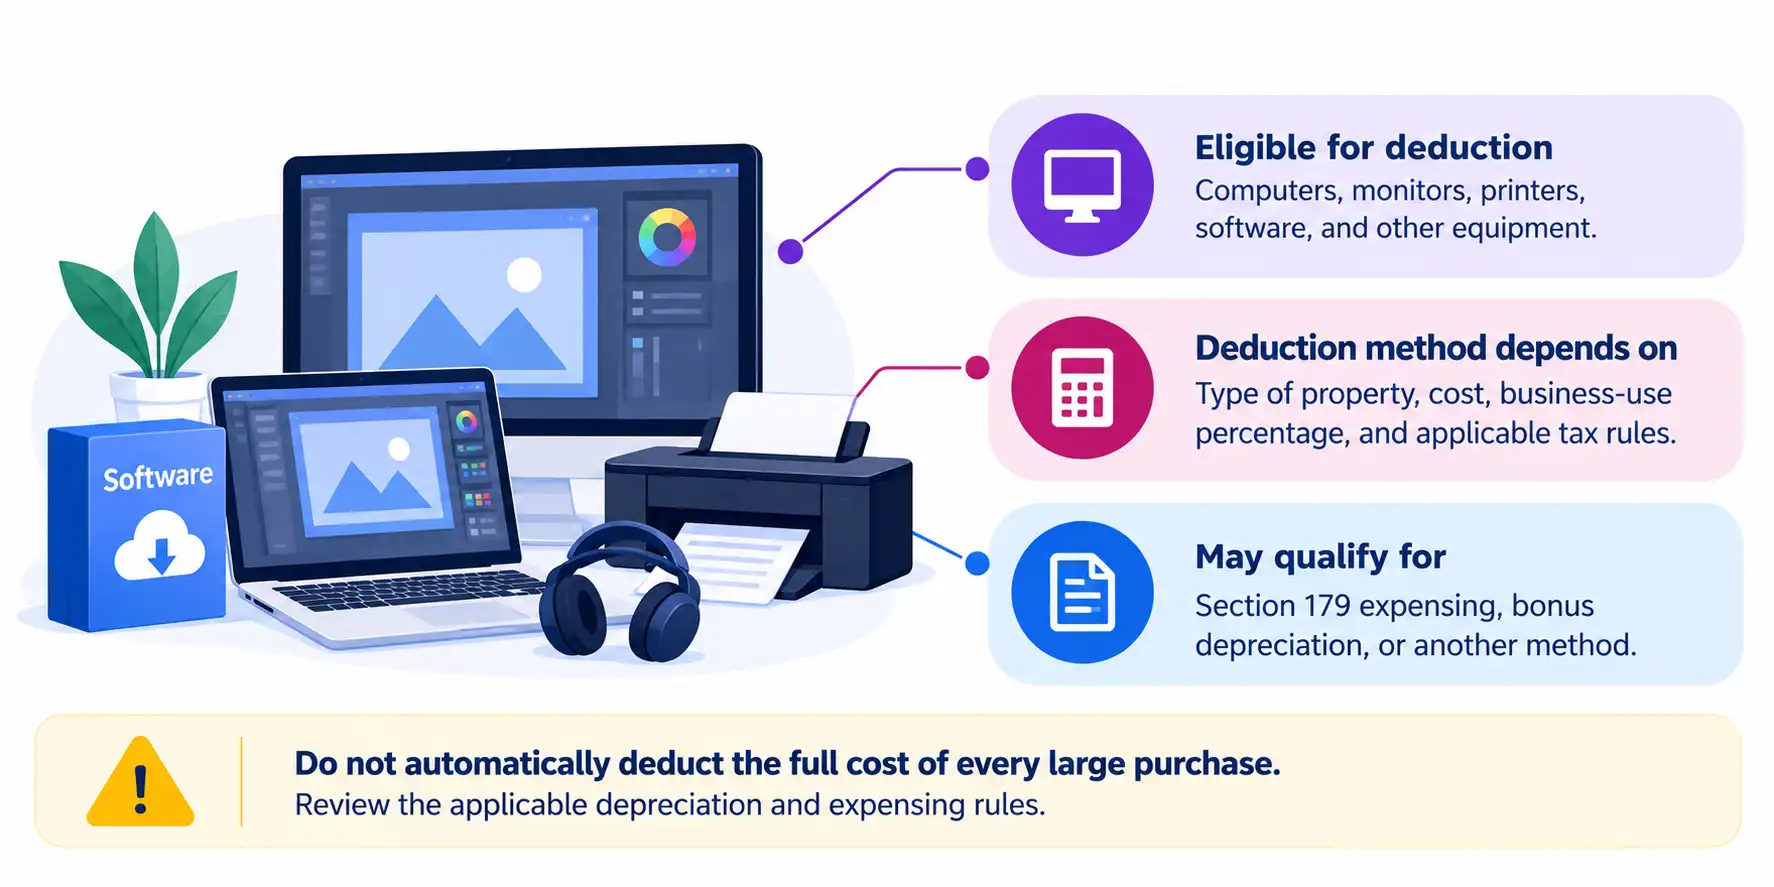
Eligible computers, monitors, printers, software, and other equipment used in your business may qualify for a deduction.
The treatment depends on the type of property, its cost, business-use percentage, and applicable tax rules. Certain assets may qualify for Section 179 expensing, bonus depreciation, or another permitted method.
For example, a freelance designer may be able to deduct eligible design software subscriptions and claim an allowable deduction for a computer used for client projects.
Do not automatically deduct the full cost of every large purchase. Review the applicable depreciation and expensing rules.
If you use a car, van, or truck for business, you may be able to deduct eligible vehicle expenses.
Depending on the applicable rules, you may choose between the standard mileage method and the actual expense method.
For the 2025 tax year, the standard business mileage rate is 70 cents per qualifying business mile. Qualifying parking fees and tolls may be deductible separately.
Under the actual expense method, eligible costs may include fuel, repairs, insurance, registration, and depreciation, allocated to business use. Commuting between home and a regular workplace is generally personal travel, not deductible business mileage.
Keep mileage records showing the date, destination, business purpose, and distance travelled.
Qualifying travel expenses incurred while travelling away from your tax home for business may be deductible.
Potentially eligible costs include:
The trip must meet the relevant business-travel requirements. Personal holidays and expenses for accompanying family members are generally not deductible unless specific rules apply.
Certain business meals may be deductible when they satisfy IRS requirements.
For most eligible business meal expenses, the deduction is generally limited to 50% of the qualifying cost. The meal should have a valid business purpose, should not be lavish or extravagant under the circumstances, and must meet the applicable attendance and documentation requirements.
Entertainment expenses are generally not deductible as business expenses, even when business discussions occur during the event. Keep itemized receipts and record the business purpose and attendees.
Premiums for qualifying business insurance may be deductible.
Examples include:
The policy must relate to the business, and special rules can apply to particular types of insurance. Personal life insurance premiums generally cannot be deducted as a business expense when the taxpayer is directly or indirectly the beneficiary.
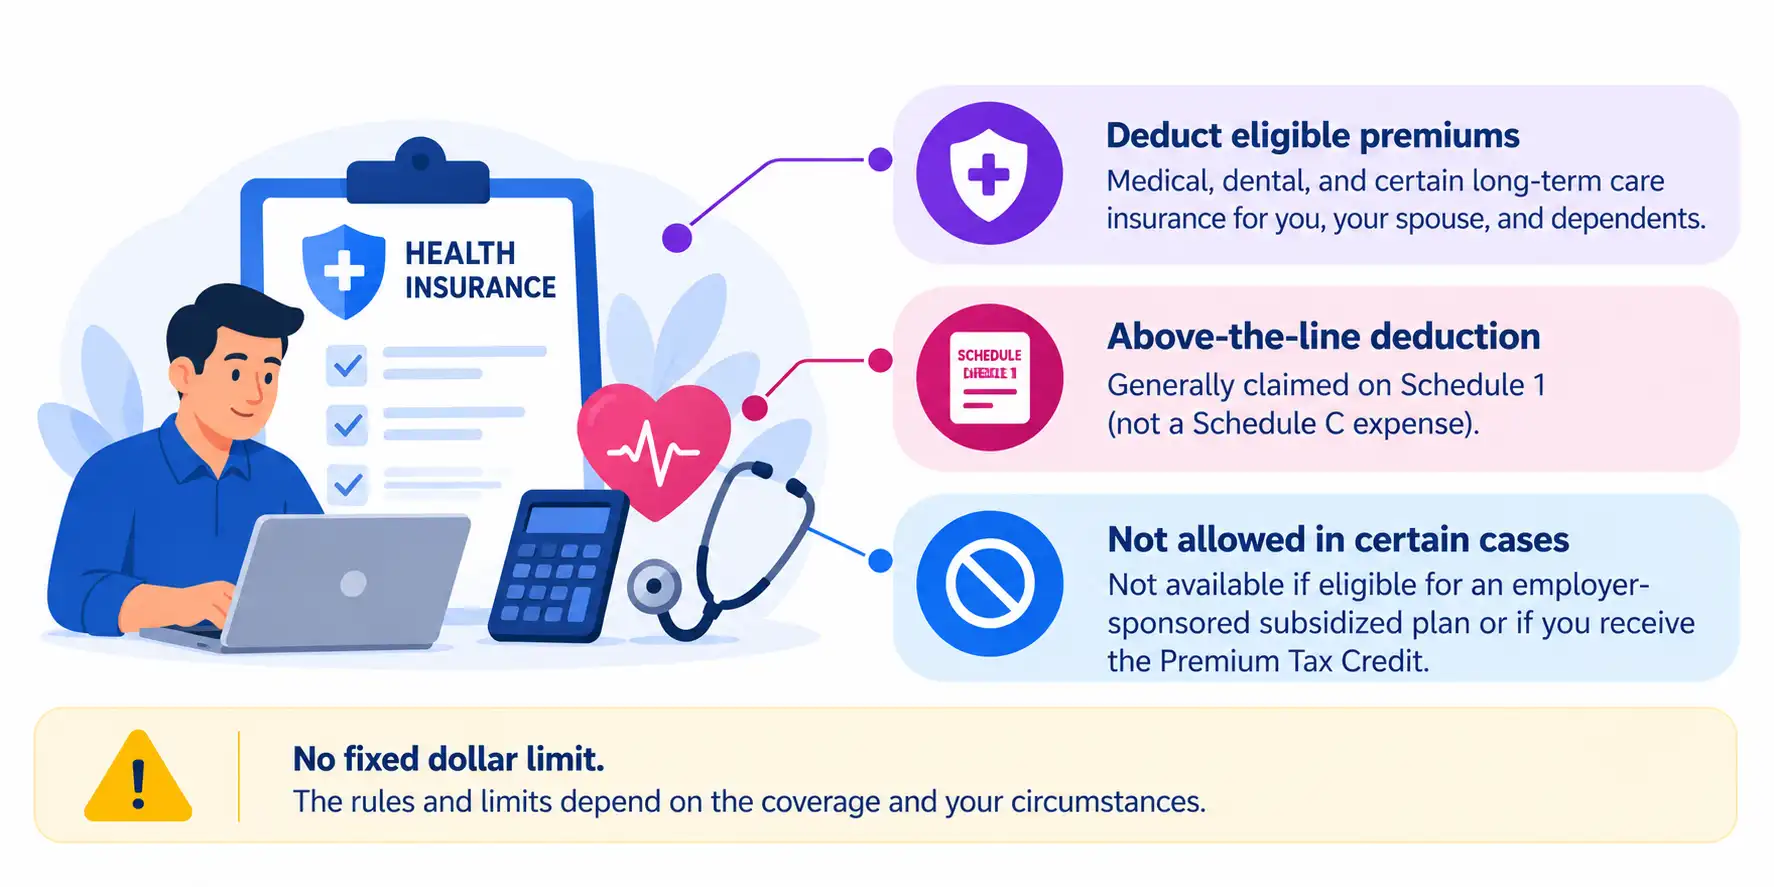
Eligible self-employed individuals may be able to deduct qualifying medical, dental, and certain long-term care insurance premiums for themselves, their spouse, and eligible dependents.
This is generally an above-the-line deduction claimed on Schedule 1, rather than an ordinary Schedule C expense. The deduction is subject to eligibility and earned-income limitations.
You generally cannot claim the deduction for months when you were eligible to participate in a subsidized health plan maintained by your employer or your spouse's employer. Additional restrictions can apply if you receive the Premium Tax Credit.
Do not use a generic age-based dollar cap. The rules and limits depend on the coverage and applicable circumstances.
Self-employed people may qualify for deductions for contributions to eligible retirement plans, such as:
Contribution limits, deadlines, and deduction calculations depend on the plan, income, and business structure. Contributions made for the owner's retirement are generally claimed differently from contributions made for employees.
Review the applicable plan rules before calculating the deduction.
Self-employed individuals generally pay Social Security and Medicare taxes on qualifying net earnings from self-employment.
Eligible taxpayers can generally deduct one-half of their self-employment tax as an adjustment to income. This deduction does not reduce the self-employment tax itself; it reduces adjusted gross income for federal income tax purposes.
Use Schedule SE and the applicable Form 1040 instructions to calculate the amount. Special rules may apply to nonresident aliens and individuals covered by an international Social Security agreement.
Eligible business owners may qualify for the deduction for qualified business income under Section 199A.
The deduction can generally be up to 20% of qualified business income, subject to taxable-income limitations and other requirements. Wage, property, and specified service trade or business rules can affect the calculation.
The QBI deduction is separate from ordinary business expenses. It is generally claimed on the individual tax return rather than as a Schedule C business expense.
For the 2025 tax year, check the applicable IRS instructions and income thresholds before estimating the deduction.
Ordinary and necessary advertising expenses may be deductible when incurred to promote your business.
Examples include:
Keep invoices and records showing the business purpose. Costs to acquire certain long-term assets or create certain intangible assets may require different treatment.
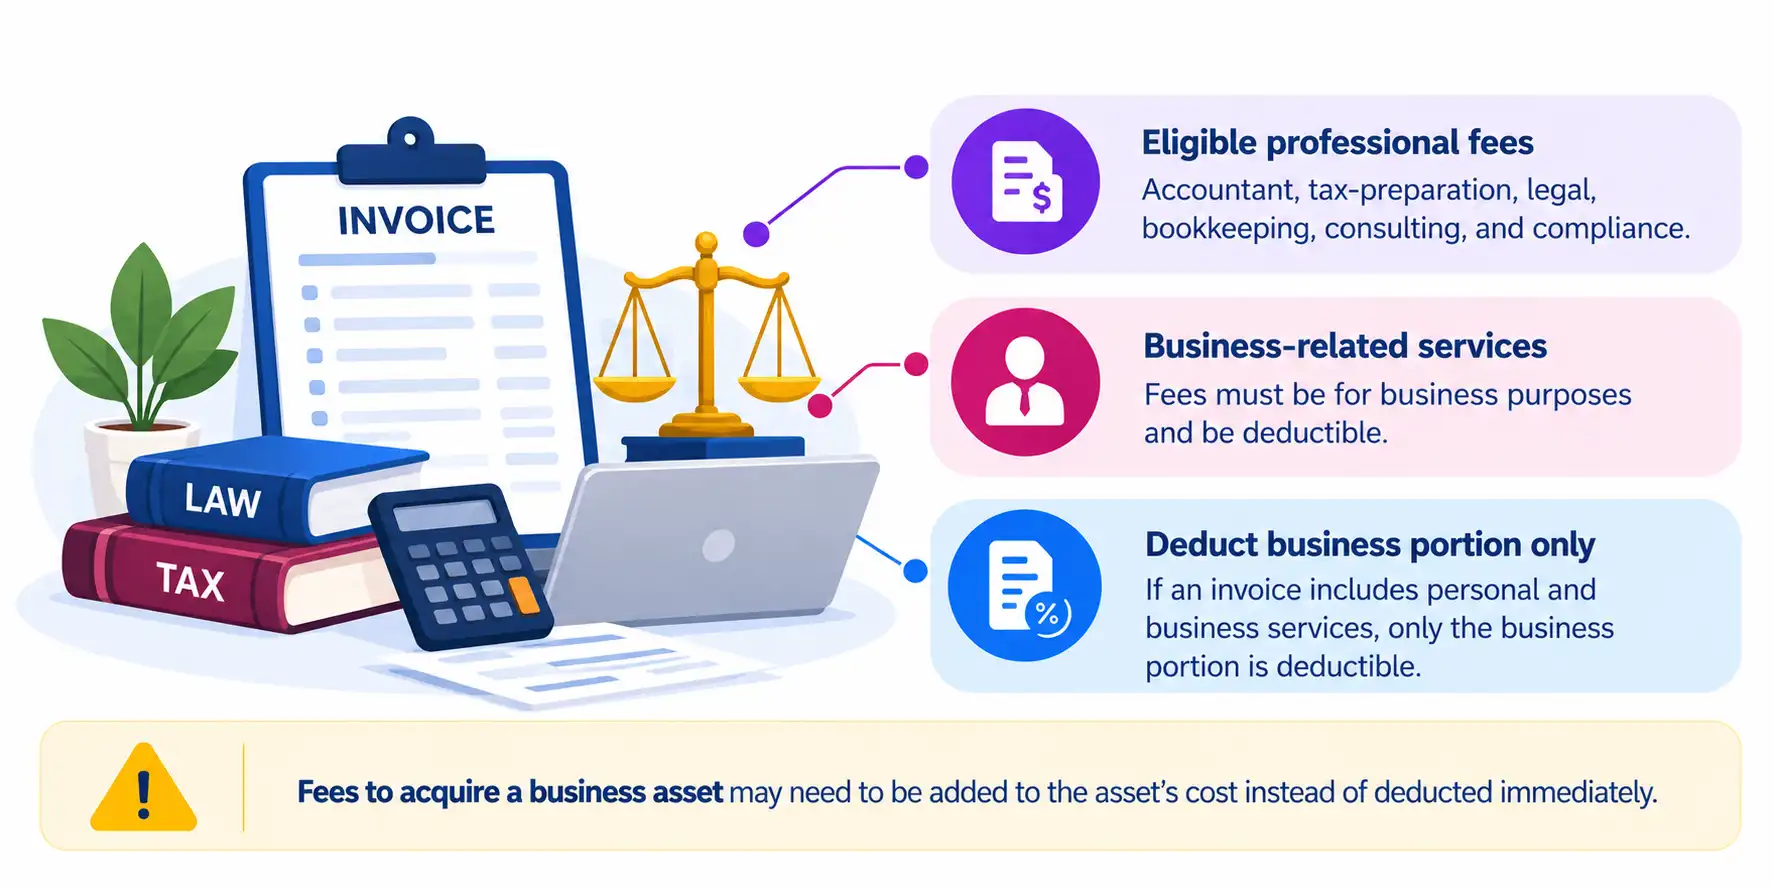
Fees paid for eligible business-related professional services may be deductible.
These can include:
If a professional invoice includes both personal and business services, only the eligible business portion should be deducted. Fees paid to acquire a business asset may need to be added to the asset's cost instead of deducted immediately.
If your business hires employees, eligible wages, salaries, bonuses, and certain employee benefits may be deductible.
Payments to independent contractors may also qualify as business expenses when the services are ordinary and necessary for the business.
You generally cannot deduct your own sole proprietor's draw as employee wages. Worker classification and applicable payroll reporting requirements must also be followed.
Interest paid on qualifying business debt may be deductible.
For example, a self-employed consultant who borrows money to purchase business equipment may be able to deduct the eligible interest associated with the business borrowing.
The taxpayer must generally be legally liable for the debt, and the borrowing must have a genuine debtor-creditor relationship. Personal loan interest is not a business deduction merely because the borrower is self-employed. Business interest limitations may also apply.
Certain state, local, and other taxes directly related to operating your business may be deductible.
Examples include eligible business licence fees, regulatory fees, business property taxes, and certain employment taxes paid by the employer.
Federal income tax is not deductible as a Schedule C business expense. Taxes connected to acquiring property may need to be included in the property's cost, and certain licence or registration costs may need to be capitalized or amortized.
Check the rules applicable to your state, business, and type of tax.
Costs incurred before a business begins operating may qualify as startup costs. Certain costs associated with creating a corporation or partnership may qualify as organizational costs.
For qualifying startup costs, the general federal rule allows an immediate deduction of up to $5,000, reduced by the amount by which total startup costs exceed $50,000. Remaining eligible costs are generally amortized over 180 months beginning with the month the active business starts.
Organizational costs have separate requirements. Not every cost incurred before opening a business qualifies, and equipment purchases or other capital costs may be treated differently.
Training and education expenses may be deductible when they maintain or improve skills required in your current trade or business, or satisfy another applicable business-expense rule.
Examples may include eligible professional courses, industry conferences, reference materials, and certain training costs.
Education that qualifies you for a new trade or business, or that meets minimum educational requirements for your existing work, generally does not qualify under the ordinary business education rules. Personal education expenses are not deductible merely because the knowledge may be useful.
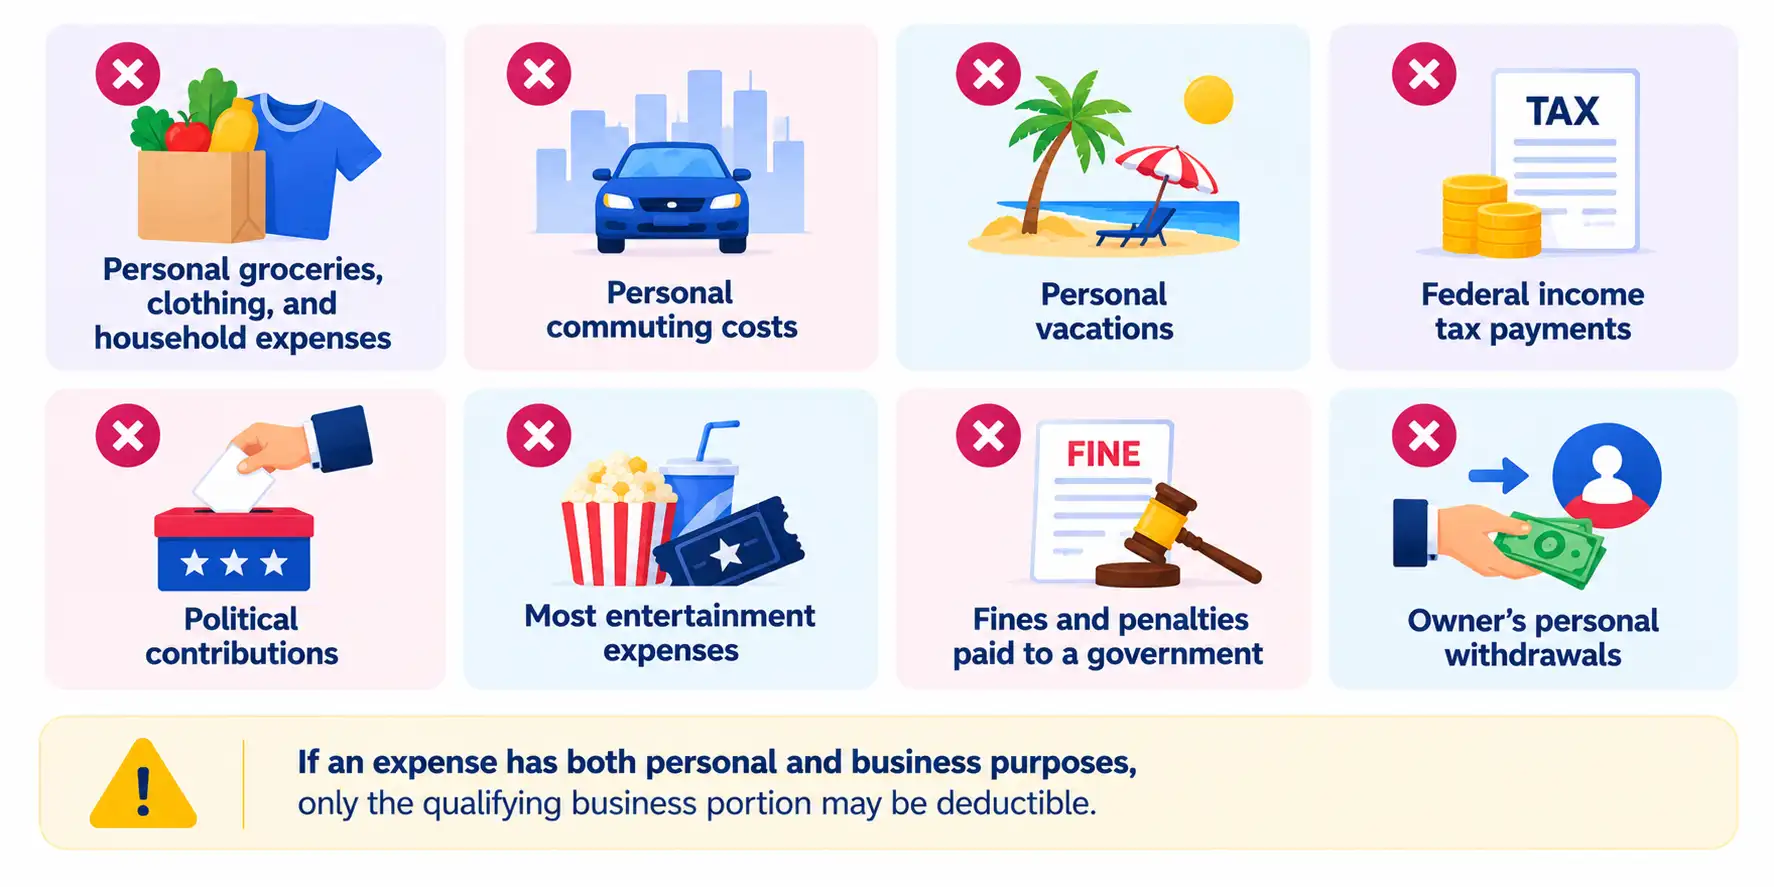
Not every expense paid by a business owner qualifies for a tax deduction. Common examples of expenses that are generally not deductible as business expenses include:
Some expenses have mixed personal and business purposes. In those cases, only the qualifying business portion may be deductible, if the relevant requirements are met.
At SaveTaxs, we help self-employed individuals, freelancers, and business owners understand eligible tax deductions and navigate U.S. tax filing requirements based on their circumstances.
Follow these steps to prepare your tax return:
Tax deductions can reduce taxable income, but they do not usually reduce tax dollar for dollar. Your actual tax savings depend on your tax situation and applicable rules.
SaveTaxs helps U.S. taxpayers understand business deductions, federal filing requirements, and tax compliance. If you are self-employed, a freelancer, or a small business owner, professional guidance can help you determine which deductions apply to your circumstances and how to report them correctly.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio
Want to read more? Explore Blogs