NRI Income Tax Compliance
NRI received money from parents?NRI received money from parents?
Written by Hatim Dudhiyawala

You've probably already filed your income tax return and may have received an email or PDF mentioning Section 143(1). The confusing part is often understanding the processed figures, opening the password-protected intimation, and knowing whether you need to take any action. In this guide, we'll explain the 143(1) intimation, password, download process, tax calculation, demand or refund, and the appropriate response or rectification options.
Section 143(1) intimation communicates the result of processing your income-tax return and may show a refund, tax payable, or other processed outcome.
The 143(1) intimation PDF contains important information about the return processed, tax computation, adjustments, and resulting refund or demand.
The 143(1) intimation password is required when the PDF received by email is password protected; use the password format specified with the communication or current portal instructions.
A difference between your ITR and 143(1) result can arise from differences in income, deductions, tax credits, or adjustments permitted during processing.
A 143(1)(a) communication concerns proposed prima facie adjustments and gives the taxpayer an opportunity to respond before processing is completed.
Section 154 rectification can be used for an eligible mistake apparent from the record in an intimation issued under Section 143(1).
A 143(1) intimation should not be ignored; compare it with your filed ITR and tax records before deciding whether any action is required.
A Section 143(1) intimation is a communication showing the result of processing an income-tax return under Section 143(1). The processing can involve computing total income or loss, determining tax and interest where applicable, adjusting eligible tax credits, and determining whether tax is payable or a refund is due.
First, the Income-tax Act, 1961 provides for processing a return under Section 143(1) and sending an intimation specifying the resulting amount payable or refund due. The provision also covers cases where a declared loss is adjusted even when no tax or refund results.
For example, suppose you filed an ITR claiming a refund of ₹50,000. After processing, the intimation shows a refund of ₹42,000 because the processed figures or eligible tax credits differ from your return. The intimation communicates that processed result.
Moreover, a 143(1) intimation is not the same as a scrutiny notice under Section 143(2). Section 143(2) concerns scrutiny proceedings where the Assessing Officer requires further examination of the return.
A Section 143(1) intimation matters because it tells you what happened when the Income Tax Department processed your return. It allows you to compare the department's processed figures with the information you reported in your ITR.
First, check whether the intimation shows:
A refund due
A tax demand or amount payable
No additional amount payable or refundable
An adjustment that changed the figures reported in your return
For example, if your ITR showed ₹80,000 as a refund but the intimation shows ₹65,000, the ₹15,000 difference needs to be understood before you assume that the department made an error.
In addition, the intimation can help identify the specific figures that caused a difference between your return and the processed result. You should compare those figures with your ITR, tax-credit records, and supporting documents.
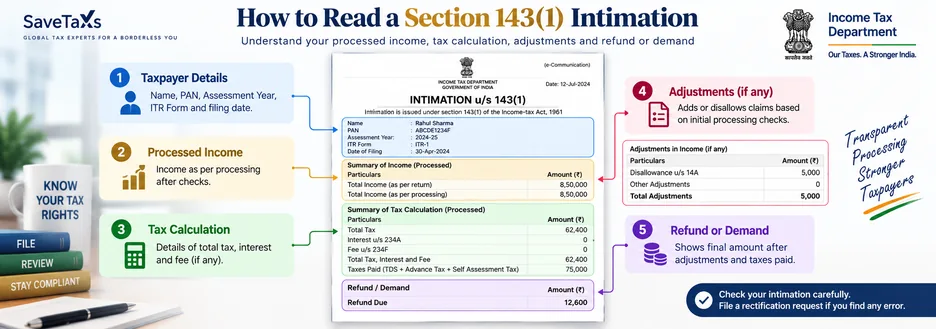
A Section 143(1) intimation generally contains the taxpayer's return-processing details, income and tax computation, applicable adjustments, and the resulting refund or amount payable. The exact presentation can vary depending on the return and processing outcome.
First, review the document for:
Taxpayer details — Check your name, PAN, assessment year, and other identifying information.
Return details — Verify the return and processing information.
Income figures — Compare the processed income with your filed ITR.
Deductions and other claims — Check whether relevant claims were accepted or changed.
Tax computation — Compare the processed tax liability with your original computation.
Tax credits — Review TDS, TCS, advance tax, self-assessment tax, and other applicable credits.
Refund or demand — Identify the final amount determined after processing.
For example, a taxpayer who claimed TDS of ₹1,20,000 should compare that credit with the amount recognized in the processed intimation. A missing or different credit can materially change the resulting refund or demand.
The 143(1) intimation PDF may be password protected, so you should use the password format specified in the communication or by the current Income Tax Department instructions. Because portal and communication procedures can change, verify the current format if the commonly circulated password combination does not work.
First, do not assume that every tax PDF uses the same password convention. The safest approach is to check the email or communication accompanying the intimation and use the current instructions provided by the Income Tax Department.
For example, if the communication specifies a particular combination of taxpayer information, enter it exactly as instructed, including the required capitalization, date format, or other characters.
At the same time, avoid repeatedly guessing passwords from third-party websites. The Income Tax Department's e-Filing portal is the appropriate source for current procedural instructions.
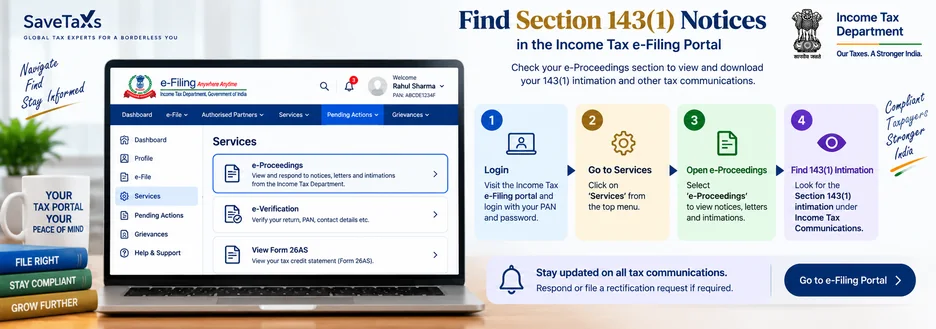
You can access your tax communications through the Income Tax Department's e-Filing services and download the relevant intimation or communication from the portal. The exact navigation can change as the portal interface is updated.
First, log in to the official e-Filing portal using your credentials. Then check the relevant sections for your return processing, pending actions, notices, or communications.
For communications that require a response, the Income Tax Department's current e-Proceedings guidance directs taxpayers to Dashboard → Pending Actions → e-Proceedings, where applicable notices and communications can be viewed.
For example, a taxpayer who receives a 143(1)(a) proposed adjustment can use e-Proceedings to view and download the notice before submitting a response.
You should read a 143(1) intimation by comparing the filed ITR with the processed income, deductions, tax credits, tax liability, and final refund or demand. Reading the final amount alone is not enough because the underlying figures explain why the result changed.
First, create a simple comparison:
| Particular | Filed ITR | 143(1) Processed | Difference |
|---|---|---|---|
| Total income | ₹10,00,000 | ₹10,20,000 | ₹20,000 |
| Taxable income | ₹8,00,000 | ₹8,20,000 | ₹20,000 |
| Tax liability | ₹70,000 | ₹76,000 | ₹6,000 |
| Tax credits | ₹1,00,000 | ₹1,00,000 | Nil |
| Refund | ₹30,000 | ₹24,000 | ₹6,000 |
For example, this taxpayer's refund is ₹6,000 lower because the processed tax liability is ₹6,000 higher. The next step is to identify which income, deduction, or adjustment produced the difference.
Moreover, the correct response depends on the reason for the difference. A genuine demand may need to be paid, while an eligible processing error may be addressed through the appropriate correction or rectification mechanism.
Your 143(1) tax calculation can differ from your ITR when the figures accepted during processing differ from the figures reported in the return or when permitted adjustments affect the computation. Section 143(1) specifically provides for certain processing adjustments, including an arithmetical error or an incorrect claim apparent from information in the return.
First, check the areas most likely to explain a difference:
Income reported in the return
Deductions and exemptions
TDS or TCS credits
Advance tax
Self-assessment tax
Other tax payments
Tax computation
Permitted processing adjustments
For example, if your ITR contains an arithmetic error that changes taxable income, the processed computation can differ from the original return.
In addition, a difference does not automatically mean that the department has made a mistake. Reconcile each changed figure before deciding whether to request correction.
A 143(1) tax demand means that the processed return results in an amount payable after the applicable computation and tax-credit adjustments. The demand should be reconciled with your ITR and tax records before you decide how to proceed.
First, identify the reason for the demand in the intimation. Check whether it relates to income, deductions, tax credits, tax payments, interest, or another processing adjustment.
For example, the Income Tax Department has issued communications explaining that a demand can arise where tax-payment challan details were not claimed in the return; in such cases, an eligible taxpayer may use rectification to claim the relevant tax credit.
At the same time, do not treat every demand as an error. If the demand is correct, the appropriate course may be to pay it or follow the applicable demand-response process.
A lower 143(1) refund means that the processed result recognizes a lower refund than the amount claimed in your ITR. The difference should be traced to the processed income, deductions, tax computation, or tax credits.
First, compare the refund computation line by line. Then check whether the difference comes from a changed income figure, disallowed claim, missing tax credit, interest computation, or another permitted adjustment.
For example, if your ITR claimed ₹75,000 but the intimation determines ₹60,000, identify the exact ₹15,000 difference before filing any correction request.
Moreover, a lower refund should be investigated rather than automatically challenged. If the processed figures are correct, no rectification is necessary merely because the refund is lower than expected.
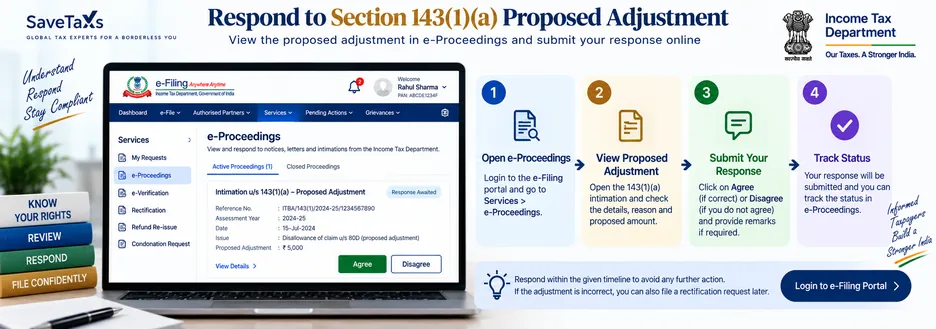
A Section 143(1)(a) communication is a notice of proposed prima facie adjustments made during processing, giving the taxpayer an opportunity to respond before the return is processed. The Income Tax Department states that taxpayers can agree or disagree with the proposed adjustments through the e-Filing portal.
First, this stage is different from the final 143(1) intimation. A proposed adjustment gives you an opportunity to review the discrepancy and submit your response.
For example, if CPC identifies a variance during processing, you can open the relevant adjustment, review the details, and select whether you agree or disagree with the proposed adjustment.
If you receive a 143(1)(a) notice, do not wait for the final intimation before responding. The Income Tax Department's current guidance states that the response should be filed within the period specified for the communication, with its user manual stating 30 days from the date of issue for this notice.
If you disagree with a final 143(1) intimation, first identify whether the difference is an eligible mistake apparent from the record and then use the appropriate correction mechanism. The correct route depends on the nature of the discrepancy.
First, follow this practical sequence:
Download and save the 143(1) intimation.
Compare it with your filed ITR.
Identify the exact difference.
Check your AIS, Form 26AS, TDS certificates, challans, and supporting records where relevant.
Determine whether the processed result is correct.
Use the applicable response, reprocessing, or rectification mechanism.
For example, if a tax payment was actually made but was not properly reflected in the processed return, gather the challan and return records before seeking correction.
Moreover, do not use a revised return as the automatic solution to every 143(1) discrepancy. A revised return and a rectification request serve different purposes, and the appropriate route depends on the facts and applicable filing rules.
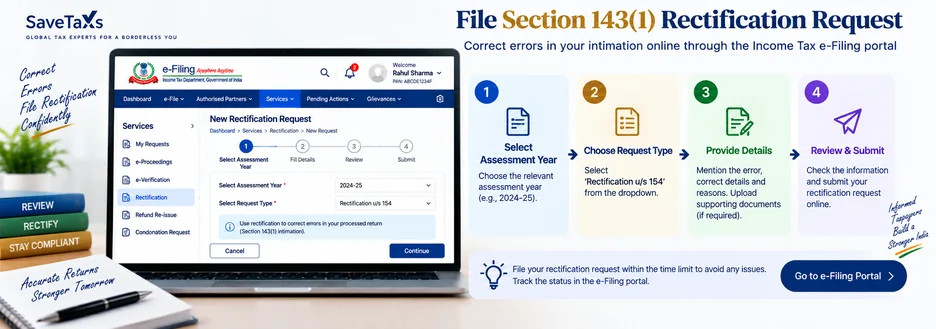
Section 154 rectification can be used where an eligible mistake apparent from the record exists in an intimation issued under Section 143(1). The Income Tax Department specifically states that taxpayers can submit a rectification request when such a mistake exists in a CPC intimation.
First, rectification is particularly relevant when the return has already been processed and the issue can be established from the existing record. The Department's guidance states that taxpayers whose returns were processed by CPC can file online rectification with CPC after logging into the e-Filing account.
For example, if an eligible tax credit was correctly paid but was not recognized during processing, the taxpayer can examine whether a rectification request is available and provide the relevant details.
You should check your refund or demand status through the official Income Tax e-Filing services after reviewing the 143(1) intimation. The intimation tells you the processed result, while the portal can provide relevant status and follow-up information.
First, keep your intimation, ITR acknowledgment, tax-payment records, and tax-credit information together. This makes it easier to reconcile any difference shown by the department.
For example, if the intimation shows a refund but the amount has not yet reached your bank account, checking the official refund status can help determine whether further action is required.
For returns governed by the Income-tax Act, 1961, Section 143(1) provides that an intimation should not be sent after one year from the end of the financial year in which the return is made. This statutory time limit is stated in the current text of Section 143(1).
First, the applicable legal framework matters because India's tax legislation has transitioned to the Income-tax Act, 2025 for later tax years. The article should therefore identify the relevant assessment/tax year before applying a statutory deadline.
For example, a taxpayer dealing with a return governed by the Income-tax Act, 1961 should not automatically apply a deadline from a different tax-year framework.
At the same time, always check the law applicable to the specific return and communication rather than relying on a generic deadline copied from an older article.
The official Income Tax e-Filing portal is the primary practical tool for viewing applicable communications, responding to eligible proceedings, and filing rectification requests. The Department's e-Proceedings service allows registered users to view and respond to specified notices and intimations, including prima facie adjustments under Section 143(1)(a).
First, use the portal to verify the communication instead of relying only on an email attachment. The Department's guidance provides the e-Proceedings path as Dashboard → Pending Actions → e-Proceedings for applicable notices.
For a proposed 143(1)(a) adjustment, the portal lets you review individual variances and provide an Agree or Disagree response before submission.
For rectification, the Income Tax Department states that taxpayers can access the rectification service through the e-Filing portal and submit an eligible request against a CPC intimation.
After receiving a 143(1) intimation, your next step is to open the document, compare the processed figures with your ITR, identify any difference, and take the appropriate action. A simple decision process prevents you from paying an incorrect demand or filing an unnecessary correction.
First, use this checklist:
No difference: Save the intimation with your tax records.
Refund is lower: Identify the adjustment or changed figure.
Demand appears: Verify the reason and reconcile tax credits and payments.
Eligible mistake exists: Check whether Section 154 rectification is available.
143(1)(a) proposal received: Review and respond through e-Proceedings within the applicable time.
Refund is due: Monitor the refund status through the official portal.
For example, if your ITR and 143(1) intimation match but a refund is pending, you generally need to monitor the refund rather than file a rectification request simply because payment has not yet arrived.
Moreover, keep the 143(1) intimation and supporting tax records for your files. These records can be useful if you later need to reconcile a demand, refund, tax credit, or rectification request.
A Section 143(1) intimation communicates the result of processing your income-tax return and tells you whether the processed result leads to a refund, demand, or another outcome. The most important step is to understand how the processed figures compare with the return you originally filed.
First, remember the practical sequence: open the intimation → compare the figures → identify the difference → verify your tax records → take the appropriate action.
If you receive a 143(1)(a) proposed adjustment, respond through the applicable e-Proceedings mechanism rather than waiting for the final processing result. If the final 143(1) intimation contains an eligible mistake apparent from the record, Section 154 rectification may provide the appropriate correction route.
Ultimately, a 143(1) intimation is not something to panic about, but it is something to review carefully. By comparing the intimation with your ITR and tax records, you can determine whether the processed result is correct and what action, if any, is required.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio
Want to read more? Explore Blogs