US Tax Filing and Compliance
Is an S Corporation Worth It? Costs, Tax Benefits and Decision ChecklistIs an S Corporation Worth It? Costs, Tax Benefits and Decision Checklist
Written by Shubham Jain

Claiming a dependent on your U.S. tax return can affect your eligibility for certain tax credits and filing benefits. However, paying someone's expenses or financially supporting a family member does not automatically make that person your dependent.
The IRS generally divides dependents into two categories: a qualifying child and a qualifying relative. Each category has separate relationship, residency, age, income, and support requirements.
Understanding these rules is especially important if you support an adult child, parent, another relative, or a family member while living outside your home country.
For federal income tax purposes, a dependent generally needs to be either your:
There are also general dependency requirements. For example, a person generally must be a U.S. citizen, U.S. national, U.S. resident alien, or resident of Canada or Mexico, although exceptions exist.
You also generally cannot claim a married person who files a joint return, except in limited circumstances, such as when the return is filed only to claim a refund.
Most importantly, determine which dependent category applies before assuming someone qualifies.
A qualifying child generally needs to satisfy five main tests:
| Test | General Requirement |
|---|---|
| Relationship | Must have an eligible family relationship with you |
| Age | Generally under 19, or under 24 if a student |
| Residency | Generally lived with you for more than half the year |
| Support | Did not provide more than half of their own support |
| Joint return | Generally did not file a joint return with a spouse |
Eligible relationships can include your child, stepchild, foster child, sibling, half-sibling, stepsibling, or a descendant of one of them.
For the age test, the person generally must be under 19 at year-end and younger than you, or under 24 if they are a qualifying student and younger than you. The age limitation generally does not apply to someone who is permanently and totally disabled.
Temporary absences for reasons such as education, illness, military service, or vacation may still count toward the residency requirement.
These five tests form the core IRS framework for determining a qualifying child.
Get expert tax filing support and claim eligible dependents and tax benefits accurately.
A qualifying relative follows different rules. Despite the name, the person does not always have to be a close relative.
Four principal tests generally apply:
Unlike a qualifying child, there is no age test for a qualifying relative.
Certain relatives, including parents, grandparents, siblings and some other family members, do not necessarily have to live with you throughout the year. Someone who is not an eligible relative may potentially satisfy the household test by living with you all year, provided the other requirements are met.
The qualifying-relative gross-income threshold is adjusted over time. For tax year 2025, the person's gross income generally must be less than $5,200, subject to exceptions.
The two categories should not be treated interchangeably.
| Rule | Qualifying Child | Qualifying Relative |
|---|---|---|
| Age requirement | Generally applies | No age limit |
| Residency | Generally more than half the year | Different relationship/household rules |
| Gross-income limit | No qualifying-relative income test | Applies |
| Support | Child cannot provide over half of own support | You generally provide over half |
| Student status | Can affect age eligibility | Not required |
For example, your 22-year-old full-time student child may potentially qualify under the qualifying-child rules.
A 30-year-old child who fails the qualifying-child age test could instead potentially qualify as a qualifying relative if the applicable income, support, and other requirements are satisfied.
Potentially, yes.
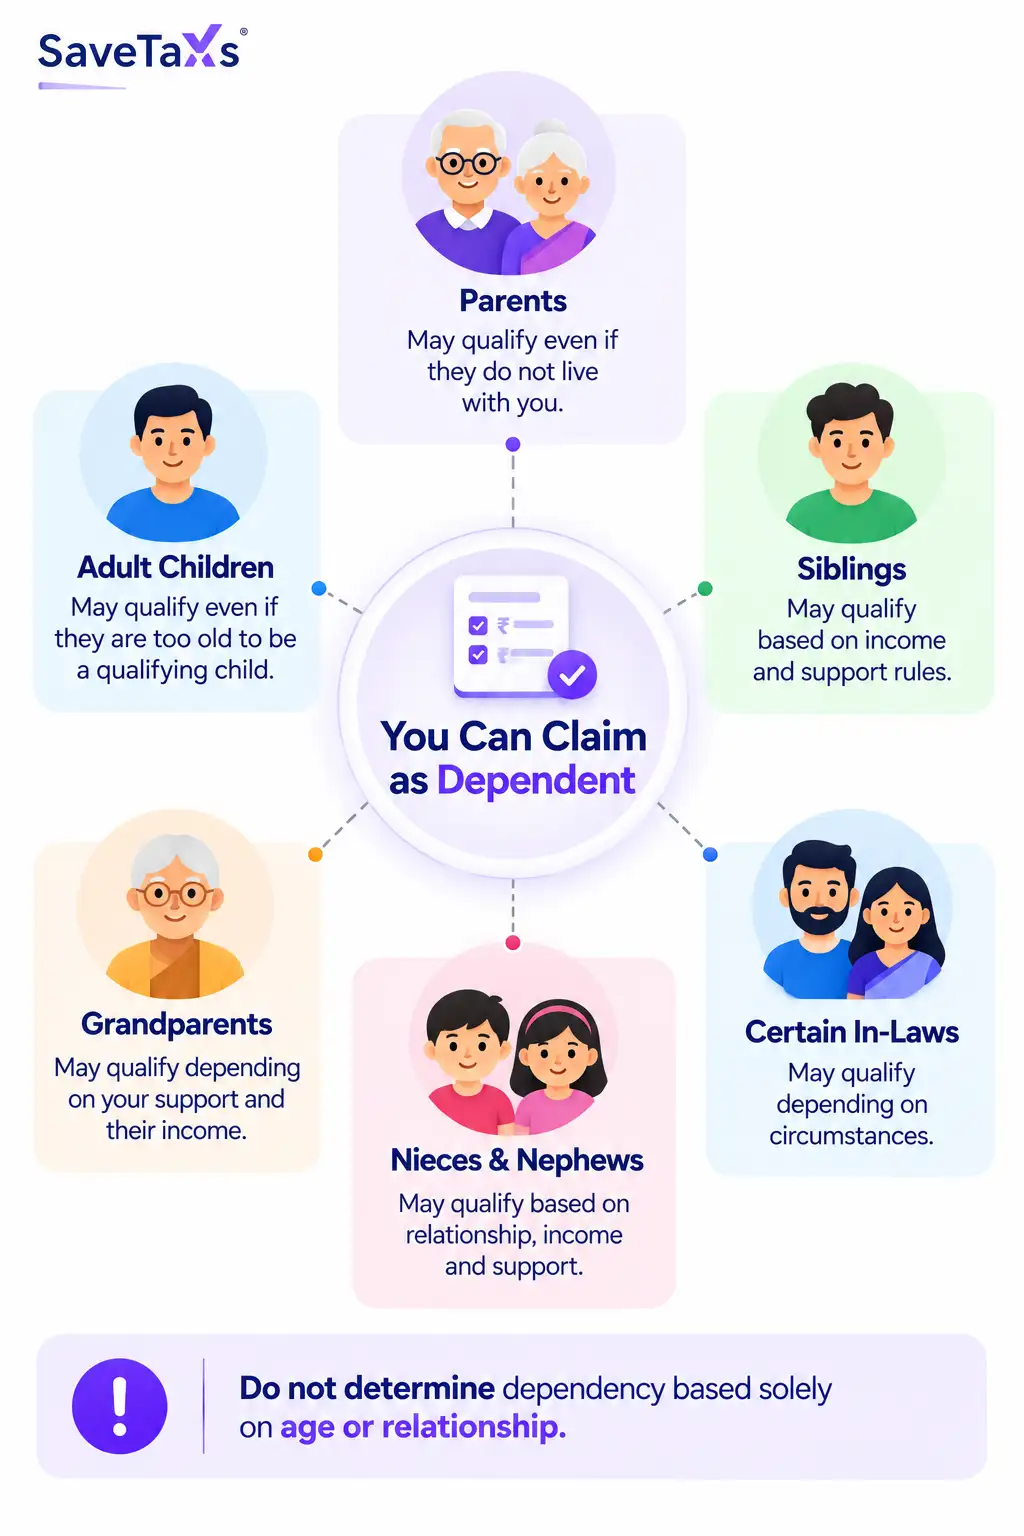
An elderly parent may qualify as your dependent even if the parent does not live with you. However, the qualifying-relative income and support requirements still need to be satisfied.
An adult child who is too old to qualify as a qualifying child may also potentially qualify as a qualifying relative.
Similarly, siblings, grandparents, nieces, nephews, and certain in-laws can potentially qualify depending on their relationship, income, support, and other circumstances.
Therefore, do not determine dependency based solely on age or relationship.
A qualifying dependent may affect eligibility for tax benefits such as the Child Tax Credit, Credit for Other Dependents, Child and Dependent Care Credit, Earned Income Tax Credit, or Head of Household filing status.
However, dependent status does not automatically qualify you for these benefits.
Each tax credit and filing status has its own requirements.
For example, being allowed to claim someone as a dependent does not necessarily mean that person is a qualifying child for the Child Tax Credit.
Therefore, first determine dependency status and then separately check the requirements for the particular tax benefit you intend to claim.
International taxpayers need to be particularly careful.
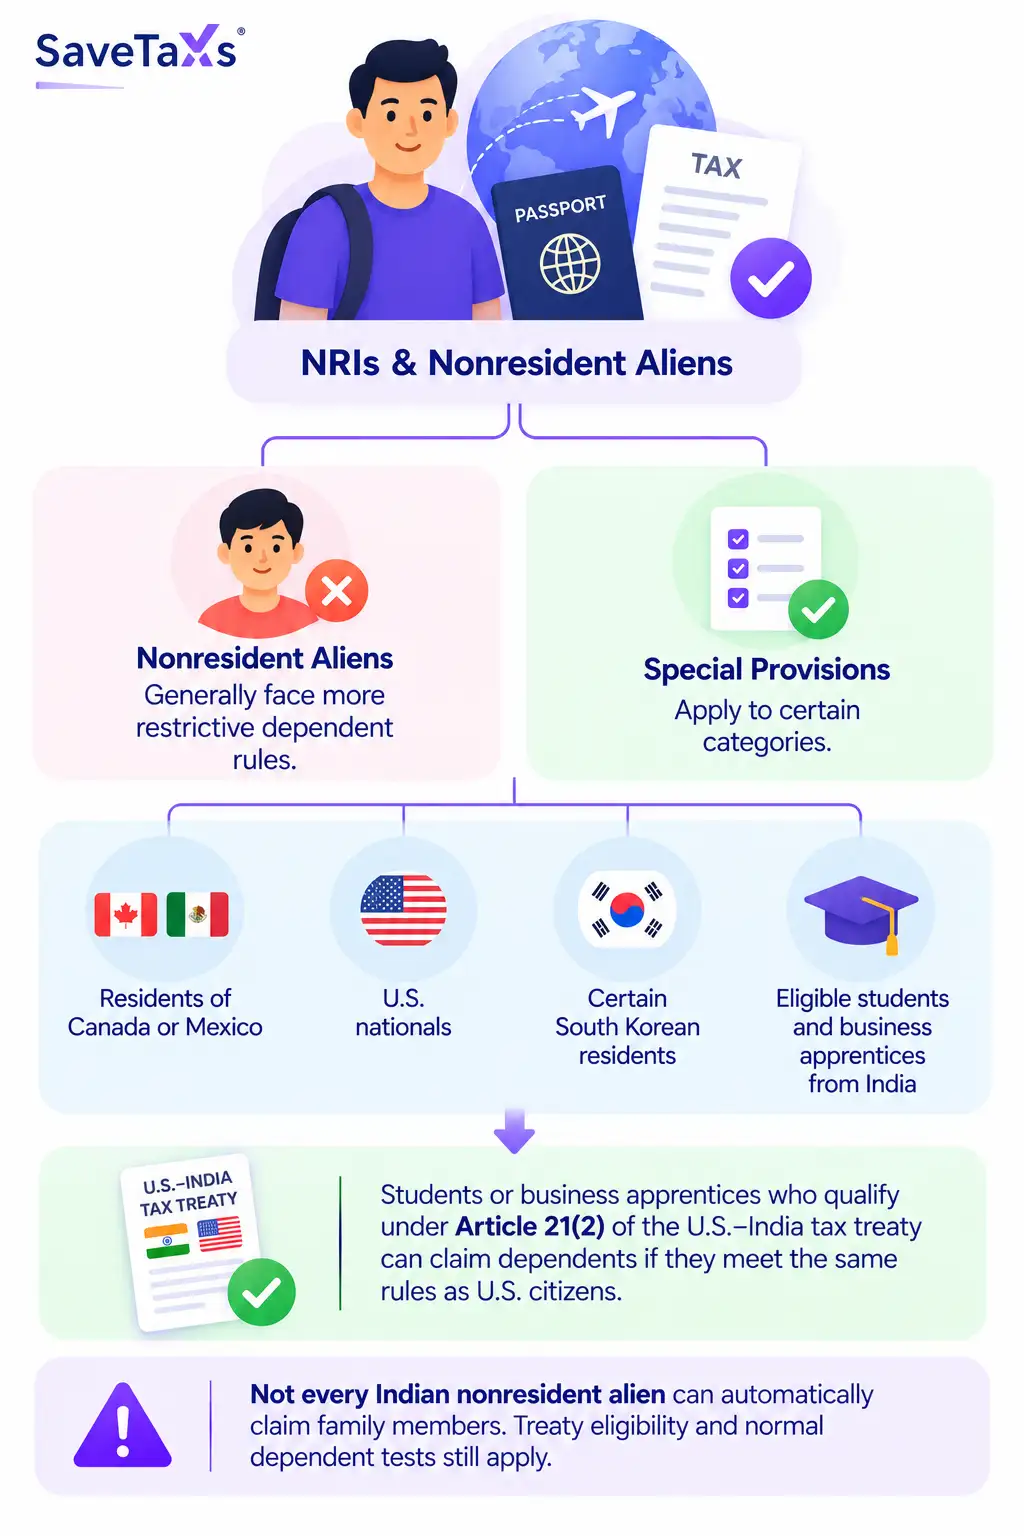
Nonresident aliens generally face more restrictive dependent rules than U.S. citizens and resident aliens. Special provisions apply to certain categories, including residents of Canada or Mexico, U.S. nationals, certain South Korean residents, and eligible students and business apprentices from India.
Importantly for Indian taxpayers, a student or business apprentice who qualifies for benefits under Article 21(2) of the U.S.–India Income Tax Treaty can claim dependents if the dependents satisfy the same applicable rules used for U.S. citizens.
This does not mean every Indian nonresident alien can automatically claim parents, children, or other family members as dependents.
Treaty eligibility and the normal dependent tests still need to be checked.
Our tax experts can help you understand IRS dependent rules and avoid filing mistakes.
A common mistake is assuming that paying most of someone's expenses automatically makes that person a dependent. Relationship, residency, income, support, citizenship/residency, and other tests may also apply.
Another mistake is using qualifying-child rules for an adult relative who should instead be evaluated under the qualifying-relative rules.
Taxpayers should also avoid assuming that dependent status automatically provides every dependent-related tax credit.
Finally, international taxpayers should not assume that sending money to relatives abroad is sufficient to claim them on a U.S. tax return.
Claiming dependents on taxes starts with determining whether the individual is your qualifying child or qualifying relative under IRS rules.
Qualifying children generally face relationship, age, residency, support, and joint-return tests. Qualifying relatives have a different framework that includes relationship or household, gross-income, and taxpayer-support requirements.
Once a person qualifies as a dependent, separately determine whether that dependent makes you eligible for a particular tax credit or filing benefit.
For NRIs and other international taxpayers, additional nonresident-alien and treaty rules may apply, so dependency eligibility should be checked carefully before filing.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio

Want to read more? Explore Blogs