NRI Income Tax Compliance
S Corporation Termination: When S Status Ends
Written by SaveTaxs Editorial Team

If you are an NRI living in Switzerland and earning income from India, you may face tax obligations in both countries. For example, you may receive dividends from Indian shares, interest from bank deposits, rental income, or capital gains from selling property in India.
The Double Tax Avoidance Agreement (DTAA) Between India and Switzerland helps determine which country can tax your income and how double taxation can be avoided.
However, not every income is exempt under the treaty. Your tax residency, income type, and applicable treaty provisions determine the benefits you can claim.
This guide explains the India–Switzerland DTAA tax rates, income-specific rules, recent MFN clause changes, and the process for claiming treaty benefits.
The India–Switzerland DTAA is a bilateral tax agreement designed to prevent double taxation and allocate taxing rights between India and Switzerland.
The original agreement was signed in 1994 and subsequently amended through protocols.
It covers several income categories, including dividends, interest, royalties, employment income, pensions, business profits, and capital gains.
Example: An NRI living in Zurich earns rental income from a property in Mumbai. India may tax that rental income because the property is located in India. Switzerland may also consider the income under its domestic tax rules.
The DTAA helps determine the applicable taxing rights and how relief is provided where the same income is taxable in both countries.
Importantly, the treaty does not automatically make income tax-free.
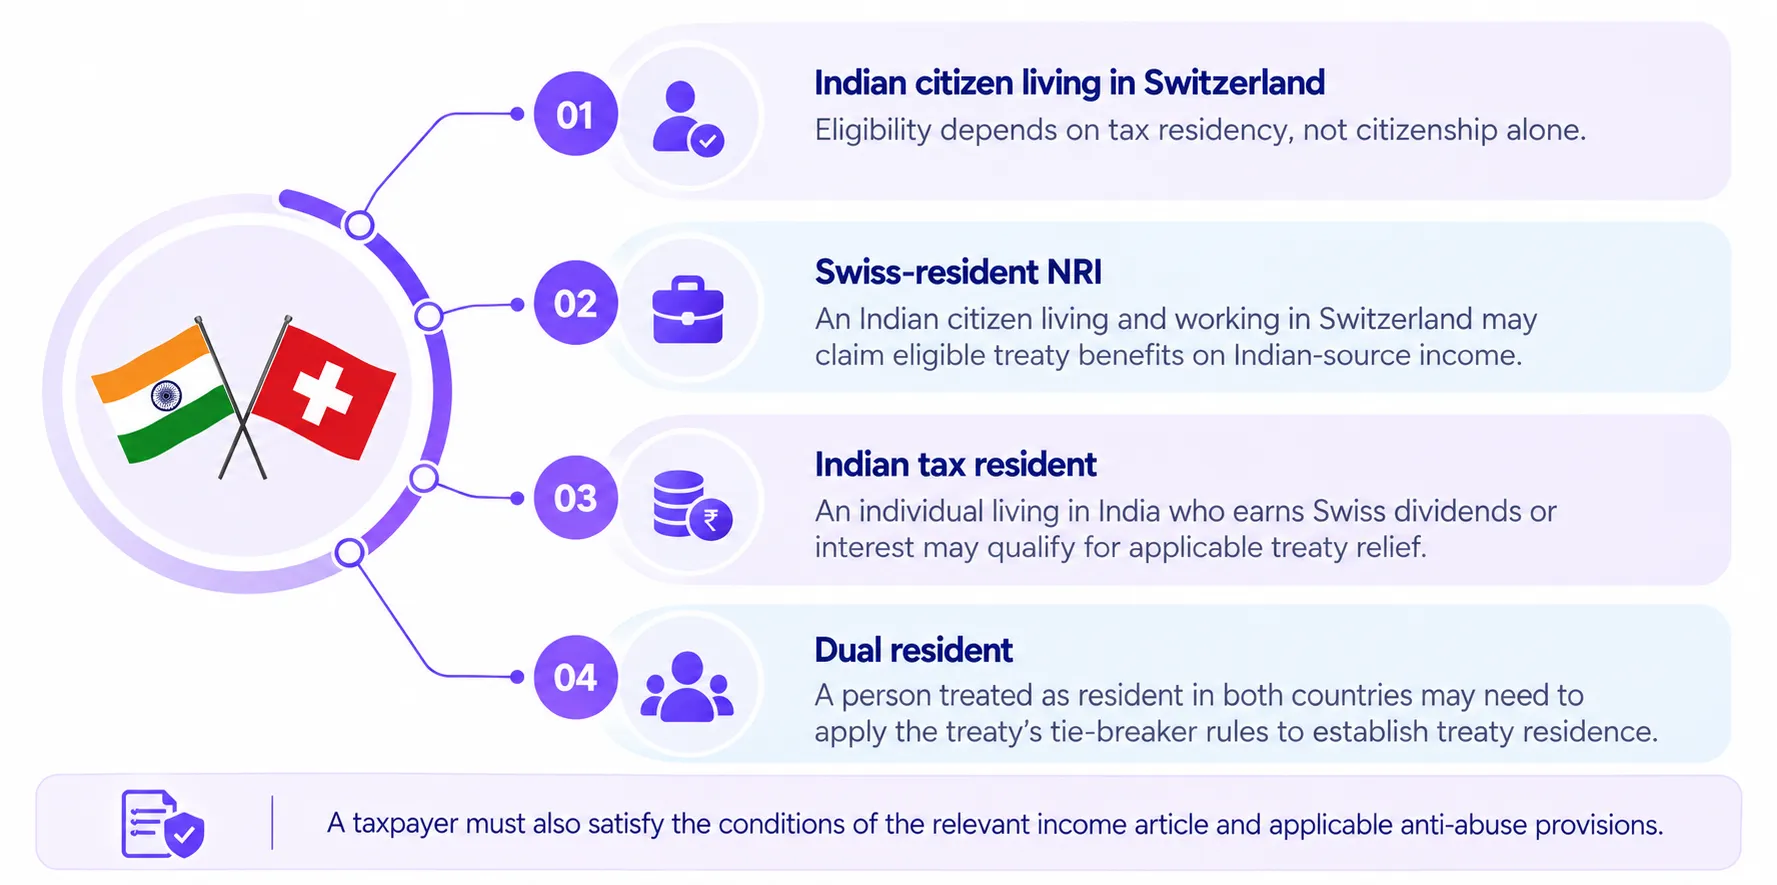
The treaty generally applies to individuals and entities that qualify as tax residents of India or Switzerland under its provisions.
For an Indian citizen living in Switzerland, eligibility depends on tax residency, not citizenship alone.
A taxpayer must also satisfy the conditions of the relevant income article and applicable anti-abuse provisions.
The agreement provides different tax treatments depending on the income earned.
| Income Type | Treaty Article | General Treaty Treatment |
|---|---|---|
| Dividends | Article 10 | Up to 10% of gross dividends |
| Interest | Article 11 | Generally up to 10% of gross interest |
| Royalties | Article 12 | Generally up to 10% of gross payments |
| Fees for technical services | Article 12 | Generally up to 10% of gross payments |
| Capital gains | Article 13 | Depends on the asset and treaty conditions |
These are general treaty limits for qualifying income. Specific exemptions, beneficial-ownership requirements, permanent-establishment exceptions, and domestic-law provisions can change the outcome.
Get expert assistance with India–Switzerland DTAA benefits and tax relief claims.
Suppose an NRI residing in Switzerland receives ₹1,00,000 in dividends from an Indian company.
If the individual qualifies for the treaty's 10% dividend withholding limit, the Indian tax on that payment would generally be limited to ₹10,000.
Without valid treaty documentation, the payer may apply domestic withholding rules instead.
Interest and royalty payments require similar checks. The correct classification of income is important because not every payment qualifies for the same treaty treatment.
Article 13 deals with capital gains from selling different assets.
For example, an NRI selling a residential apartment in India cannot assume the gain is exempt from Indian tax simply because they are a Swiss tax resident.
The relevant treaty provision and Indian capital gains rules must be considered together.
Different types of income have separate treaty rules.
A PE is a business presence that meets the treaty's requirements. If a Swiss enterprise has a PE in India, India may tax profits attributable to that establishment.
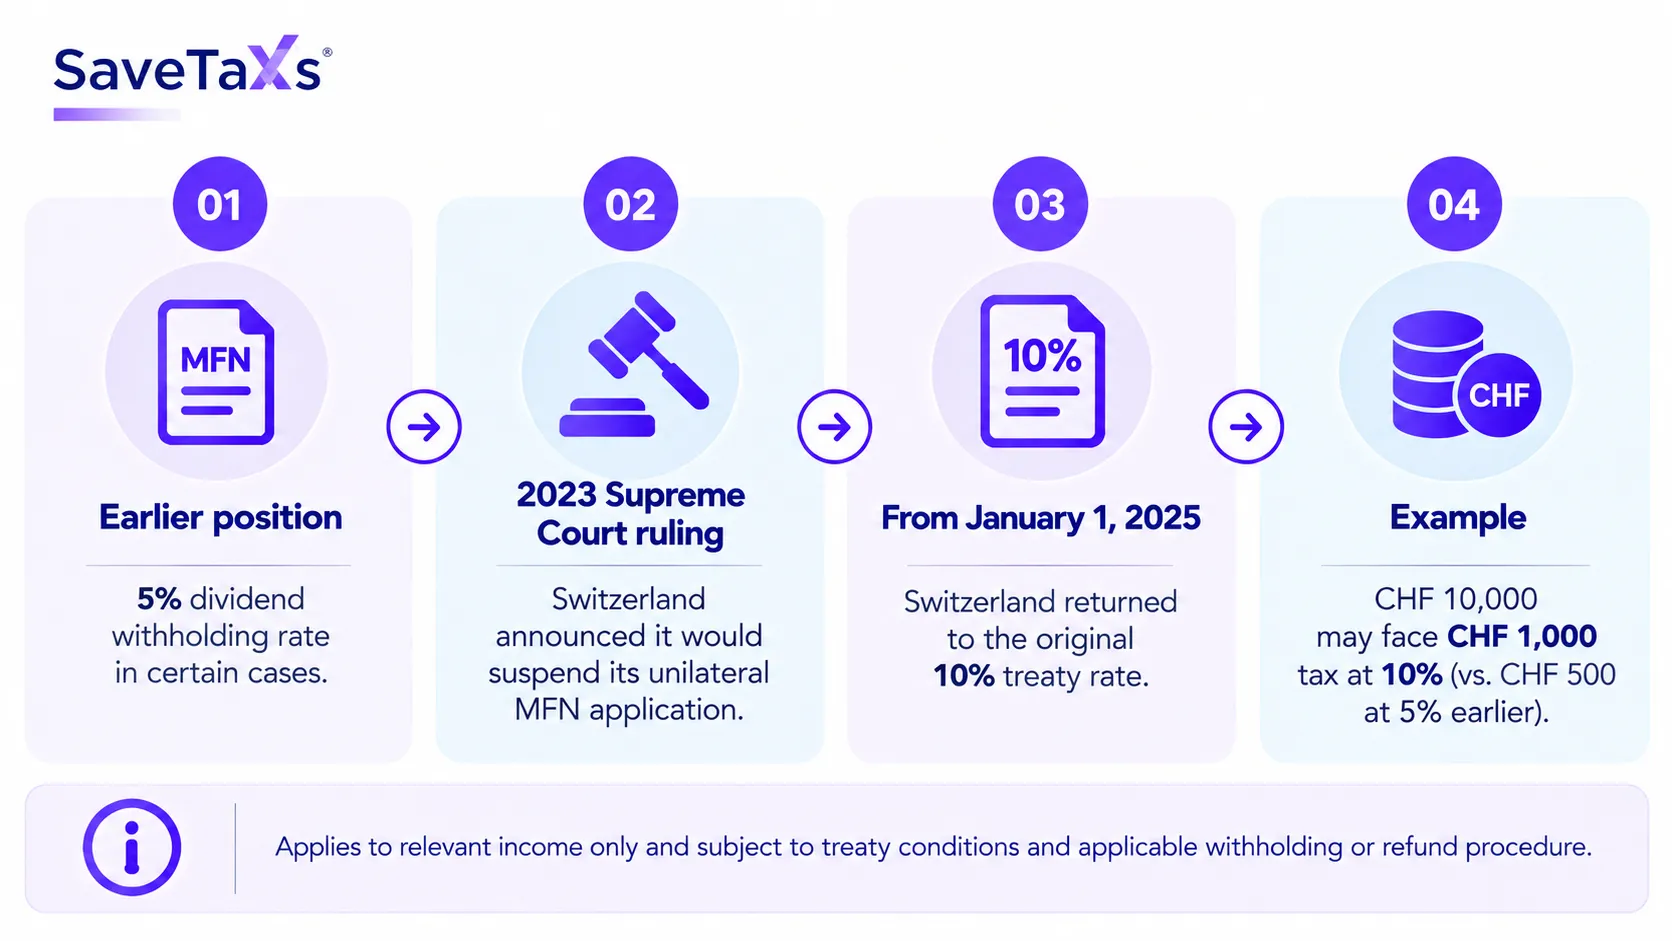
The Most-Favoured-Nation (MFN) clause has been an important issue in the India–Switzerland tax treaty.
Previously, Switzerland applied an interpretation under which a 5% dividend withholding rate could be available in certain circumstances.
However, following the Indian Supreme Court's 2023 ruling concerning MFN interpretation, Switzerland announced that it would suspend its unilateral application of the MFN clause.
From January 1, 2025, Switzerland returned to the original 10% treaty treatment for relevant dividend payments.
For example, an Indian resident receiving CHF 10,000 in qualifying Swiss dividends may face CHF 1,000 in Swiss tax under the 10% treaty rate, rather than CHF 500 under the earlier 5% interpretation.
This example assumes the recipient satisfies the treaty conditions and the applicable withholding or refund procedure.
The change primarily concerns the MFN treatment of relevant income. It should not be interpreted as a blanket change to every treaty article.
An NRI living in Switzerland should generally follow these steps when claiming treaty benefits in India.
A PAN and supporting income or withholding documents may also be required depending on the transaction.
A TRC supports treaty residency but does not, by itself, establish eligibility for every treaty benefit.
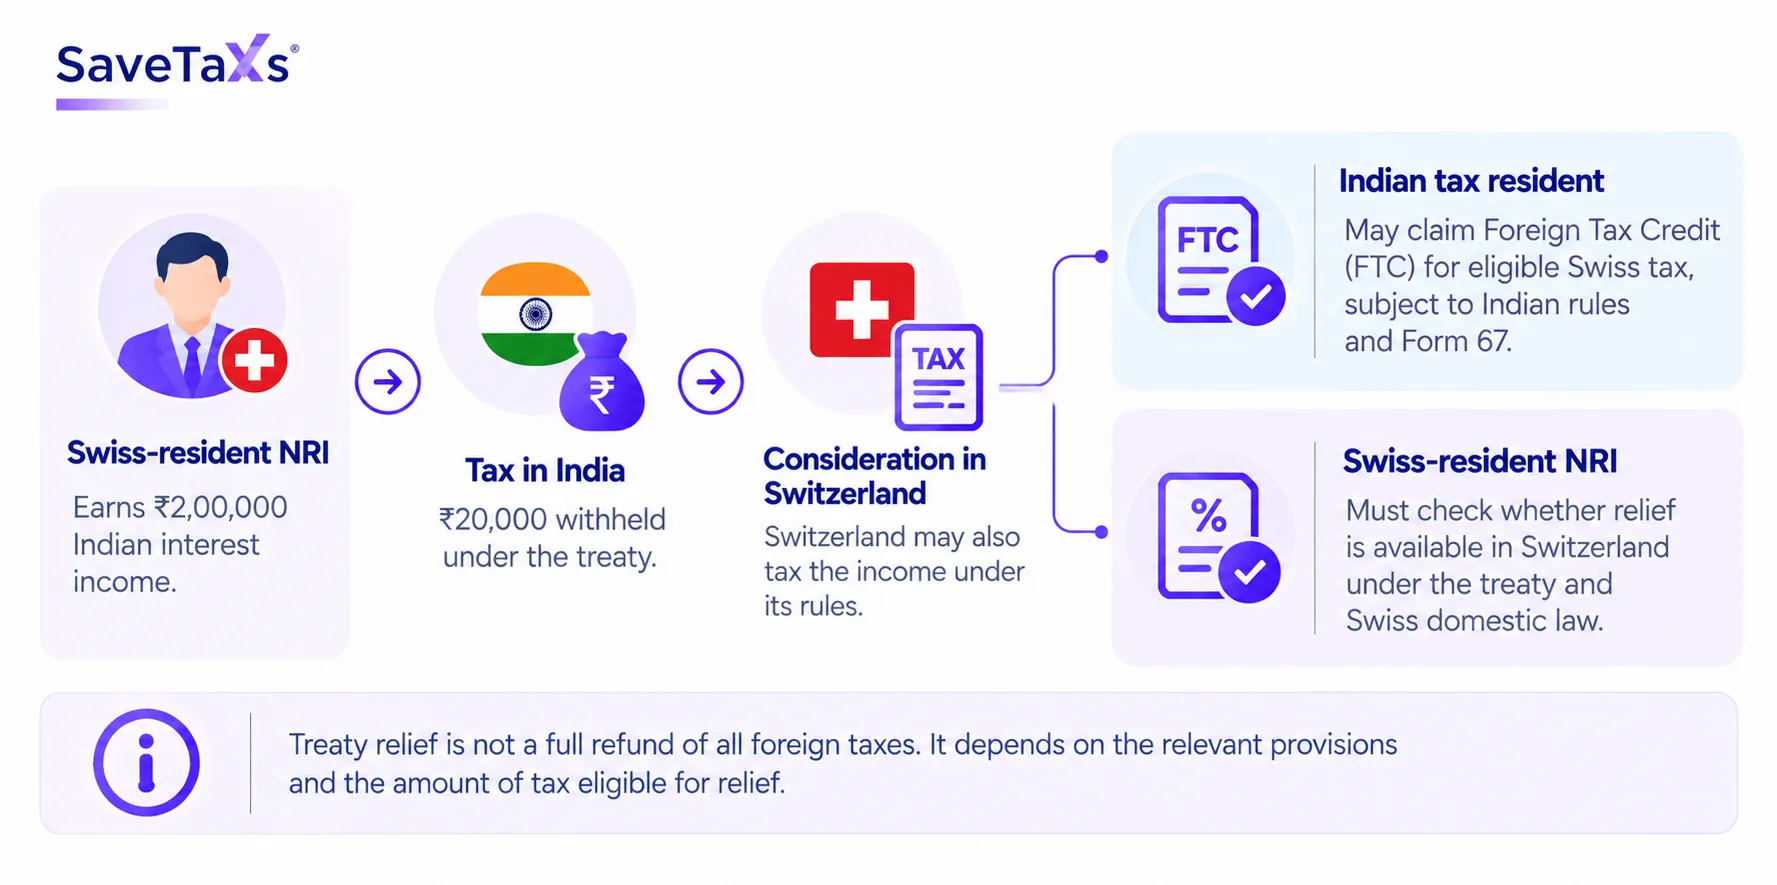
The India–Switzerland DTAA provides methods for eliminating double taxation under Article 23.
The applicable relief depends on the taxpayer's country of residence and the income involved.
For example, suppose a Swiss-resident NRI earns ₹2,00,000 in taxable Indian interest income and ₹20,000 is withheld in India under the treaty.
Switzerland may also consider the income under its tax rules. The taxpayer must then determine whether relief is available in Switzerland under the treaty and Swiss domestic law.
Similarly, an Indian tax resident who pays eligible Swiss tax on income also taxable in India may be able to claim a Foreign Tax Credit (FTC), subject to Indian rules and limitations.
Indian taxpayers claiming FTC generally need supporting tax-payment documents and Form 67 where applicable.
Treaty relief is not necessarily a full refund of all foreign taxes. It depends on the relevant provisions and the amount of tax eligible for relief.
Our tax experts can help you understand treaty rules and claim eligible tax benefits.
The Double Tax Avoidance Agreement Between India and Switzerland helps NRIs and other eligible taxpayers manage cross-border tax obligations.
The treaty can provide reduced withholding rates and relief from double taxation, but different rules apply to dividends, interest, salary, pensions, business income, and capital gains.
NRIs should pay particular attention to Switzerland's MFN clause change, confirm their tax residency, and maintain the necessary documentation before claiming treaty benefits.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Want to read more? Explore Blogs