


NRI Income Tax Compliance
S Corporation Termination: When S Status EndsS Corporation Termination: When S Status Ends
Written by Shubham Jain

Buying a home in India while living abroad can involve more than arranging a home loan. If you are an NRI who took an eligible loan to acquire a residential property, you may also want to understand whether you can claim an additional deduction on the interest paid. One important condition is that you must not have owned any residential house property on the date the qualifying loan was sanctioned.
Under Section 80EE of the Income-tax Act, 1961, an eligible individual could claim an additional deduction of up to ₹50,000 per year on home-loan interest. However, this benefit applies only to loans sanctioned during a specific period: 1 April 2016 to 31 March 2017.
The deduction is subject to conditions relating to the loan amount, property value and ownership of residential property when the loan was sanctioned. NRIs may also qualify if they meet the applicable statutory conditions and have eligible income taxable in India.
This guide explains the Section 80EE deduction, its eligibility requirements, and how NRIs should assess their claims. It also explains the corresponding provision under the Income-tax Act, 2025, effective from 1 April 2026.
Section 80EE of the Income-tax Act, 1961 provides an additional deduction for interest payable on a qualifying loan taken by an individual to acquire a residential house property.
The provision was introduced to provide additional tax relief to eligible first-time homebuyers. It allows a deduction of up to ₹50,000 in a tax year, over and above the eligible interest deduction under Section 24(b), subject to the conditions of both provisions.
The important point is that Section 80EE is not available for every home loan. The loan must have been sanctioned within the specified 2016–17 period, and the borrower must satisfy the other statutory conditions.
Section 80EE is generally relevant to taxpayers opting for the old tax regime because the deduction is restricted under the default new tax regime.
The maximum deduction under Section 80EE is ₹50,000 per year.
The actual deduction is limited to the eligible interest payable on the qualifying loan, subject to the statutory ceiling.
Suppose you have a qualifying home loan and pay ₹2.30 lakh as eligible interest during the year.
| Particulars | Amount |
|---|---|
| Eligible home-loan interest | ₹2,30,000 |
| Interest deduction under Section 24(b), assumed eligible | ₹2,00,000 |
| Remaining eligible interest | ₹30,000 |
| Additional deduction under Section 80EE | ₹30,000 |
In this example, the eligible additional deduction under Section 80EE is ₹30,000, not the full ₹50,000, because the remaining eligible interest is only ₹30,000.
The actual claim depends on the applicable property, income and tax-regime conditions.
Get assistance with your Indian tax return and applicable NRI tax deductions.
Section 80EE is available to an eligible individual who has taken a qualifying loan from a specified financial institution to acquire a residential house property.
The provision does not restrict eligibility to Indian residents alone. Therefore, an NRI may also qualify if the statutory conditions are met.
However, the following points should be checked before claiming the deduction:
Important: Being a first-time homebuyer in the ordinary sense is not enough. The specific ownership condition on the loan-sanction date must be satisfied.
For a broader overview of home-loan benefits available to NRIs, read Tax Deductions on Home Loan Repayment for NRIs in India.
To claim the deduction, the borrower must satisfy all the applicable conditions under Section 80EE.
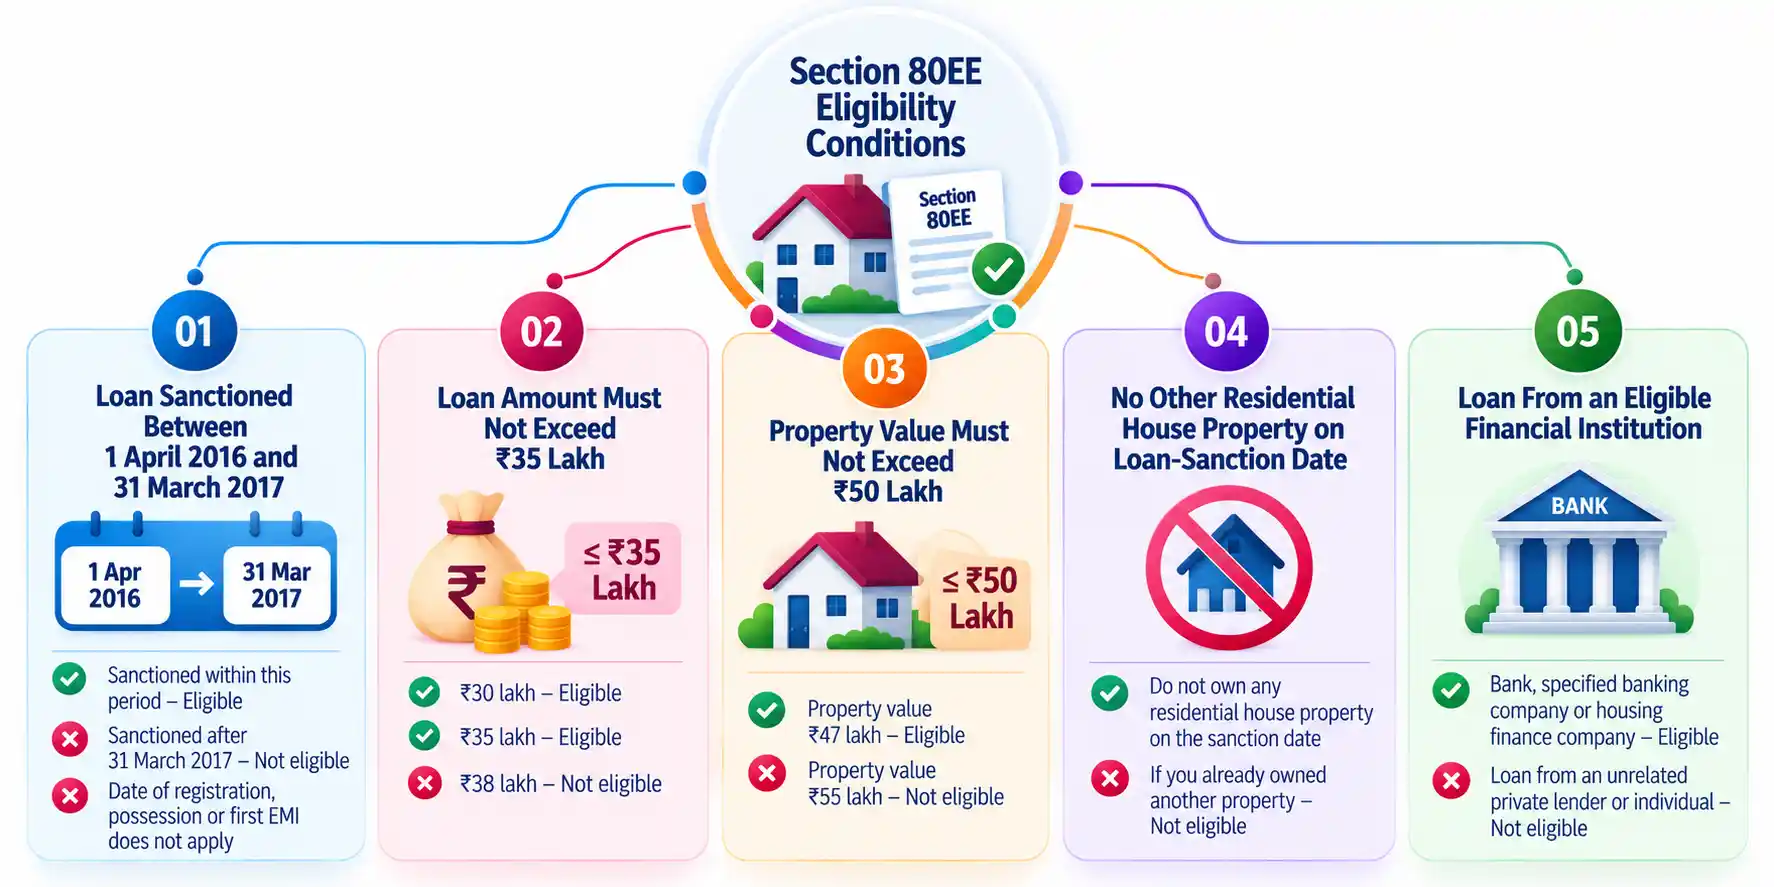
The financial institution must have sanctioned the home loan between 1 April 2016 and 31 March 2017.
The date of loan sanction is important. The date of property registration, possession, or the first EMI payment does not replace the statutory sanction-date requirement.
A loan sanctioned after 31 March 2017 does not qualify under Section 80EE merely because the borrower purchased their first home.
The amount of the loan sanctioned for acquiring the residential house property must not exceed ₹35 lakh.
For example:
A borrower whose loan exceeds ₹35 lakh does not satisfy this condition, even if the property value is below ₹50 lakh.
The value of the residential house property must not exceed ₹50 lakh.
For example, if the property value is ₹47 lakh and the qualifying loan amount is ₹34 lakh, both amounts fall within the respective limits.
However, if the property value is ₹55 lakh, the borrower does not meet this condition.
The statutory wording refers to the value of the residential house property. Do not automatically substitute a different valuation measure without checking the applicable legal interpretation and supporting documents.
The borrower must not own any residential house property on the date the financial institution sanctions the loan.
This is a specific statutory condition. It is not enough to say that the property being purchased is your first home in India without checking your ownership position on the relevant date.
For example, if you already owned another residential house property when the qualifying loan was sanctioned, you may not satisfy this condition.
For NRIs who own residential property outside India, this condition should also be examined carefully. Section 80EE refers to ownership of any residential house property and does not expressly limit the wording to properties situated in India. Foreign property ownership should therefore be reviewed before claiming the deduction.
The loan must be taken from a financial institution covered by Section 80EE.
The provision includes specified banking companies, banks or banking institutions, and housing finance companies meeting the statutory definition.
A loan from an unrelated private lender or an individual does not automatically qualify.
Yes. An NRI may claim the Section 80EE deduction if they satisfy the applicable conditions.
The provision refers to an individual taxpayer and does not make Indian income-tax residency a separate eligibility condition. Therefore, an NRI should not be treated as automatically ineligible merely because they live outside India.
However, the borrower must establish that the loan and property satisfy the statutory requirements. The individual should also have eligible gross total income taxable in India against which the deduction can be considered. The deduction cannot exceed the applicable gross-total-income limit, and the applicable tax regime must permit the claim.
Suppose an NRI living in the UAE purchased a residential property in India.
The relevant details are:
| Particulars | Details |
|---|---|
| Loan sanction date | 15 September 2016 |
| Loan amount | ₹32 lakh |
| Property value | ₹45 lakh |
| Residential property owned on sanction date | No |
| Eligible interest during the year | ₹2.40 lakh |
The loan sanction date, loan amount, property value and ownership position satisfy the stated Section 80EE conditions.
The NRI may therefore assess a claim for the additional deduction, subject to the applicable Section 24(b) treatment, tax-regime requirements and the individual's Indian taxable income.
The maximum additional deduction is ₹50,000, not an automatic ₹50,000 refund or tax saving.
No. The provision does not prescribe a minimum stay in India as a condition for claiming Section 80EE.
An NRI's residential status should nevertheless be determined separately under the applicable income-tax rules. The tax treatment of the individual's Indian income and the applicable tax regime must also be considered.
Do not confuse eligibility for a deduction with the rules used to determine residential status.
If you meet the statutory conditions, follow these steps to prepare your claim.
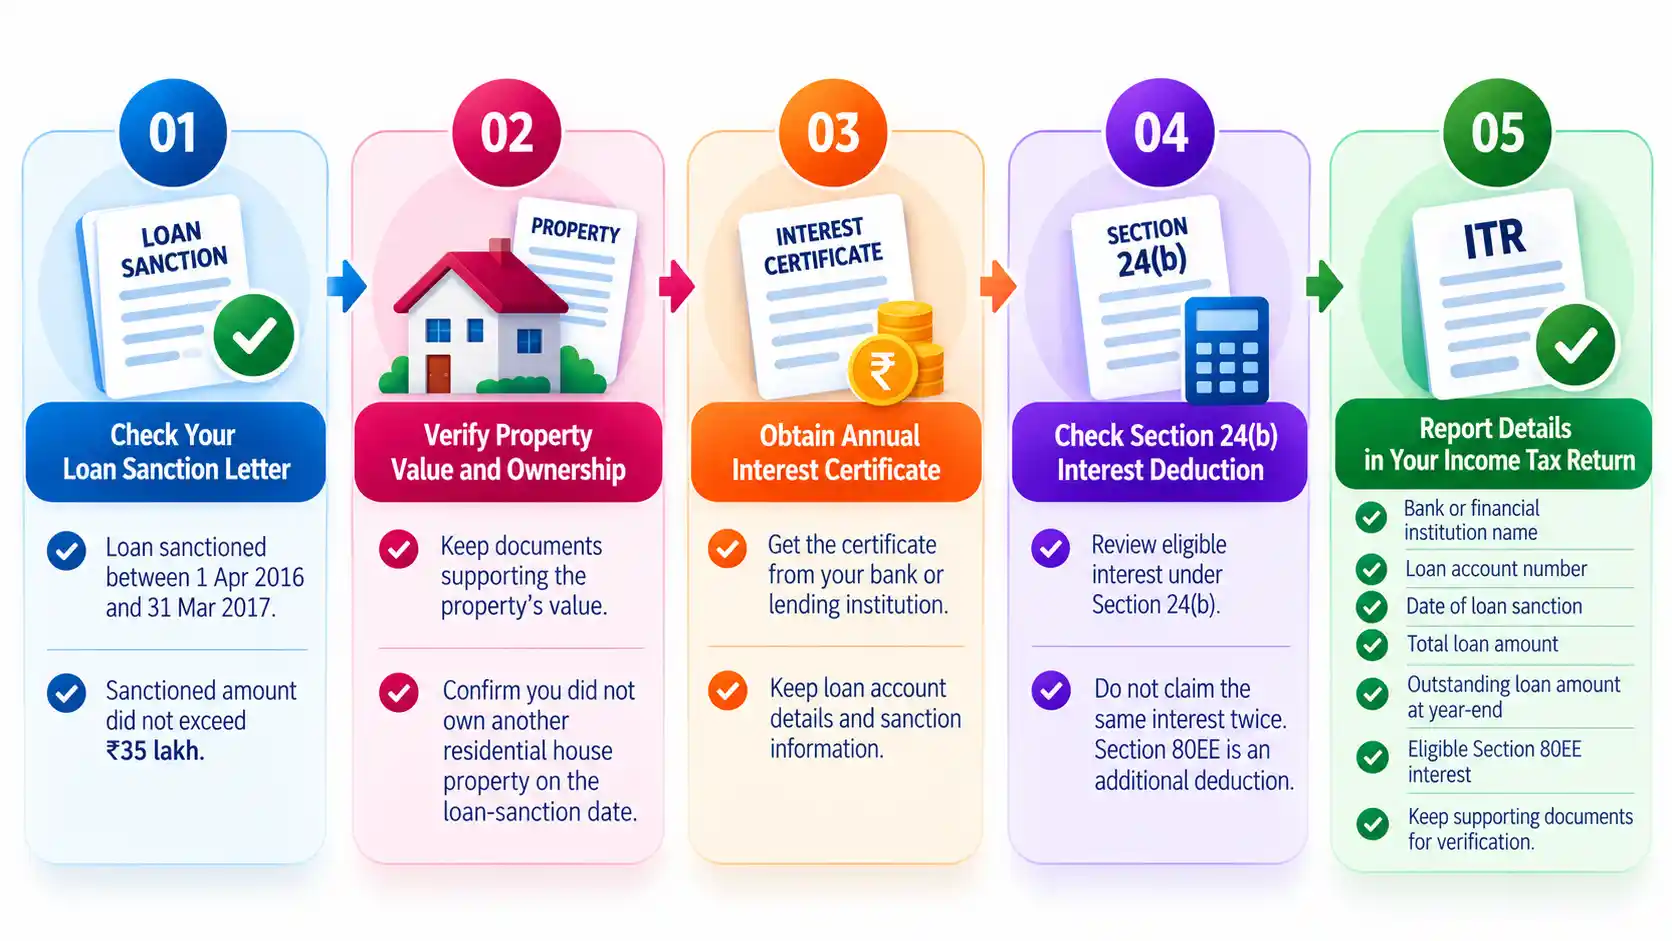
Review the sanction letter issued by your bank or eligible financial institution.
Confirm that the loan was sanctioned between 1 April 2016 and 31 March 2017 and that the sanctioned amount did not exceed ₹35 lakh.
Keep documents supporting the property's value and verify that you did not own another residential house property on the loan-sanction date.
The ownership condition should be assessed based on the facts and documents relevant to that date.
Request an annual home-loan interest certificate from the lending institution.
The certificate should help establish the interest payable during the relevant tax year. Keep the loan account details and sanction information available for your return.
Review the eligible interest under Section 24(b) before calculating the additional Section 80EE deduction.
Section 80EE provides an additional deduction, but the same interest cannot be deducted twice. The statutory restriction prevents the same interest from being claimed under another provision for the same or another assessment year.
For a detailed explanation of the general home-loan interest deduction, refer to Section 24(b) of the Income Tax Act.
The Income Tax Department's ITR guidance asks taxpayers claiming Section 80EE to provide details such as:
Keep the supporting documents available in case the department requests clarification.
For NRIs, the return should also correctly report relevant Indian taxable income and residential status.
| Document | Why it is relevant |
|---|---|
| Home-loan sanction letter | Confirms the loan sanction date and amount |
| Loan agreement | Supports the loan terms and purpose |
| Annual interest certificate | Establishes the interest payable |
| Property purchase documents | Support the property details and value |
| Ownership records | Help establish the ownership position on the sanction date |
| Loan account statement | Supports the loan balance and repayment details |
The documents should support the specific conditions of Section 80EE. Keep them with your tax records rather than relying only on prefilled return information.
Section 80EE and Section 80EEA provide additional home-loan interest deductions under different eligibility conditions. They are not interchangeable.
| Particulars | Section 80EE | Section 80EEA |
|---|---|---|
| Maximum deduction | ₹50,000 | ₹1,50,000 |
| Loan sanction period | 1 April 2016 to 31 March 2017 | 1 April 2019 to 31 March 2022 |
| Maximum loan amount | ₹35 lakh | No specific loan amount ceiling under this condition |
| Property value | Not more than ₹50 lakh | Stamp duty value not more than ₹45 lakh |
| Ownership condition | Borrower must not own a residential house property on the sanction date | Borrower must not own a residential house property on the sanction date |
| Relationship between provisions | Available subject to its own conditions | Available to an individual not eligible to claim Section 80EE, subject to its conditions |
A taxpayer cannot claim both deductions for the same qualifying interest. The applicable provision depends on the loan sanction date and the other statutory conditions. Under Section 80EEA, the deduction is limited to eligible interest remaining after the deduction under Section 24(b).
For a complete explanation of the affordable-housing deduction, read Section 80EEA Tax Deduction.
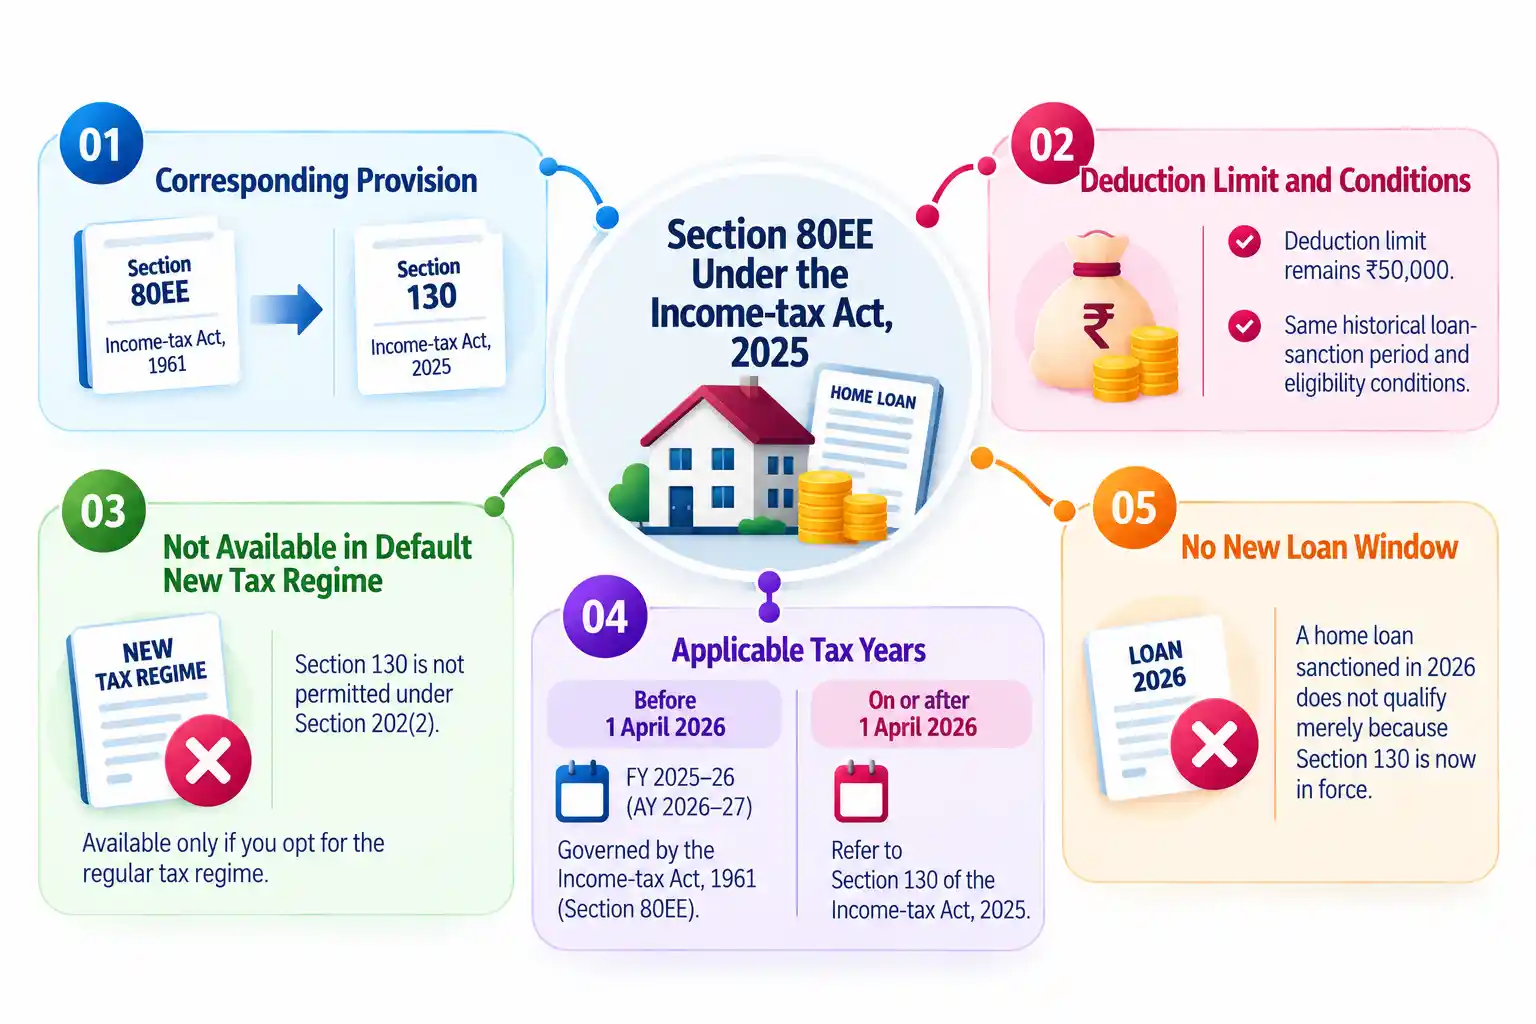
The Income-tax Act, 2025 came into effect on 1 April 2026. Section 80EE is the corresponding provision under the Income-tax Act, 1961. Its corresponding provision under the new Act is Section 130.
Section 130 retains the ₹50,000 deduction ceiling and the same historical loan-sanction period and eligibility conditions.
However, taxpayers must also consider Section 202 of the Income-tax Act, 2025, which governs the default new tax regime. Since Section 130 is not among the deductions permitted under Section 202(2), the Section 130 deduction is not available under the default new tax regime. An eligible individual who opts out of the default regime may consider the deduction under the regular tax regime, subject to the applicable conditions.
This distinction matters when filing returns for different tax years:
The transition does not reopen the loan-sanction window. A new home loan sanctioned in 2026 does not qualify merely because Section 130 is now in force.
Eligible individuals opting for the regular tax regime may consider the deduction, subject to the applicable statutory conditions. Do not assume that the tax-regime treatment for an earlier assessment year automatically applies under the new Act.
Get your Section 80EE eligibility and supporting documents reviewed by an NRI tax expert.
Section 80EE provides an additional home-loan interest deduction of up to ₹50,000 to eligible individuals who meet its specific conditions. The benefit applies to qualifying loans sanctioned between 1 April 2016 and 31 March 2017. NRIs may also qualify if they satisfy the applicable requirements and have eligible income taxable in India.
Before claiming the deduction, review your loan sanction letter, property ownership records, interest certificate, and applicable tax regime. For tax years beginning on or after 1 April 2026, also consider the corresponding provision under Section 130 of the Income-tax Act, 2025 and the restrictions under Section 202 governing the default new tax regime.
Savetaxs can assist NRIs in reviewing their Indian home-loan tax eligibility, understanding applicable interest deductions, and preparing their Indian income tax returns. Our tax experts can help assess the relevant provisions and identify the documents and information required to support your claim. If you are unsure whether your home loan qualifies for Section 80EE or how to report the deduction in your ITR, seek professional tax guidance before filing.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio
Want to read more? Explore Blogs
For tax years governed by the Income-tax Act, 1961, Section 80EE is not available under the default new tax regime under Section 115BAC; eligible taxpayers would need to opt for the old tax regime and satisfy its conditions.
For tax years beginning on or after 1 April 2026, the corresponding deduction under Section 130 of the Income-tax Act, 2025 is not available under the default new tax regime governed by Section 202. An eligible individual may consider claiming the deduction under the regular tax regime, subject to the applicable statutory conditions.