NRI Income Tax Compliance
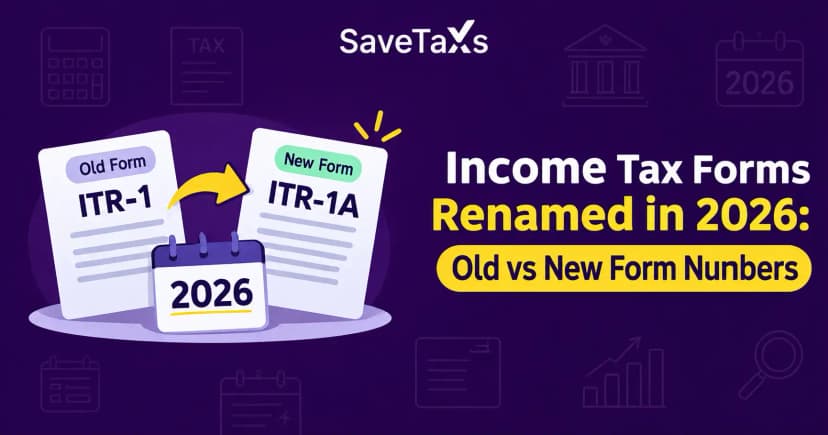
Income Tax Forms Renamed in 2026: Old vs New Form NumbersIncome Tax Forms Renamed in 2026: Old vs New Form Numbers
Written by Vipul Jain


If you have earned income abroad and paid tax there, you have probably wondered whether India will tax the same income again. The important catch is that Form 67 is not a form that every NRI can use; its applicability depends on your residential status and the rules governing Foreign Tax Credit (FTC). In this guide, we explain Form 67, FTC eligibility, required documents, filing timelines, and how the rules have changed from April 1, 2026.
Form 67 is the former prescribed form for Foreign Tax Credit claims under Rule 128 of the Income-tax Rules, 1962.
Form 67 applies to eligible resident taxpayers, so an individual who is genuinely non-resident for Indian tax purposes should not automatically assume that Form 67 applies to them.
Foreign Tax Credit reduces eligible Indian tax liability for qualifying foreign taxes, subject to applicable Indian tax law and DTAA conditions.
The credit is not automatically equal to the foreign tax paid because Indian FTC rules impose limits on the amount that can be credited.
Foreign income and foreign-tax evidence must be maintained before claiming the credit.
From April 1, 2026, Form 44 replaced Form 67 under the Income-tax Rules, 2026 for the new tax-law framework.
The applicable form depends on the relevant tax year and governing law, so taxpayers should verify the form applicable to their particular return.
Form 67 is the prescribed statement historically used by an eligible resident taxpayer to furnish foreign-income and foreign-tax details for claiming Foreign Tax Credit in India. Under the earlier Rule 128 framework, the form captured information about foreign income, tax paid or deducted abroad, and the FTC claimed.
Foreign Tax Credit is relief that allows an eligible taxpayer to receive credit in India for qualifying foreign tax paid on income that is also taxed in India. For example, if a resident taxpayer earns interest from a foreign bank, pays qualifying tax on that interest overseas, and offers the same income to tax in India, the taxpayer may be able to claim an eligible FTC.
At the same time, Form 67 should not be confused with the income-tax return. Form 67 provided the foreign-tax information required for the credit, while the ITR remained the return through which income was reported and the resulting tax liability was determined.
Important for NRIs: Rule 128 specifically applied Foreign Tax Credit to a resident assessee. Therefore, an individual who is non-resident under Indian tax law should not assume that Form 67 is applicable merely because they paid tax in another country.
Foreign Tax Credit matters because it can provide relief when the same foreign-source income is subject to tax in both the foreign country and India. The available credit is governed by Indian tax law and, where applicable, the relevant DTAA.
For example, suppose an eligible resident taxpayer has foreign income on which ₹40,000 of qualifying foreign tax was paid, while the corresponding Indian tax attributable to that income is ₹30,000. The FTC is not automatically ₹40,000; the applicable rules generally restrict the credit to the amount allowable under the prescribed computation. Rule 128 provides that the credit is generally the lower of the Indian tax payable on that income and the eligible foreign tax, subject to treaty-related limitations.
Moreover, FTC can be claimed against tax, surcharge, and cess but not against interest, fee, or penalty under the earlier Rule 128 framework. This distinction is important when estimating the actual benefit of a foreign-tax credit.
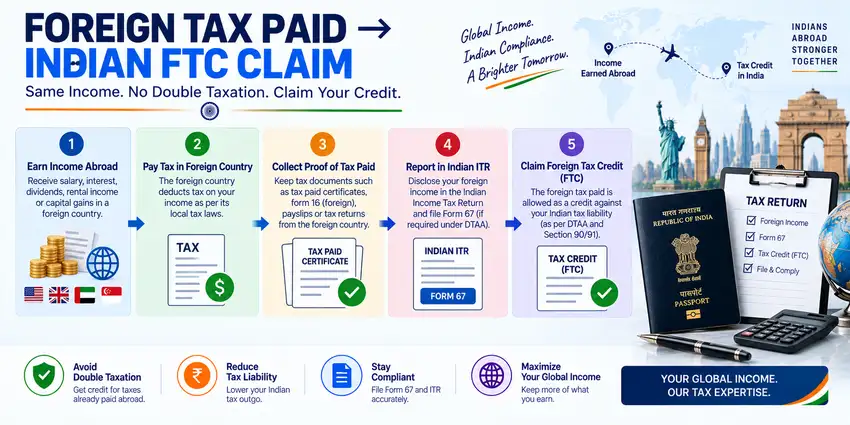
Under the earlier Rule 128 framework, Form 67 was intended for resident taxpayers claiming credit for eligible foreign tax. The Income Tax Department's Form 67 guidance expressly describes the form as applicable to resident taxpayers.
First, determine your Indian residential status for the relevant tax year before deciding whether Form 67 is applicable. Being an NRI in everyday language is not enough to establish eligibility; Indian tax residency is determined under the applicable income-tax provisions.
Second, identify whether the foreign income has been offered to tax or assessed to tax in India. The foreign tax must also fall within the category of tax eligible for credit under Indian law or an applicable DTAA.
| Check | What you should verify |
|---|---|
| Residential status | Whether you are resident under the applicable Indian tax rules |
| Foreign income | Nature and amount of income earned abroad |
| Foreign tax | Tax paid or deducted on that income |
| Treaty | Whether India has a DTAA with the relevant country |
| Indian tax | Tax attributable to the corresponding foreign income |
| Evidence | Foreign tax certificate, statement, payment or deduction proof |
Do not use Form 67 simply because you have foreign income. If you are genuinely non-resident in India, first determine whether Indian law provides an FTC mechanism applicable to your circumstances rather than assuming Form 67 is required.
An FTC claim requires evidence showing the nature of the foreign income and the foreign tax paid or deducted. Under the earlier Rule 128, supporting evidence could include a certificate or statement from the foreign tax authority or the person responsible for deducting the tax.
Before preparing the claim, keep the following information available:
Foreign country or territory where the income arose
Nature and amount of foreign income
Foreign tax paid or deducted
Evidence of foreign tax payment or deduction
Applicable DTAA details, where relevant
Indian income and tax details
Relevant assessment-year information
For example, a foreign salary statement showing income and tax withheld can support the foreign-tax details, subject to the documentation requirements applicable to the claim.
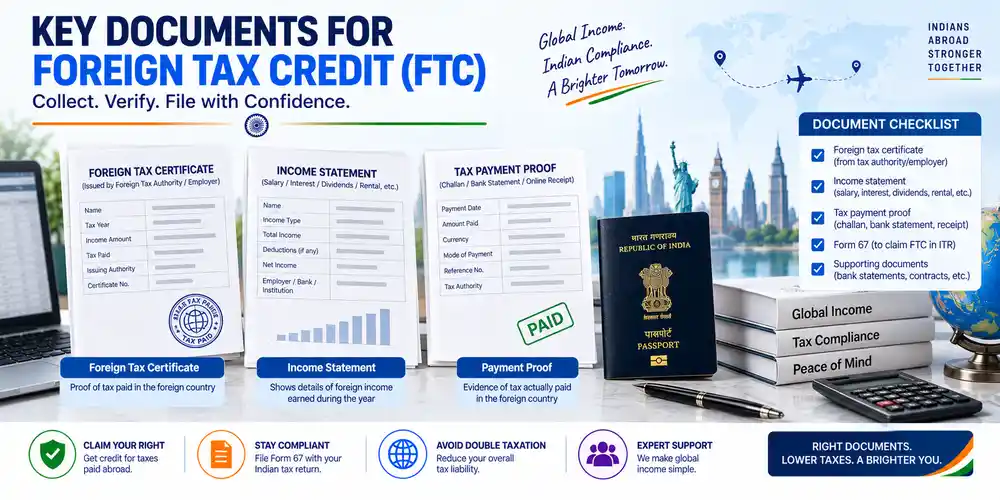
Under the earlier framework, Form 67 was filed online through the Income Tax e-Filing portal. The Income Tax Department's user manual states that Form 67 could be submitted only through the online mode.
For an assessment year to which the earlier Form 67 rules apply, the practical process is:
Determine your residential status and FTC eligibility.
Identify each foreign income source and the corresponding foreign tax.
Collect foreign-tax evidence and verify that the figures match your records.
Log in to the Income Tax e-Filing portal and access the applicable statutory-form section.
Select Form 67 and the relevant assessment year, where Form 67 is applicable.
Enter the foreign-income and tax-credit details required in the form.
Attach the prescribed supporting documents and complete verification.
Submit the form and retain the acknowledgement with your tax records.
The earlier Form 67 contained Part A, Part B, verification, and attachments, with Part A covering basic taxpayer information and foreign-income/FTC details. Part B addressed matters such as foreign-tax refunds resulting from loss carry-back and disputed foreign tax.
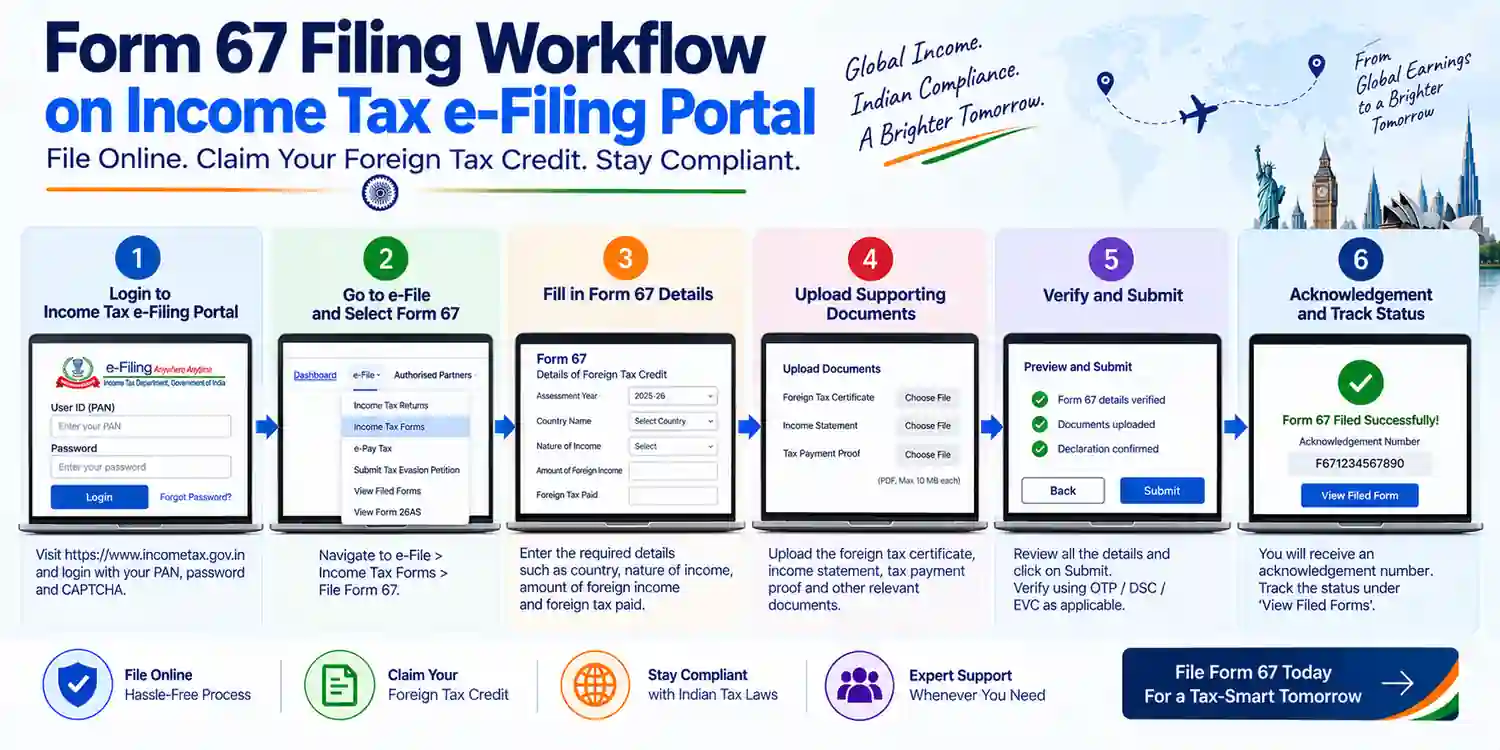
For the earlier Rule 128 framework, Form 67 and the supporting foreign-tax statement had to be furnished within the prescribed timeline linked to the relevant assessment year and return filing. The Income Tax Department's current historical Form 67 guidance should therefore be checked against the assessment year for which the claim is being made.
That timing rule is especially important because you should not assume that filing Form 67 after the ITR deadline will always be acceptable. The applicable requirement depends on the governing law and tax year.
From April 1, 2026, Form 44 replaced the earlier Form 67 under the Income-tax Rules, 2026. The Income Tax Department describes Form 44 as the new statement for foreign income and Foreign Tax Credit under Rule 76.
Under the new framework, Form 44 is required for a resident assessee claiming credit for foreign tax paid on foreign income, and the department states that it is generally due within 12 months from the end of the relevant tax year, subject to the applicable conditions.
Therefore, an article discussing Form 67 should always identify the relevant assessment or tax year. Otherwise, readers filing under the post-April-1-2026 framework could follow an outdated form requirement.
Foreign Tax Credit is claimed in conjunction with reporting the relevant foreign income in the income-tax return and furnishing the prescribed foreign-tax statement. Form 67 or the applicable successor form does not replace the ITR.
For example, if an eligible resident taxpayer reports foreign interest income in India and has qualifying foreign tax deducted from that interest, the taxpayer should reconcile the foreign income, foreign tax, Indian tax computation, and FTC claim before filing.
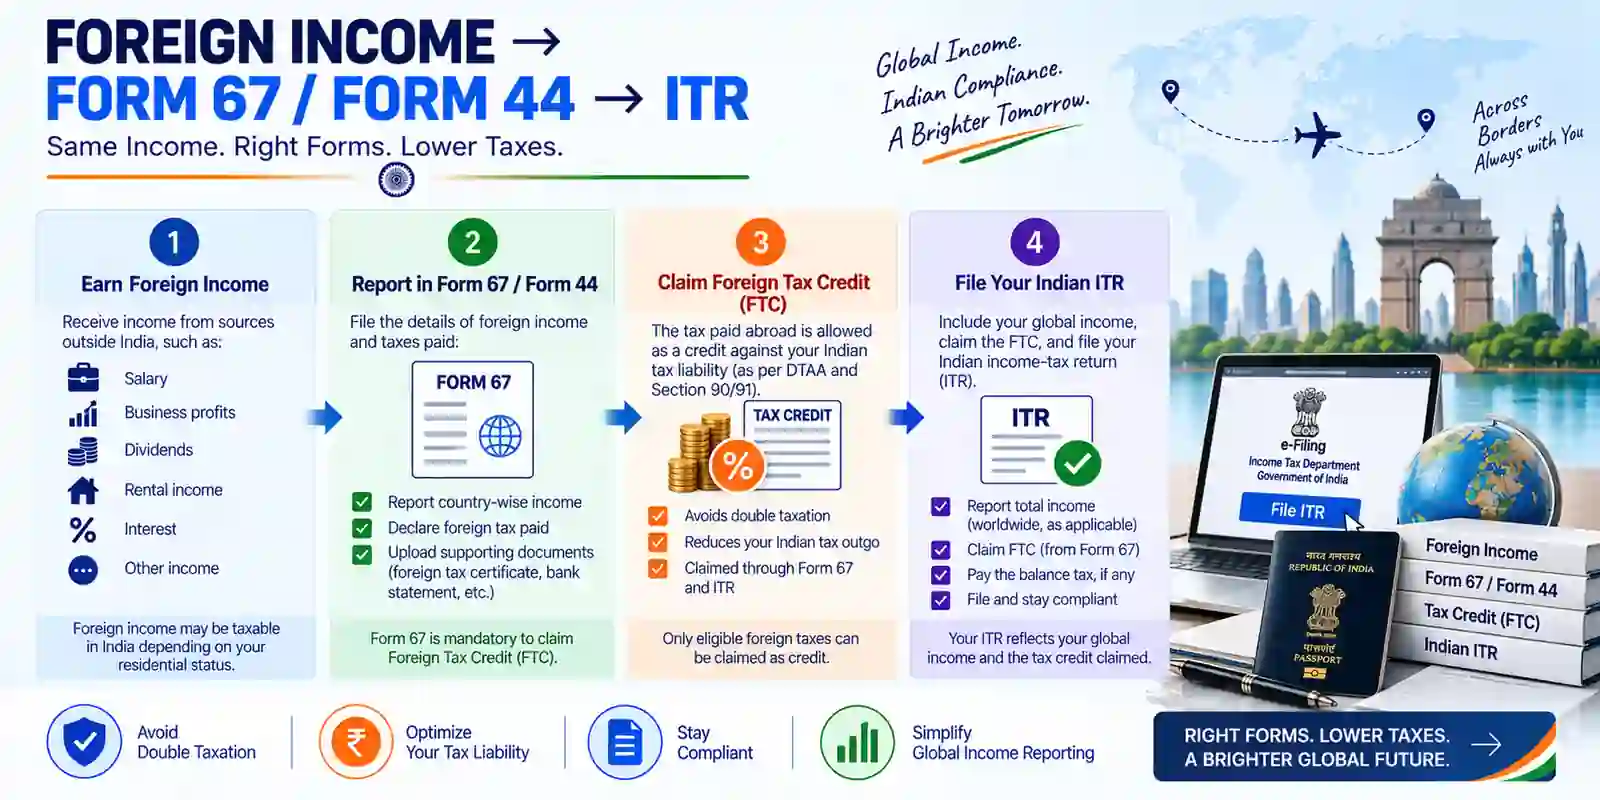
An FTC calculation compares the eligible foreign tax with the Indian tax attributable to the corresponding foreign income. For example, assume an eligible resident reports ₹2,00,000 of foreign interest income, pays ₹30,000 of qualifying foreign tax, and the applicable Indian tax attributable to that income is ₹22,000.
In this simplified illustration, the allowable FTC would generally be limited to ₹22,000 rather than automatically allowing the full ₹30,000, subject to the applicable law, treaty, and detailed computation. The example is illustrative and does not account for every possible tax adjustment.
A pre-filing reconciliation helps prevent incorrect FTC claims and documentation mismatches. Before submitting your claim, verify:
Your residential status for the relevant tax year
The correct form for that tax year
Foreign income reported in the ITR
Foreign tax actually paid or deducted
Currency conversion used for the FTC computation
Applicable DTAA provisions
Supporting foreign-tax evidence
Any disputed foreign tax
Any foreign-tax refund already received or expected
Under the earlier Rule 128, foreign tax was converted using the telegraphic transfer buying rate on the last day of the month immediately preceding the month in which the foreign tax was paid or deducted.
The first step is to determine your Indian residential status and the tax-year-specific FTC rules before preparing Form 67 or its successor. This prevents a common mistake: treating every person earning foreign income as eligible to file the same FTC form.
Next, reconcile your foreign income, foreign tax, Indian tax liability, and supporting documents. If the rules applicable to your tax year require Form 67, follow the prescribed process; for the new 2026 framework, check whether Form 44 applies instead.
Form 67 was the prescribed FTC statement under the earlier Rule 128 framework, but its applicability is tied to resident taxpayers and the relevant tax year. NRIs should therefore verify their Indian residential status and the law applicable to their return before assuming that Form 67 is required.
Moreover, the FTC amount depends on the applicable Indian rules, foreign tax, treaty provisions, and Indian tax attributable to the corresponding income. From April 1, 2026, taxpayers under the new Income-tax Rules should also check the replacement Form 44 rather than relying on older Form 67 guidance.
By reconciling your foreign income, foreign tax evidence, applicable treaty provisions, and Indian tax return before filing, you can make your FTC claim more accurate and avoid relying on outdated compliance guidance.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio
Want to read more? Explore Blogs