US Tax Forms
Form 2350 vs Form 4868 for Taxpayers AbroadForm 2350 vs Form 4868 for Taxpayers Abroad
Written by Shubham Jain
If you are a nonresident alien who earns income connected with the United States, you may need to file IRS Form 1040-NR, officially called the U.S. Nonresident Alien Income Tax Return.
For Indians and NRIs, one of the biggest sources of confusion is the term “nonresident.” Being an NRI under Indian tax law does not automatically make you a nonresident alien under U.S. tax law. The United States applies its own tax-residency rules.
Therefore, before filing Form 1040-NR, you first need to determine your U.S. tax status and whether you actually have a filing requirement.
This guide explains who files Form 1040-NR, the income reported on it, how it differs from Form 1040, the relevant schedules, and the filing deadline.
Form 1040-NR is the U.S. federal income tax return used by nonresident alien individuals who are required to file a U.S. income tax return.
The IRS uses the form to determine a nonresident alien's taxable U.S. income, applicable deductions and credits, tax liability, payments, refund, or balance due.
A foreign individual is generally considered a U.S. resident alien for tax purposes if they meet either the green card test or substantial presence test for the relevant calendar year, subject to applicable exceptions. If neither test is met, the person is generally treated as a nonresident alien, although treaty provisions and other special rules can affect the final determination.
For example, an Indian citizen living in India who earns certain U.S.-source income may remain a nonresident alien for U.S. tax purposes. If a U.S. return is required, Form 1040-NR may apply.
On the other hand, an Indian citizen who meets the substantial presence test may be treated as a U.S. resident alien and generally use Form 1040 instead, subject to applicable exceptions or treaty positions.
Not every foreign person who receives money from the United States automatically needs to file a 1040-NR tax return.
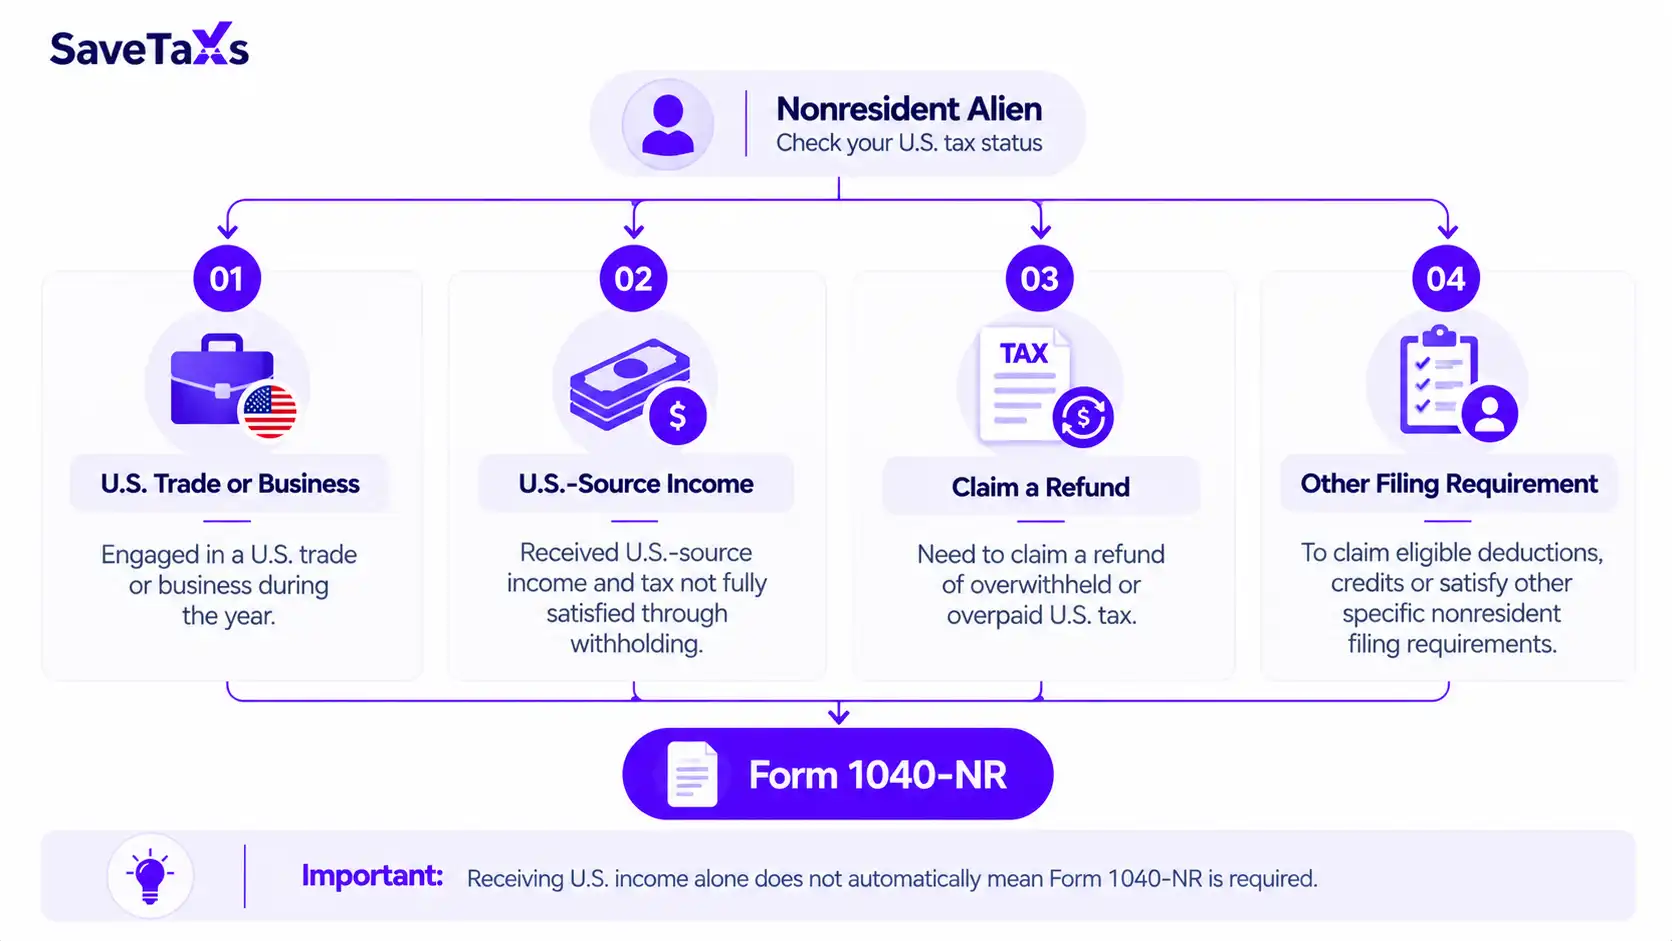
According to the IRS, filing requirements can arise in several circumstances. A nonresident alien generally must file Form 1040-NR if, for example, they were engaged in a trade or business in the United States during the year—even if they had no income from that trade or business, no U.S.-source income, or their income was exempt from U.S. tax under a treaty or Code provision, subject to limited exceptions.
A filing requirement may also arise where a nonresident alien who was not engaged in a U.S. trade or business received U.S.-source income and not all of the U.S. tax due was satisfied through withholding.
You may also file Form 1040-NR when necessary to:
This means the question is not simply:
“Did I receive U.S. income?”
Instead, determine your U.S. residency status, the nature of your U.S. income, whether you were engaged in a U.S. trade or business, and whether the applicable U.S. tax was already fully satisfied through withholding.
Form 1040 and Form 1040-NR are both individual federal income tax returns, but they generally apply to different U.S. tax statuses.
| Point | Form 1040 | Form 1040-NR |
|---|---|---|
| Generally used by | U.S. citizens and resident aliens | Nonresident aliens required to file |
| General tax scope | Worldwide income | Income taxable under U.S. nonresident-alien rules |
| U.S. tax status | Citizen/resident taxpayer | Nonresident alien |
| Foreign income | Generally included under worldwide-income rules | Generally outside U.S. tax unless subject to applicable U.S. taxing rules |
| Main purpose | Regular individual federal income tax return | Nonresident alien tax return |
For NRIs, this distinction is particularly important.
Suppose an Indian citizen moves to the United States and meets the substantial presence test. Even if that person remains an NRI under Indian tax law, they may be a U.S. resident alien for federal tax purposes and generally file Form 1040.
Conversely, an Indian resident earning certain income from the United States may remain a nonresident alien and potentially need Form 1040-NR.
Therefore, Form 1040 vs 1040-NR should be determined using U.S. tax residency—not simply nationality, citizenship, or Indian residential status.
A key part of understanding Form 1040-NR filing requirements is distinguishing between two broad categories of income: Effectively Connected Income and certain U.S.-source FDAP income that is not effectively connected with a U.S. trade or business.
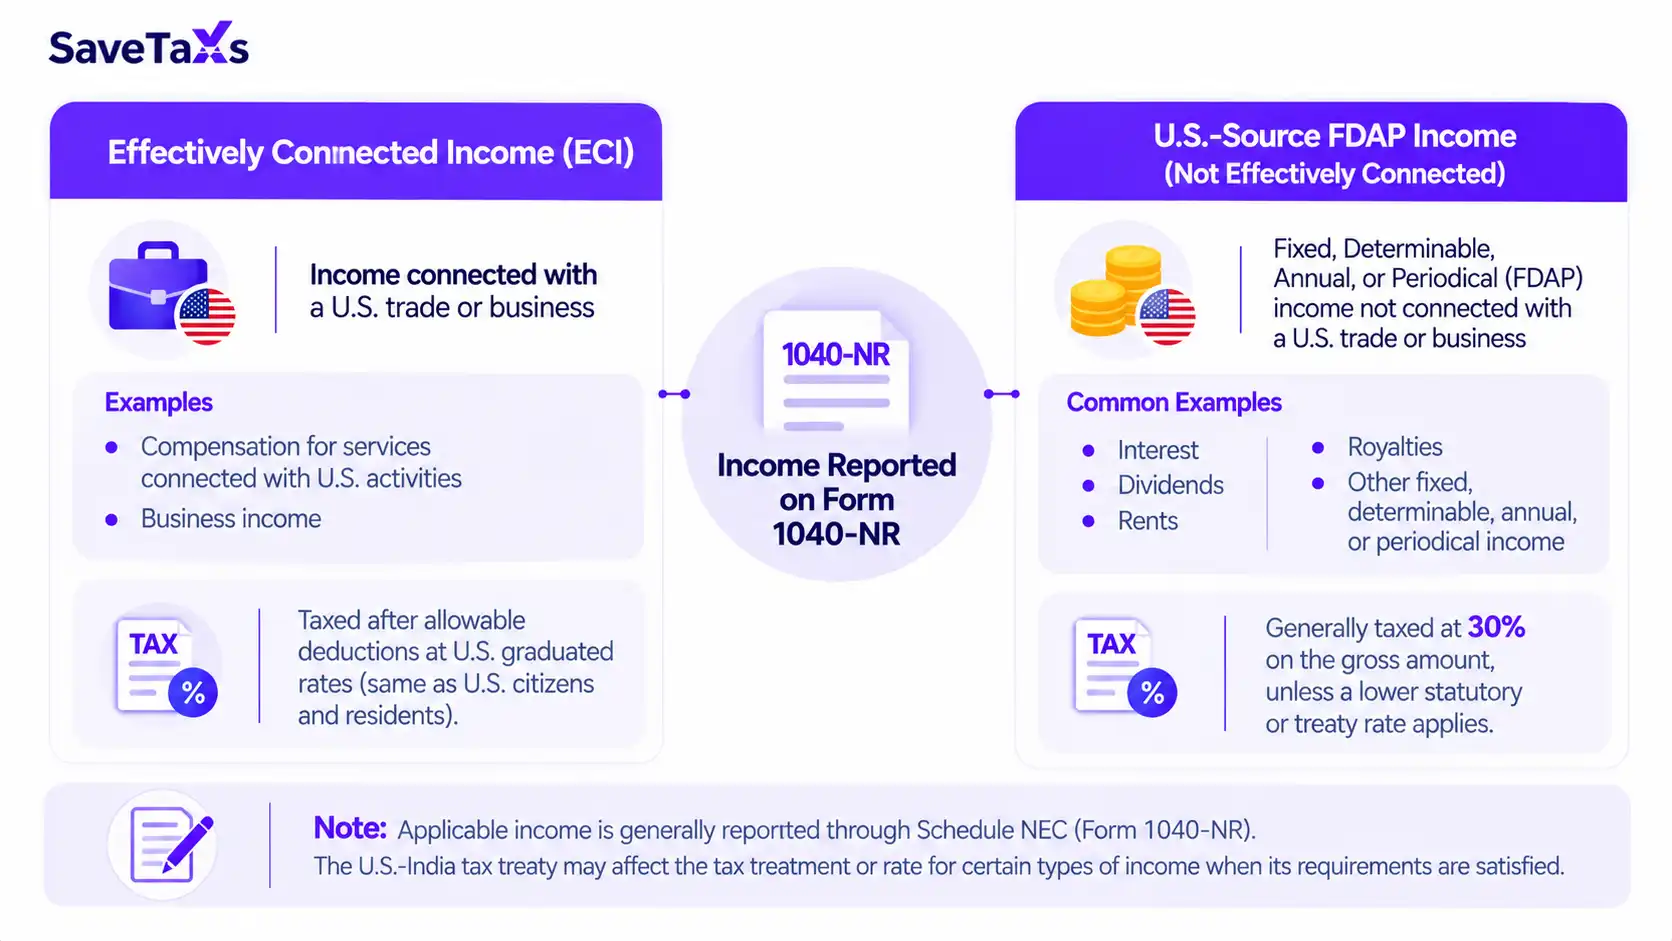
Effectively Connected Income, or ECI, generally refers to income that is effectively connected with the conduct of a trade or business in the United States.
ECI is generally taxed after allowable deductions at the graduated tax rates applicable to U.S. citizens and resident aliens.
Depending on the taxpayer's circumstances, ECI can include certain compensation for services or business income connected with U.S. activities.
The exact treatment depends on the source and nature of the income and the applicable nonresident-alien tax rules.
FDAP stands for Fixed, Determinable, Annual, or Periodical income.
Common examples can include certain:
U.S.-source FDAP income that is not effectively connected with a U.S. trade or business is generally taxed on the gross amount at 30%, unless a lower statutory or treaty rate applies.
Applicable income in this category is generally reported through Schedule NEC (Form 1040-NR).
For an Indian taxpayer, the U.S.-India income tax treaty may affect the tax treatment or rate for certain types of income when its requirements are satisfied. Treaty eligibility should therefore be checked based on the specific income and taxpayer circumstances rather than assuming that the standard 30% rate always applies.
Depending on your income and circumstances, additional schedules may need to accompany IRS Form 1040-NR.
Common Form 1040-NR schedules include:
| Schedule | General Purpose |
|---|---|
| Schedule A (Form 1040-NR) | Itemized deductions available to eligible nonresident aliens |
| Schedule NEC (Form 1040-NR) | Tax on income not effectively connected with a U.S. trade or business |
| Schedule OI (Form 1040-NR) | Other information relating to nationality, residence, visa status, treaty positions and related matters |
| Schedule P (Form 1040-NR) | Foreign partner's interests in certain partnerships transferred during the tax year |
Depending on the return, some numbered schedules associated with Form 1040 may also be required.
You do not need every schedule simply because you file Form 1040-NR. The schedules required depend on the type of income, deductions, taxes, credits, and other circumstances reported on your return.
The filing process begins with determining whether Form 1040-NR is actually the correct return.
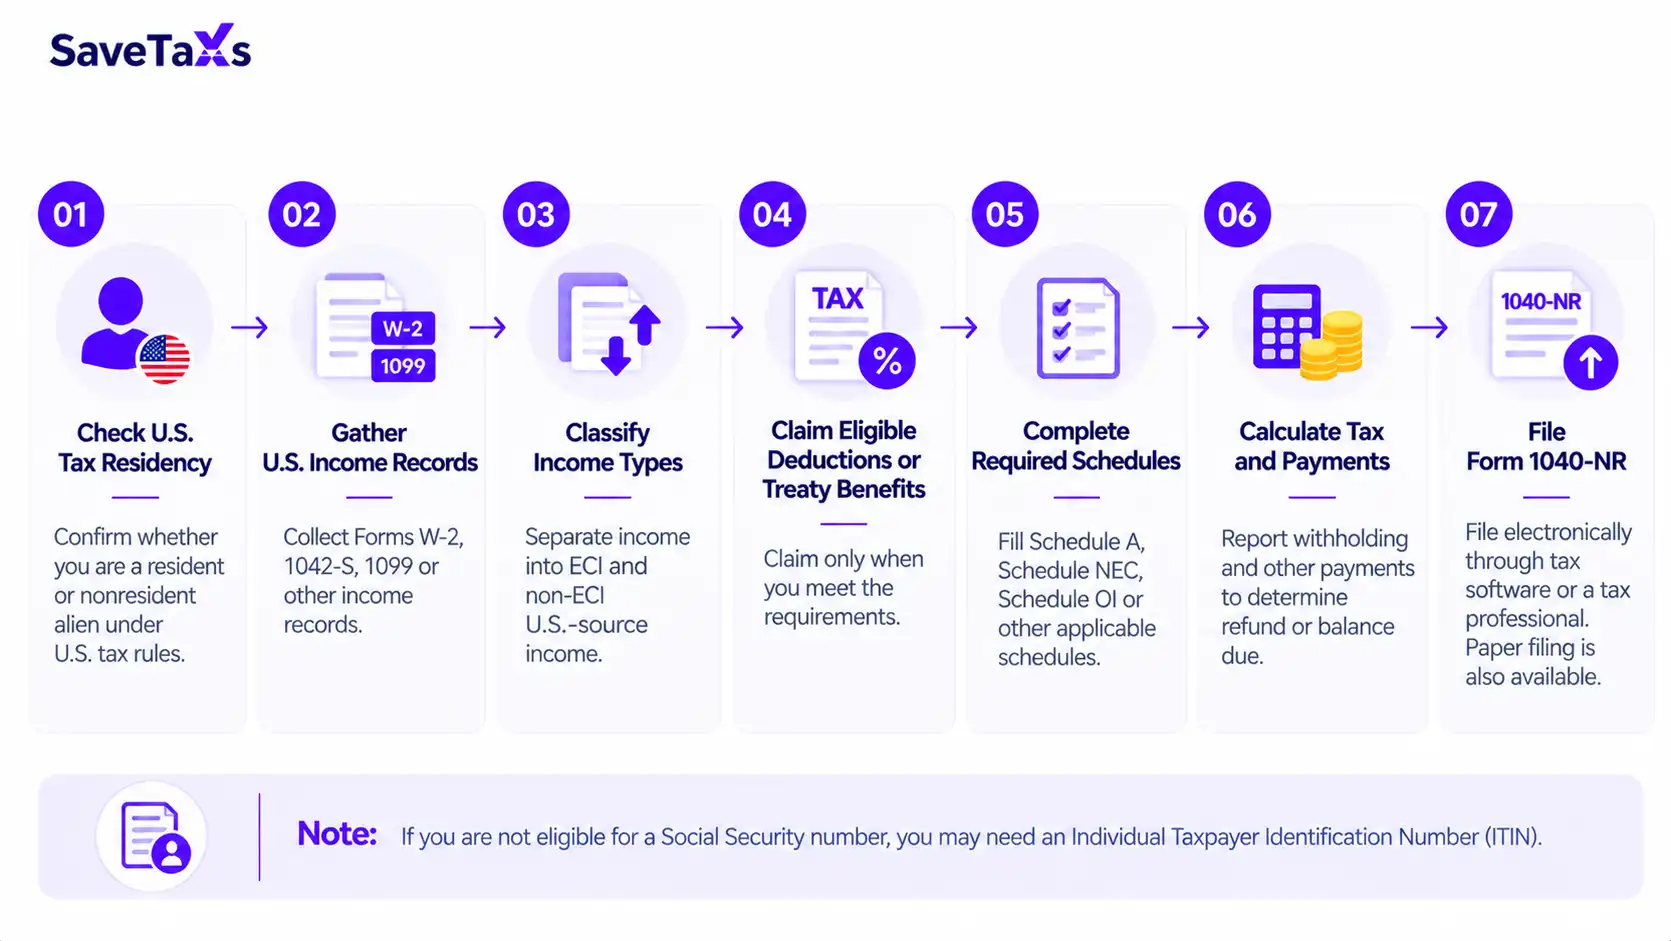
Check whether you are a resident or nonresident alien under U.S. tax rules. This may require considering the green card test, substantial presence test, applicable exceptions, and potentially a tax treaty.
Gather records relating to your U.S. income, such as applicable Forms W-2, 1042-S, 1099, partnership statements, or other income records.
Determine which income is effectively connected with a U.S. trade or business and which income is subject to the separate rules for non-effectively connected U.S.-source income.
This classification can materially affect how your income is taxed.
Nonresident aliens do not necessarily receive the same deductions and credits as U.S. residents.
Only claim a deduction, credit, exemption, or treaty benefit when you satisfy the relevant requirements.
Complete Schedule A, Schedule NEC, Schedule OI, or other applicable schedules based on your circumstances.
Report applicable withholding and other payments and determine whether you owe additional tax or are entitled to a refund.
The IRS allows Form 1040-NR to be filed electronically through supporting tax software or authorized tax professionals. Paper filing is also available.
A taxpayer who is not eligible for a Social Security number may need an Individual Taxpayer Identification Number (ITIN), subject to the applicable ITIN rules.
The Form 1040-NR deadline is not necessarily the same for every nonresident alien.
For a 2025 calendar-year return filed in 2026, the IRS instructions generally provide:
If you need additional time to file, you can generally request an automatic extension using Form 4868 by your applicable return due date.
However, an extension to file generally does not provide additional time to pay tax. Tax due should generally be paid by the original applicable deadline to reduce potential interest and penalties.
Special rules can apply in certain circumstances, so taxpayers should confirm their actual filing deadline rather than assuming that every Form 1040-NR is due April 15.
IRS Form 1040-NR is the primary U.S. individual income tax return for nonresident aliens who have a U.S. filing requirement.
For Indians and NRIs, the first step is determining U.S. tax residency. Your NRI status under Indian law does not automatically determine whether you should file Form 1040 or Form 1040-NR.
If you are a nonresident alien, the next step is determining whether you have a filing requirement and properly classifying your U.S. income. In particular, understanding the difference between Effectively Connected Income and non-effectively connected U.S.-source income is important because the tax treatment can differ substantially.
Finally, check the deadline that applies to your specific situation. Depending on whether you received wages subject to U.S. income tax withholding or had an office or place of business in the United States, a calendar-year Form 1040-NR may generally be due April 15 or June 15.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio

Want to read more? Explore Blogs