US Tax Filing and Compliance
Is an S Corporation Worth It? Costs, Tax Benefits and Decision ChecklistIs an S Corporation Worth It? Costs, Tax Benefits and Decision Checklist
Written by Shubham Jain

U.S. federal income tax rules for 2025 include inflation-adjusted tax brackets and changes introduced by the One Big Beautiful Bill Act (OBBBA), enacted on July 4, 2025. These changes affect deductions, certain tax credits, and the amount of income that may be subject to federal income tax.
If you are preparing your 2025 US tax return in 2026, understanding the updated US tax brackets 2025, standard deduction, and new deduction rules can help you estimate your taxable income and identify potential tax benefits.
This guide covers federal individual income tax rules for tax year 2025. State income taxes and individual eligibility requirements may differ.
The One Big Beautiful Bill Act introduced several changes relevant to individual tax returns for 2025. Some provisions apply to income earned from January 1, 2025, even though the legislation was enacted during the year.
| Tax provision | 2025 update |
|---|---|
| Federal income tax rates | Seven marginal rates remain in place |
| Standard deduction | Increased to $15,750 for single and married filing separately; $31,500 for joint filers; $23,625 for heads of household |
| Qualified tips | Eligible taxpayers may deduct up to $25,000, subject to qualifying occupation, reporting, income and other requirements (2025–2028 only) |
| Qualified overtime | Eligible taxpayers may deduct up to $12,500, or $25,000 for joint filers, subject to qualifying compensation and other requirements (2025–2028 only) |
| Passenger vehicle loan interest | Eligible taxpayers may deduct up to $10,000, subject to vehicle, loan, income and other requirements (2025–2028 only) |
| Additional deduction for seniors | Eligible taxpayers aged 65 or older may qualify for up to $6,000 per person, subject to income and other requirements (2025–2028 only) |
| State and local taxes | Maximum SALT deduction increased to $40,000 for most eligible filers for 2025–2029 (reverts to $10,000 in 2030), subject to phaseouts; the limit is generally $20,000 for married filing separately |
These provisions have detailed eligibility rules, income phaseouts, and other restrictions. The phrase "no tax" in descriptions of tips or overtime does not mean that all of a worker's income is exempt from tax.
Get help navigating US tax brackets, deductions, and filing requirements.
The United States uses a progressive federal income tax system. Different portions of taxable income are taxed at different rates. Reaching a higher bracket does not mean all your income is taxed at that higher rate.
The following are the 2025 federal ordinary income tax brackets. Amounts are in U.S. dollars and refer to taxable income.
| Tax rate | Single | Married filing jointly | Married filing separately | Head of household |
|---|---|---|---|---|
| 10% | 0–11,925 | 0–23,850 | 0–11,925 | 0–17,000 |
| 12% | 11,926–48,475 | 23,851–96,950 | 11,926–48,475 | 17,001–64,850 |
| 22% | 48,476–103,350 | 96,951–206,700 | 48,476–103,350 | 64,851–103,350 |
| 24% | 103,351–197,300 | 206,701–394,600 | 103,351–197,300 | 103,351–197,300 |
| 32% | 197,301–250,525 | 394,601–501,050 | 197,301–250,525 | 197,301–250,500 |
| 35% | 250,526–626,350 | 501,051–751,600 | 250,526–375,800 | 250,501–626,350 |
| 37% | Over $626,350 | Over $751,600 | Over $375,800 | Over $626,350 |
How the brackets work: Suppose a single filer has $60,000 in taxable income. The first $11,925 falls into the 10% bracket, the next portion is taxed at 12%, and only the taxable income above $48,475 falls into the 22% bracket. The entire $60,000 is not taxed at 22%.
Note: These are the official 2025 federal ordinary income tax bracket thresholds. Use the applicable IRS tax rate schedules and instructions when calculating the actual tax due.
The standard deduction reduces income before federal income tax is calculated. Most eligible taxpayers can claim the standard deduction or itemize eligible deductions, depending on their filing circumstances. Nonresident aliens generally cannot claim the standard deduction, except for certain eligible students and business apprentices from India under Article 21(2) of the U.S. India Income Tax Treaty, provided they do not claim itemized deductions.
The updated 2025 amounts are:
| Filing status | Standard deduction |
|---|---|
| Single | $15,750 |
| Married filing jointly | $31,500 |
| Married filing separately | $15,750 |
| Head of household | $23,625 |
Suppose a single taxpayer has $70,000 in adjusted gross income (AGI) before the standard deduction and no other adjustments or deductions. If the taxpayer qualifies for the $15,750 standard deduction, the calculation begins with:
This is a simplified illustration, not a final tax calculation. Actual adjusted gross income, other deductions, tax credits, and special rules can change the result.
The OBBBA, enacted on July 4, 2025, created four new temporary deductions for eligible individuals, available for tax years 2025 through 2028 only. Some may be claimed even when the taxpayer takes the standard deduction rather than itemizing, but the specific requirements still apply. Eligible taxpayers generally claim these four new deductions using Schedule 1-A with their applicable 2025 federal income tax return.
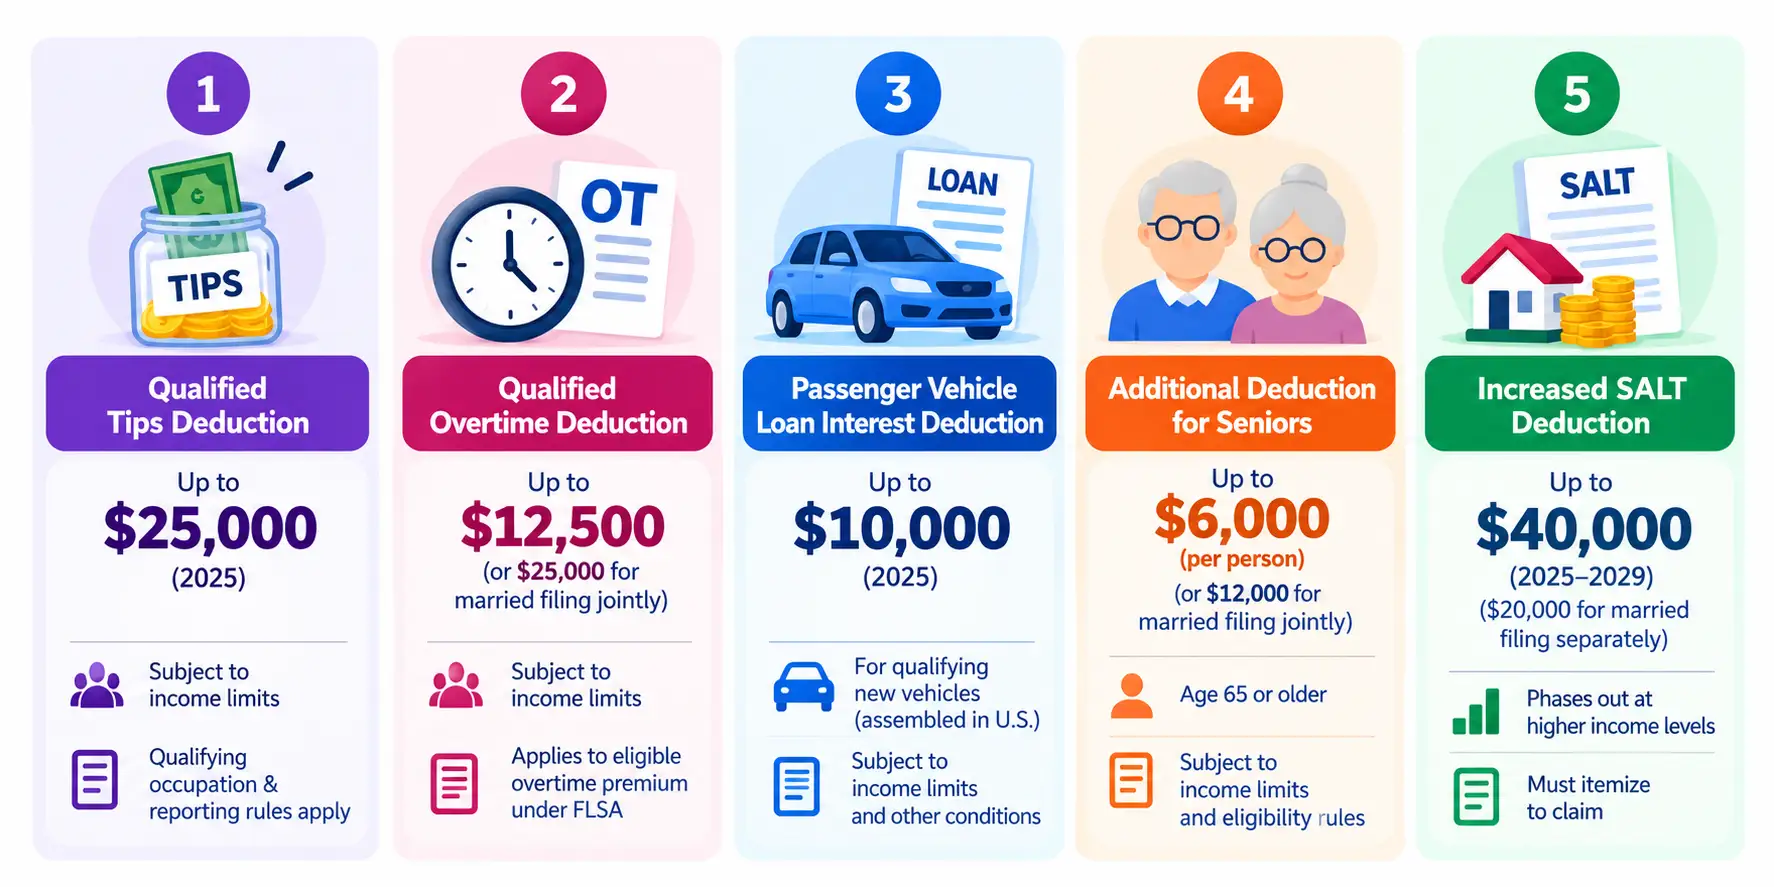
Eligible workers may deduct up to $25,000 in qualified tips for 2025. The deduction is subject to income limits, qualifying occupation and reporting requirements, and valid Social Security number requirements. The deduction phases out when modified adjusted gross income (MAGI) exceeds $150,000, or $300,000 for married taxpayers filing jointly. Married taxpayers generally must file jointly to claim this deduction.
It does not make every service charge, commission, or payment received by a worker a qualifying tip. Check the IRS requirements before claiming it.
Eligible workers may deduct up to $12,500 in qualified overtime compensation, or up to $25,000 for married taxpayers filing jointly. Married taxpayers generally must file jointly to claim this deduction.
The deduction generally applies to the qualifying overtime premium required under the Fair Labor Standards Act, not necessarily every payment labelled as overtime by an employer. Income limits and other eligibility conditions apply. The deduction phases out when MAGI exceeds $150,000, or $300,000 for married taxpayers filing jointly.
Eligible taxpayers may deduct up to $10,000 in qualifying interest on a passenger vehicle loan for a vehicle purchased for personal use. The loan must generally have originated after December 31, 2024, be secured by a first lien on the vehicle, and meet the applicable security requirements. The vehicle must be a qualifying new vehicle whose original use begins with the taxpayer and whose final assembly takes place in the United States. The deduction is subject to income-based phaseouts. Nonresident aliens are generally not eligible for this deduction.
Interest on every car loan does not automatically qualify. Taxpayers should confirm the vehicle, loan, purchase date, and documentation requirements. The deduction generally phases out when MAGI exceeds $100,000, or $200,000 for married taxpayers filing jointly. Lease payments do not qualify.
Eligible taxpayers aged 65 or older may qualify for an additional deduction of up to $6,000 per person. A qualifying married couple, where both spouses are aged 65 or older, may be eligible for up to $12,000 combined.
This is separate from the existing additional standard deduction for age or blindness. The new deduction has income limits and eligibility conditions, including Social Security number requirements. The deduction phases out at a rate of 6% of MAGI in excess of $75,000 for single filers (or $150,000 for married filing jointly), and is fully eliminated when MAGI reaches $175,000 for single filers or $350,000 for married filing jointly. Married taxpayers generally must file jointly to claim this deduction.
The SALT deduction cap increased to 40,000formosteligibletaxpayersfortaxyears2025through2029(20,000 for married filing separately), with a 1% annual increase through 2029. Starting in 2030, the cap permanently reverts to $10,000. For 2025, the deduction phases out at a rate of 30% of MAGI in excess of $500,000 (or $250,000 for married filing separately), but generally cannot fall below $10,000, or $5,000 for married filing separately.
SALT generally covers qualifying state and local income or sales taxes and property taxes. Taxpayers must itemize to claim the SALT deduction.
The new provisions are only part of the U.S. tax system. Depending on eligibility, other deductions and credits may reduce taxable income or the tax owed.
A deduction reduces taxable income, while a tax credit generally reduces tax owed directly. Neither should be claimed without confirming the relevant eligibility rules and required records.
For authoritative eligibility rules and forms, consult the IRS's 2025 tax guidance.
NRIs should not assume that U.S. tax deductions apply merely because they have U.S.-source income or a U.S. bank account. The first step is determining whether the person is a U.S. citizen, resident alien, nonresident alien, or dual-status taxpayer under the relevant rules.
For example, an Indian citizen working in the United States may need to determine U.S. tax residency and filing status before deciding which 2025 deductions are available. Their Indian tax residency and any India-side reporting obligations are separate questions.
For related guidance, review SaveTaxs resources on Form 1040, Form 1040-NR, and the Foreign Tax Credit. Eligibility depends on the taxpayer's specific circumstances.
Understand your cross-border tax obligations with expert guidance.
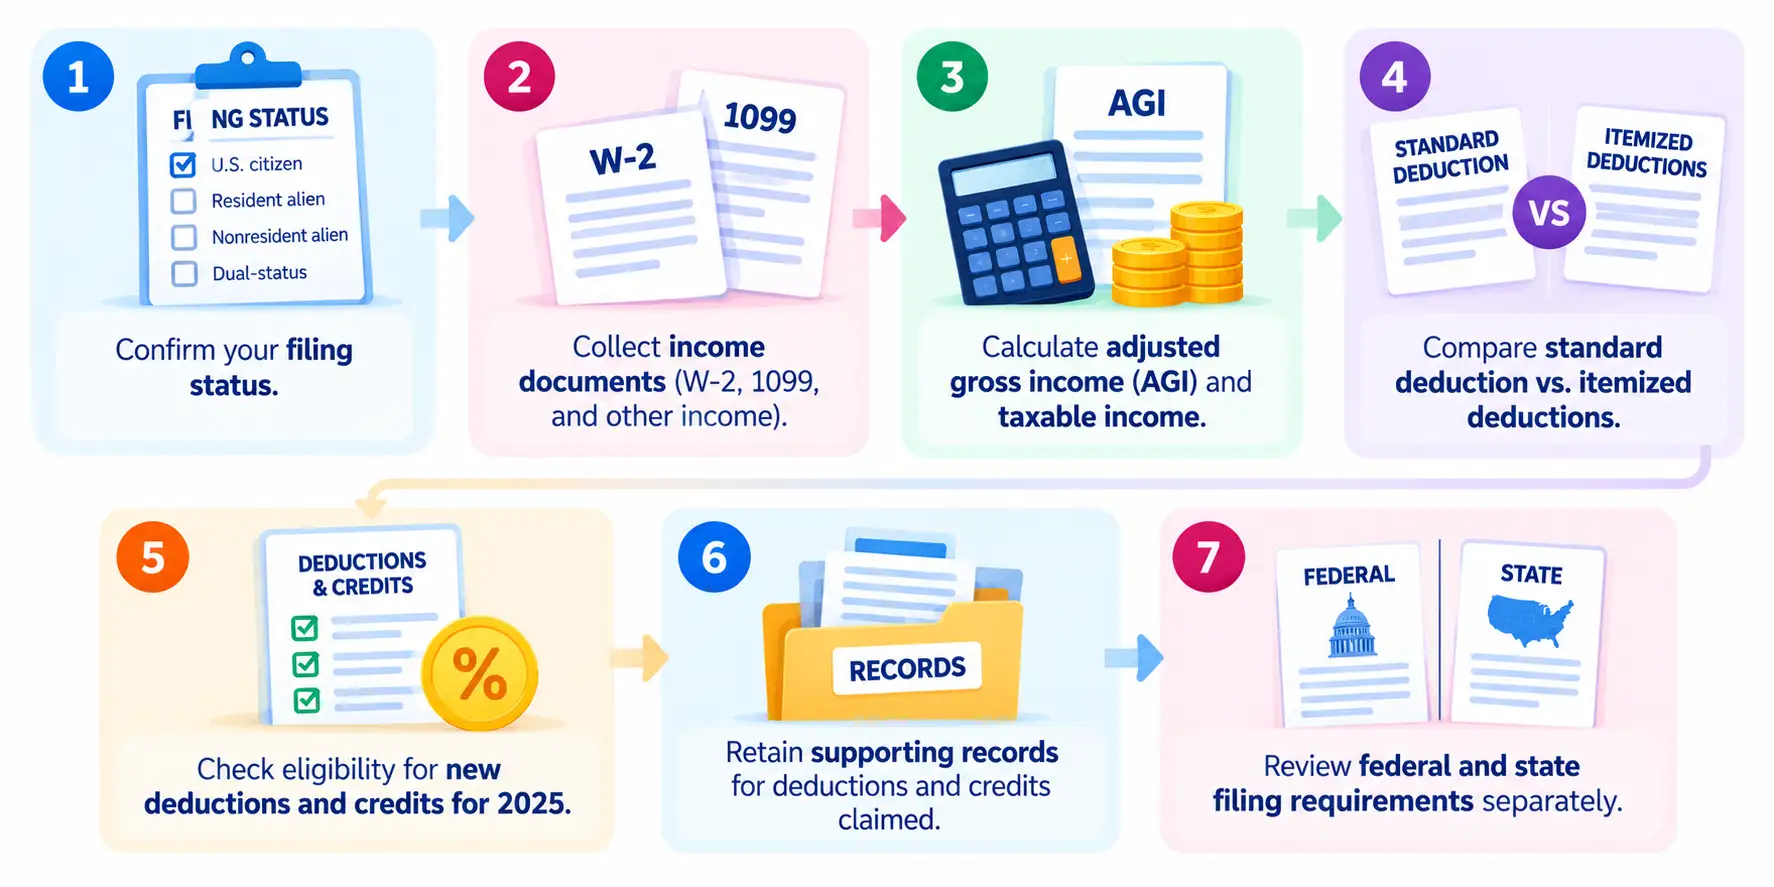
Use this checklist before filing:
The IRS advises taxpayers to maintain records supporting deductions and to use official guidance when checking eligibility.
Understanding the 2025 US tax brackets and deductions can help you prepare your return more accurately, but the correct result depends on your income, filing status, and eligibility for each tax benefit.
SaveTaxs can help eligible taxpayers and NRIs understand U.S. tax filing requirements and navigate cross-border tax considerations based on their circumstances.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio

Want to read more? Explore Blogs