US Tax Filing and Compliance
How to Report Multiple 1099 Forms on a U.S. Tax Return: A Guide for NRIsHow to Report Multiple 1099 Forms on a U.S. Tax Return: A Guide for NRIs
Written by Hatim Dudhiyawala
If your S Corporation cannot complete its federal income tax return by the original filing deadline, you can request additional time from the IRS using Form 7004. This form allows eligible S Corporations to obtain an automatic extension to file Form 1120-S without submitting a detailed explanation for the delay.
However, requesting an extension does not remove your tax payment obligations or extend the deadlines for other business tax filings. You must complete Form 7004 correctly, submit it by the original return deadline, and pay any applicable tax due on time.
This guide explains how to file Form 7004 for an S Corporation, the information required, important deadlines, and what happens after submitting the extension request.
An S Corporation needs to file Form 7004 when it cannot complete and submit its Form 1120-S by the original filing deadline and needs additional time to prepare an accurate return.
For example, an S Corporation may need an extension because:
Form 7004 allows an eligible S Corporation to request an automatic extension without explaining why it needs more time.
The extension applies specifically to the Form 1120-S return identified in the application. It does not automatically extend every other federal tax filing obligation of the business.
Get assistance with Form 7004, Form 1120-S filing deadlines, and S Corporation tax compliance.
An S Corporation must generally file Form 7004 by the original due date of its Form 1120-S return.
For a calendar-year S Corporation, the original filing deadline is generally March 15 of the following year. If the deadline falls on a Saturday, Sunday, or legal holiday, the deadline moves to the next business day.
For example:
| Filing requirement | General deadline |
|---|---|
| Original Form 1120-S deadline | March 15 |
| Form 7004 extension request | By the original Form 1120-S deadline |
| Extended Form 1120-S deadline | September 15 |
These dates apply to the standard calendar-year filing situation. Fiscal-year and short-tax-year S Corporations must calculate their deadlines based on their applicable tax year.
Important: Do not wait until the extended deadline to submit Form 7004. You must generally submit the extension request by the original return deadline.
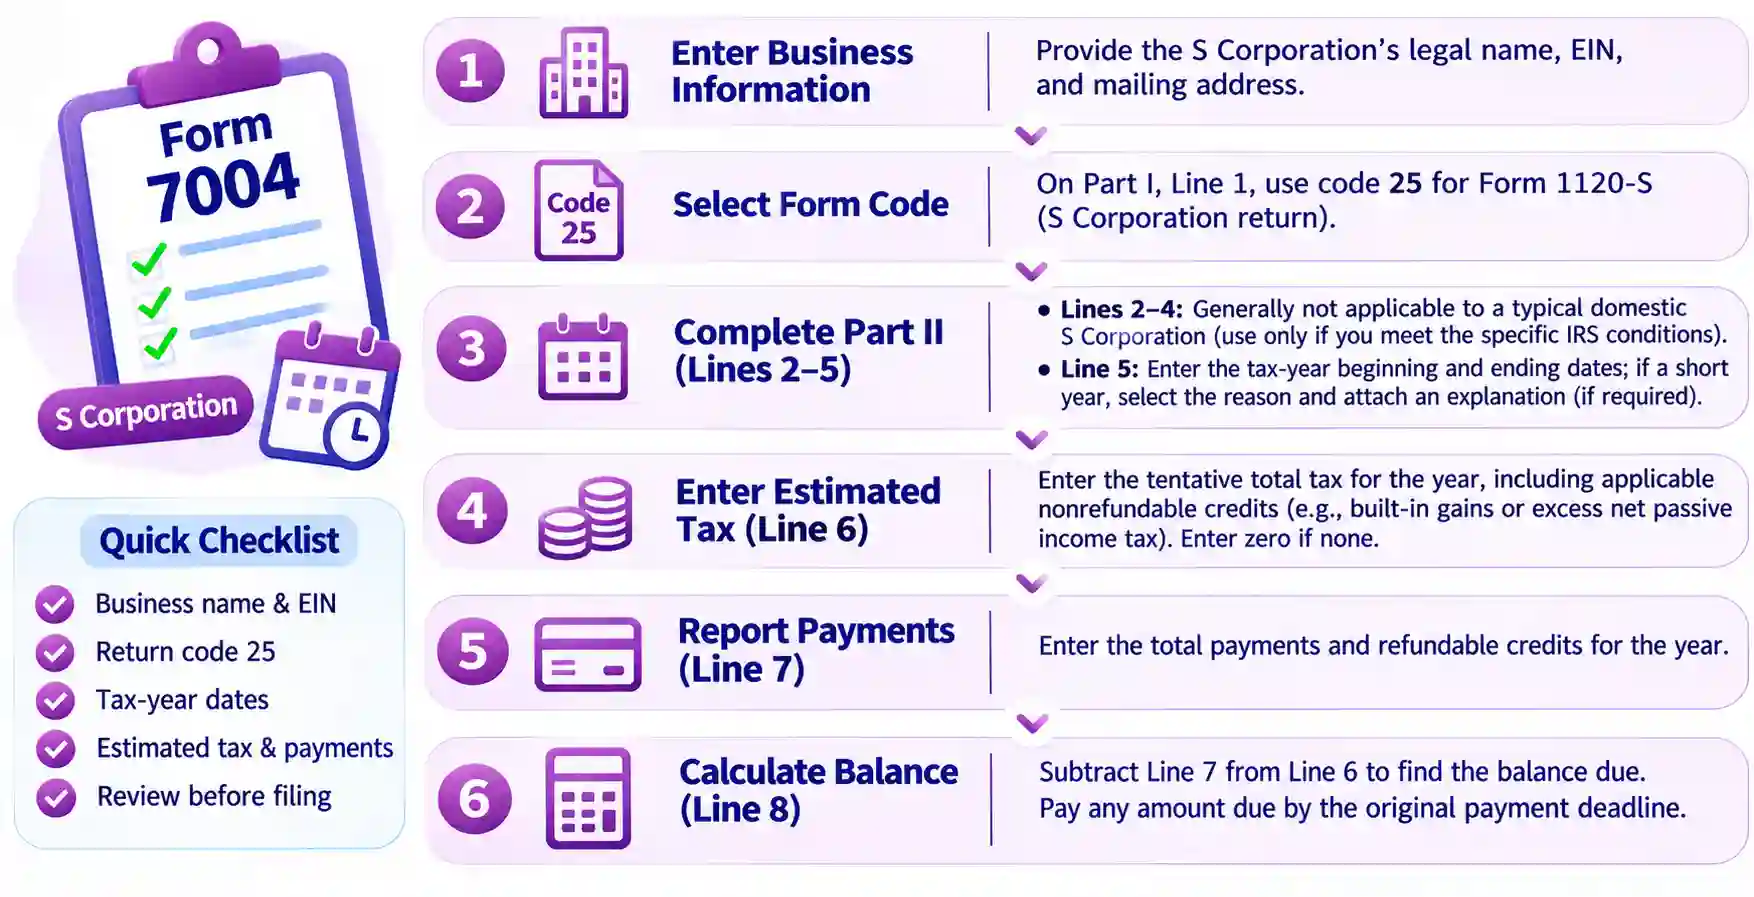
An S Corporation must provide its identifying information, select the correct return code, enter the applicable tax-year details, and report its estimated tax and payments when completing Form 7004.
Before starting, keep the following information ready:
At the top of Form 7004, enter the S Corporation's:
Make sure the business name and EIN match the IRS records. Incorrect identifying information can affect the validity of the extension request.
On Part I, Line 1, select the form code corresponding to the return for which you are requesting an extension.
For an S Corporation filing Form 1120-S, the correct Form 7004 code is 25.
Selecting the correct code is important because the extension applies only to the specific return identified in the application.
Part II contains additional information about the organization and its tax year.
For a typical domestic S Corporation:
Do not check special-rule boxes simply because the business operates internationally. The corporation must meet the specific IRS eligibility conditions.
On Line 6, enter the tentative total tax the S Corporation expects to owe for the tax year, including applicable nonrefundable credits.
An S Corporation generally passes its income and deductions through to shareholders. However, certain S Corporations may have entity-level federal tax liabilities, such as built-in gains tax or excess net passive income tax.
If the expected amount is zero, enter zero as directed by the IRS instructions.
On Line 7, enter the total payments and refundable credits applicable to the estimated tax calculation.
Use the relevant tax records and applicable return instructions to determine the correct amount.
Subtract Line 7 from Line 6 to calculate the balance due.
If the S Corporation has an unpaid tax liability, it should pay the amount by the original payment deadline.
The IRS does not require a signature on Form 7004.
Before submitting: Review the business name, EIN, return code, tax-year dates, and tax calculations to reduce the risk of an invalid extension request.
An S Corporation can generally submit Form 7004 electronically or through paper filing.
Electronic filing
Electronic filing is generally the convenient option. An S Corporation can use an IRS-authorized e-file provider or compatible tax preparation software to submit its extension request.
Follow the provider's instructions and retain the electronic submission acknowledgement for your records.
Paper filing
If submitting Form 7004 by mail:
The applicable mailing address can depend on the corporation's location and other filing details.
Important: The IRS cautions that when an S Corporation submits Form 7004 on paper but later files Form 1120-S electronically, the return may be processed before the extension is granted. This can result in a penalty notice. Electronic filing of both documents, where available, can help avoid this processing issue.
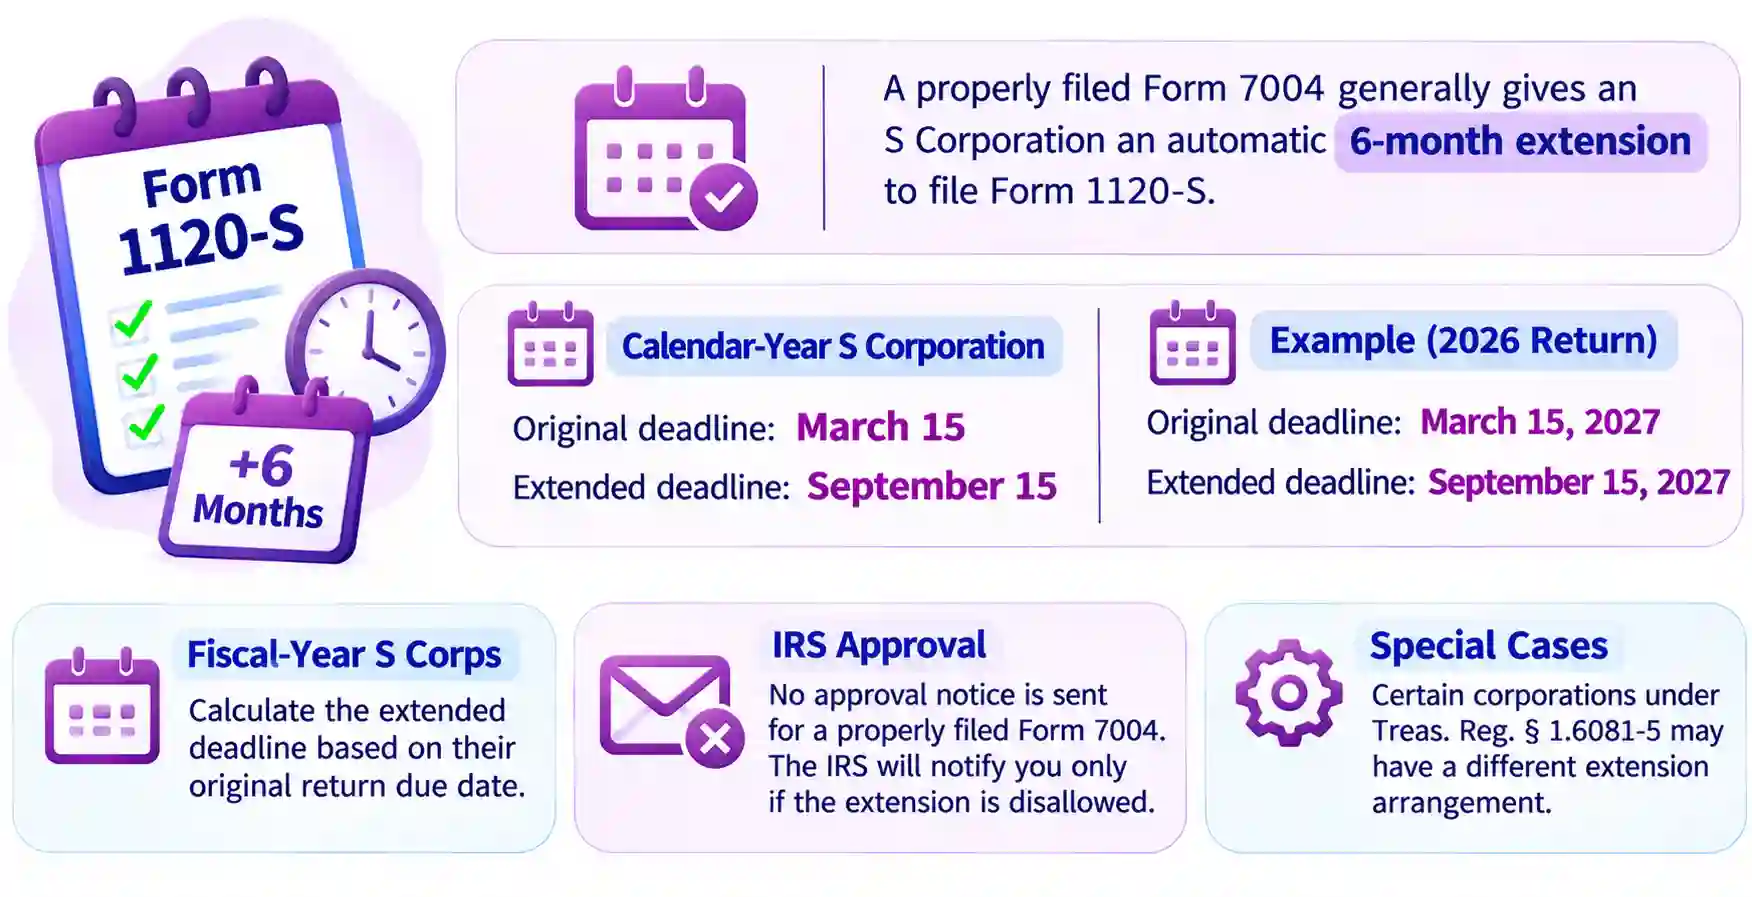
A properly filed Form 7004 generally gives an S Corporation an automatic six-month extension to file its Form 1120-S.
For a calendar-year S Corporation:
For example, an S Corporation filing its 2026 calendar-year return generally has an original deadline of March 15, 2027. A valid six-month extension generally moves its filing deadline to September 15, 2027.
Fiscal-year S Corporations must calculate the extended deadline based on their original return due date.
The IRS generally does not send an approval notification for a properly filed Form 7004. It will notify the corporation if the extension request is disallowed.
Certain corporations qualifying under special rules in Treasury Regulation Section 1.6081-5 may have a different extension arrangement. These exceptions should be evaluated separately.
If an S Corporation does not submit Form 7004 by the original Form 1120-S deadline, it may not receive a valid automatic extension.
In that situation, the corporation should:
The IRS generally imposes a late-filing penalty on an S Corporation for each month or part of a month the return remains late, based on the applicable penalty rules and number of shareholders.
A late extension request does not automatically eliminate penalties for an overdue return.
Yes. When an S Corporation obtains a valid extension for Form 1120-S, the extended filing timeline also affects when it must provide Schedule K-1 information to its shareholders.
An S Corporation generally must provide Schedule K-1 to each shareholder by the date its Form 1120-S is required to be filed, including applicable extensions.
However, the corporate extension does not automatically extend the shareholders' individual federal income tax return deadlines.
Shareholders who are waiting for Schedule K-1 information should consider whether they need to request an individual tax extension using the applicable individual filing procedure.
The S Corporation should also communicate the expected Schedule K-1 delivery date to its shareholders so they can plan their individual tax filings.
Get help completing Form 7004, understanding extension deadlines, and avoiding late filing issues.
An S Corporation can use Form 7004 to obtain additional time to file its annual Form 1120-S return. However, the corporation must submit the extension request by the original filing deadline, use the correct return code, and meet the applicable tax payment requirements.
Errors in the extension request, missed deadlines, or incorrect tax calculations can create unnecessary compliance problems.
Savetaxs helps U.S. business owners understand their federal tax filing requirements, extension obligations, and business tax compliance needs. With professional guidance, S Corporation owners can organize their filing information, address extension requirements, and manage their tax responsibilities more effectively.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Hatim Dudhiyawala is a Certified Public Accountant (CPA) with SaveTaxs and specializes in Indian and NRI taxation. He advises individuals, NRIs, and businesses on income tax filing, capital gains taxation, DTAA benefits, fund repatriation, and tax compliance. With experience in cross-border tax matters, Hatim helps taxpayers understand complex regulations and make informed decisions. Through his articles, he shares practical insights to help readers stay compliant and manage their tax obligations with confidence. See Full Bio

Want to read more? Explore Blogs