US Tax Filing and Compliance
Is an S Corporation Worth It? Costs, Tax Benefits and Decision ChecklistIs an S Corporation Worth It? Costs, Tax Benefits and Decision Checklist
Written by Shubham Jain

An S corporation is one of the most popular structural choices for small-to-midsize businesses seeking to benefit from a U.S. corporation. It is not a separate legal entity and is elected under Subchapter S of the Internal Revenue Code. It offers a hybrid structure that combines a corporation's limited liability with a partnership's pass-through taxation.
Under it, businesses generally aren't subject to regular federal corporate income tax; profits pass through to shareholders, who pay tax when filing their returns. However, certain federal and state taxes may still apply. Not everyone can elect S corporation status; you must meet certain requirements.
Want to know more about an S corp, its requirements, taxation, and how it works? Then you are on the right page. Scroll down and gather all the information associated with an S corporation.
An S corporation is a popular business structure in the U.S. elected under Subchapter S of the Internal Revenue Code. This tax status is available to eligible domestic corporations and certain other eligible domestic entities, including LLCs that qualify for and elect corporate tax treatment. Under it, the business itself remains the LLC or corporation; the status only changes the tax obligations. An S corp provides a hybrid structure combining the limited liability of a corporation with the pass-through taxation of a partnership.
Under pass-through taxation, the business itself generally does not pay regular federal corporate income taxes. Instead, the shareholders report their share of business profit or income on their personal tax returns and pay tax at individual rates. This generally avoids double taxation on corporate income, although certain entity-level taxes may apply.
Further, an S corporation is not a separate legal entity like a company. The IRS describes it as a corporation that passes corporate income, profits, losses, deductions, and credits through to shareholders for federal tax purposes.
This was all about an S corporation. Next, let's look at the requirements and eligibility for forming one.
Under IRS §1361, the IRS sets specific criteria you must meet to form an S corporation. Miss one and you may not qualify for S corp status. Common eligibility requirements for an S corporation include:
At Savetaxs, we help U.S. taxpayers understand their tax obligations and pay them on time, accurately.
Here is all about who generally cannot be an S corp shareholder:
An eligible LLC may itself elect S corporation status if it meets the IRS requirements.
Additionally, eligibility for an S corporation is not checked only once. For instance, if a shareholder inadvertently transfers their interest to an ineligible individual, or dies and their interest passes to a trust that does not qualify, the S corp election may terminate. However, certain qualifying trusts are permitted to hold S corporation shares.
Generally, an S corporation cannot have more than 100 shareholders. Special family aggregation rules can affect how to count shareholders for this purpose. Additionally, an S corp has only one class of stock. The IRS states that outstanding shares should offer identical rights to shareholders for distribution and liquidation proceeds, although differences in voting rights may be permitted.
So, this covered the S corporation eligibility requirements. Moving forward, let's learn how this corporation is taxed.
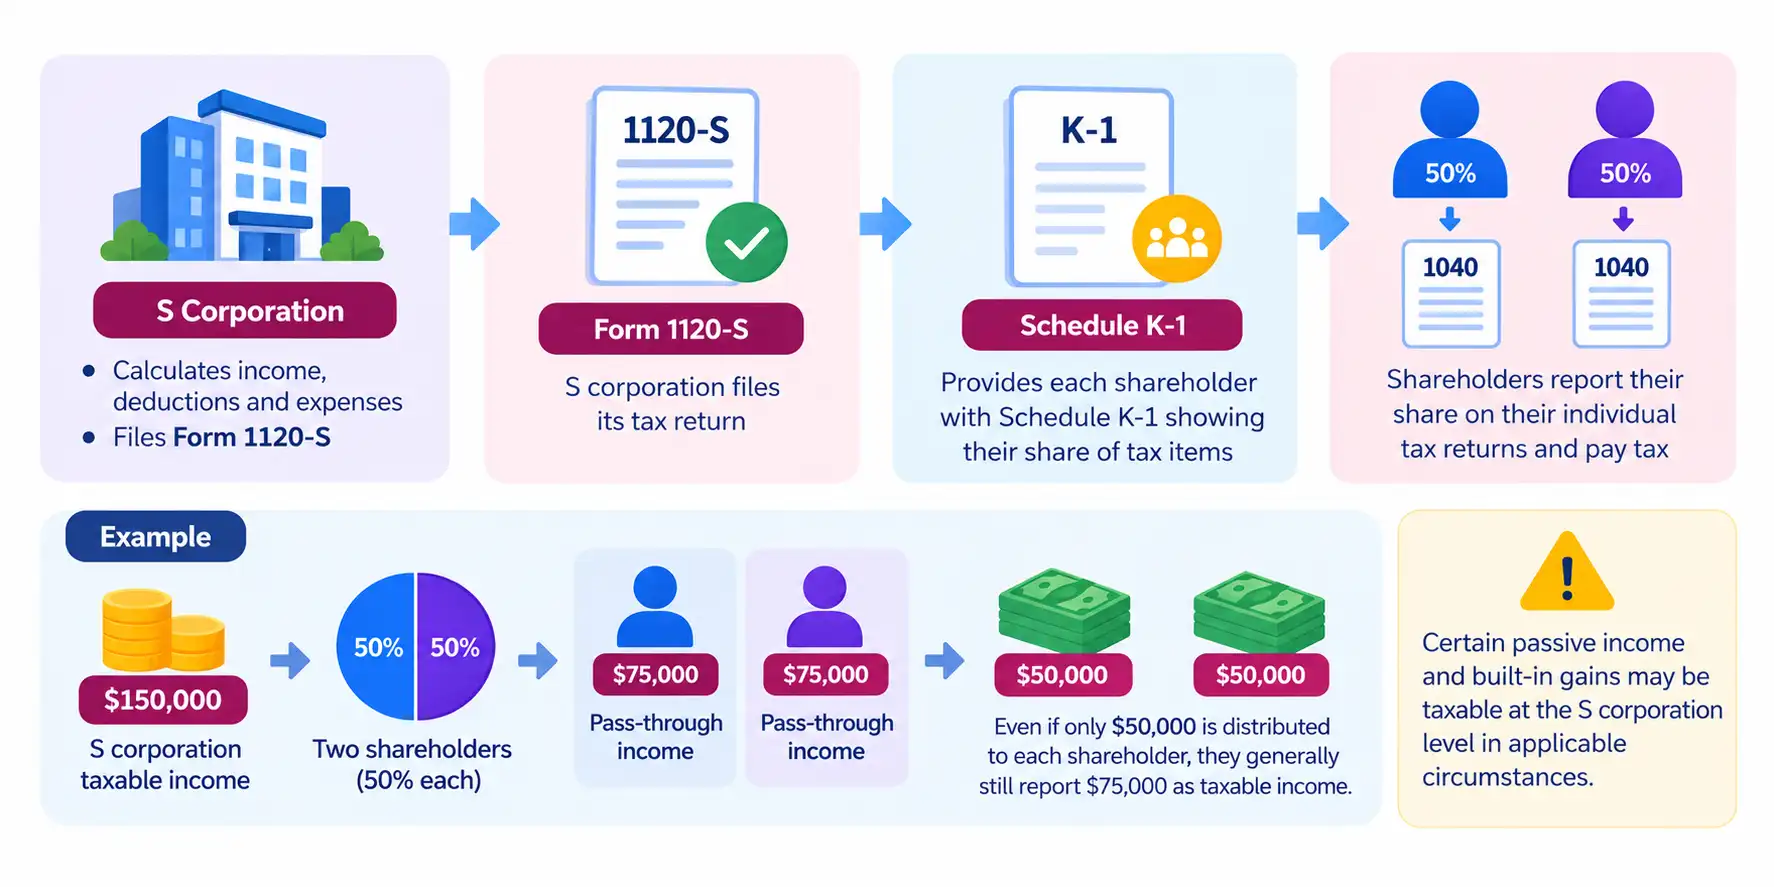
As mentioned earlier, an S corporation for federal tax purposes operates as a pass-through entity. As a result, the business calculates its income, deductions, expenses, and other relevant items and files a tax return using Form 1120-S.
After that, generally, the relevant tax items pass through to shareholders based on their ownership interest. The company provides each shareholder with Schedule K-1. The schedule reflects their share in specified S corporation tax items. Then the shareholders report those items in their individual tax returns and pay tax on them. They generally must report their allocated share of taxable income even if they do not receive that amount in cash. The tax treatment of actual distributions depends on the applicable rules, including the shareholder's stock basis.
However, the S corporation itself is not completely exempt from the federal tax system. In applicable circumstances, certain passive income and built-in gains are taxable at the entity level. To better understand how an S corporation works, let's look at an example.
For instance, after allowable wages and deductible expenses, an S corporation has around $150,000 taxable business income. Under this, two shareholders own 50% each. Subject to the applicable rules, each receives $75,000 in pass-through income.
However, if the corporation distributes only $50,000 in cash to each shareholder, that does not limit their taxable income from the corporation to $50,000.
If you are a shareholder in the S corporation and perform substantial services for the business, generally you are considered an employee of the corporation. This means the corporation pays you wages through payroll. Additionally, like other employees, your salary from the corporation will also be reported on Form W-2.
As a shareholder, you receive a distribution when the S corporation transfers property or money to you because you have an ownership interest.
Now, suppose you are an owner in the S corporation and work full-time in the business. The business generates $150,000 before paying you compensation. Here, you cannot simply state that you will pay yourself $5,000 as salary and take the remaining amount as a distribution to avoid payroll taxes.
Based on the services you performed, you need to determine a reasonable salary. For this, you can use the relevant considerations:
There is no universal percentage to calculate a reasonable salary that works for every S corporation. Now, moving ahead, let's look at how to elect S corporation status.
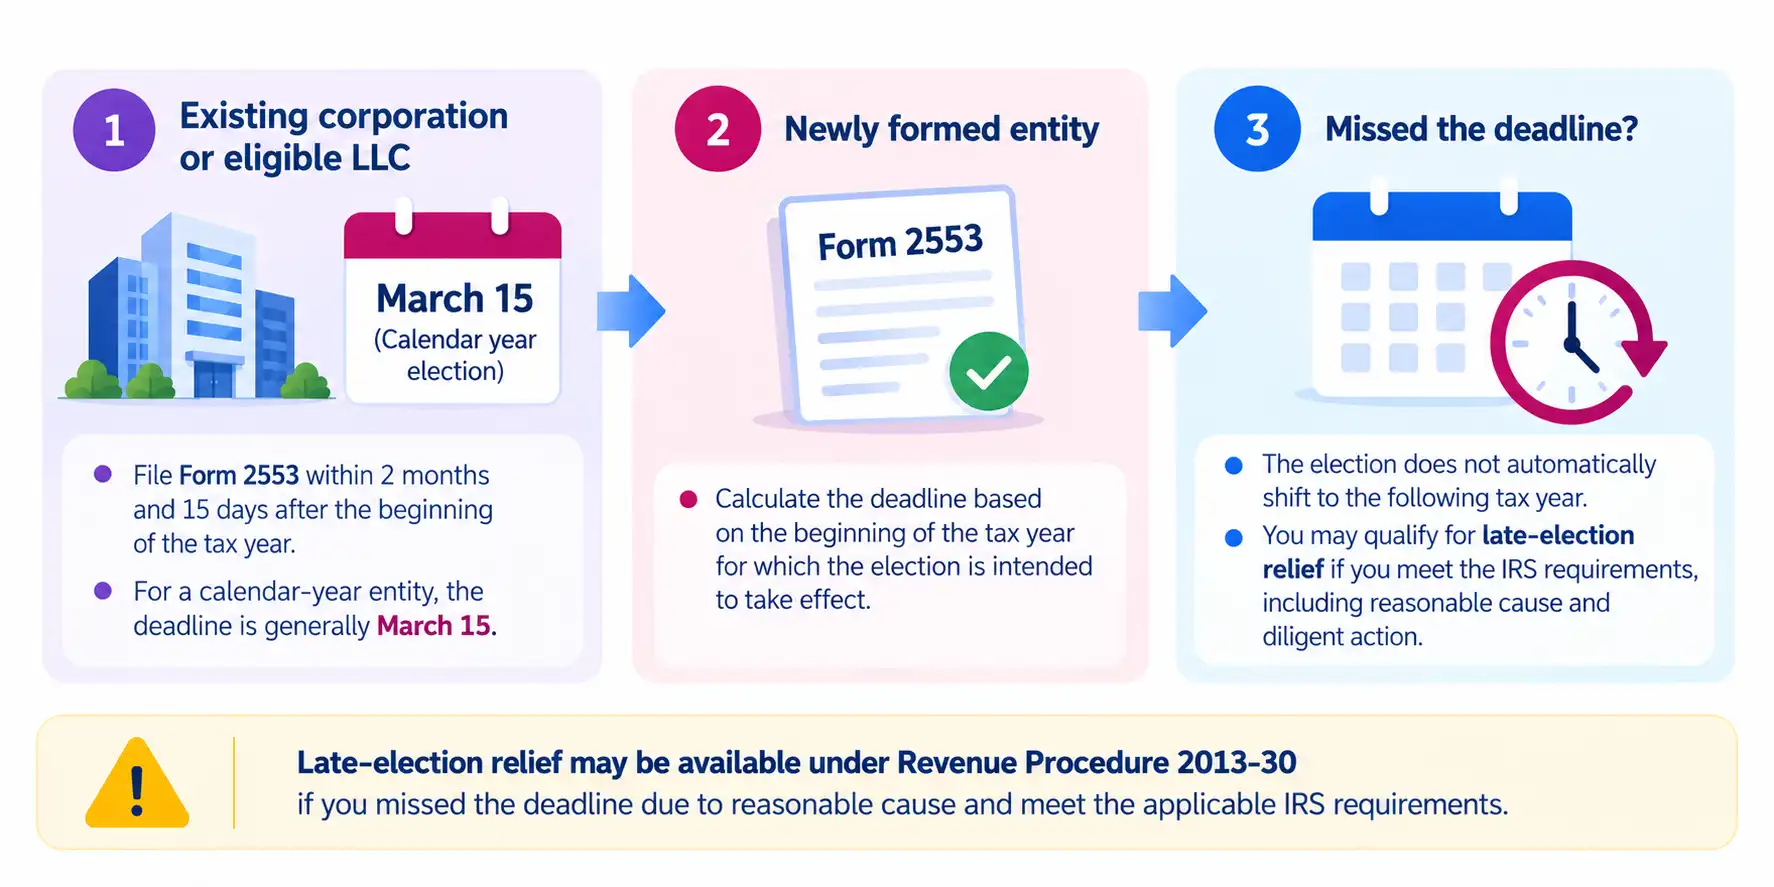
Here is how you can elect S corporation status:
Here is what you should consider when filing Form 2553:
So, this is how you can elect S corp status. Now, moving forward, let's look at the compliance requirements after obtaining this status.
You need to fulfill the following compliance requirements after electing S corp status:
These are the compliance requirements you must follow after gaining S corporation status. Moving further, let's know the advantages and disadvantages of forming this entity.
An S corporation offers several benefits to its owners; however, it may not suit every business. With that in mind, let's look at the S corporation's advantages and disadvantages.
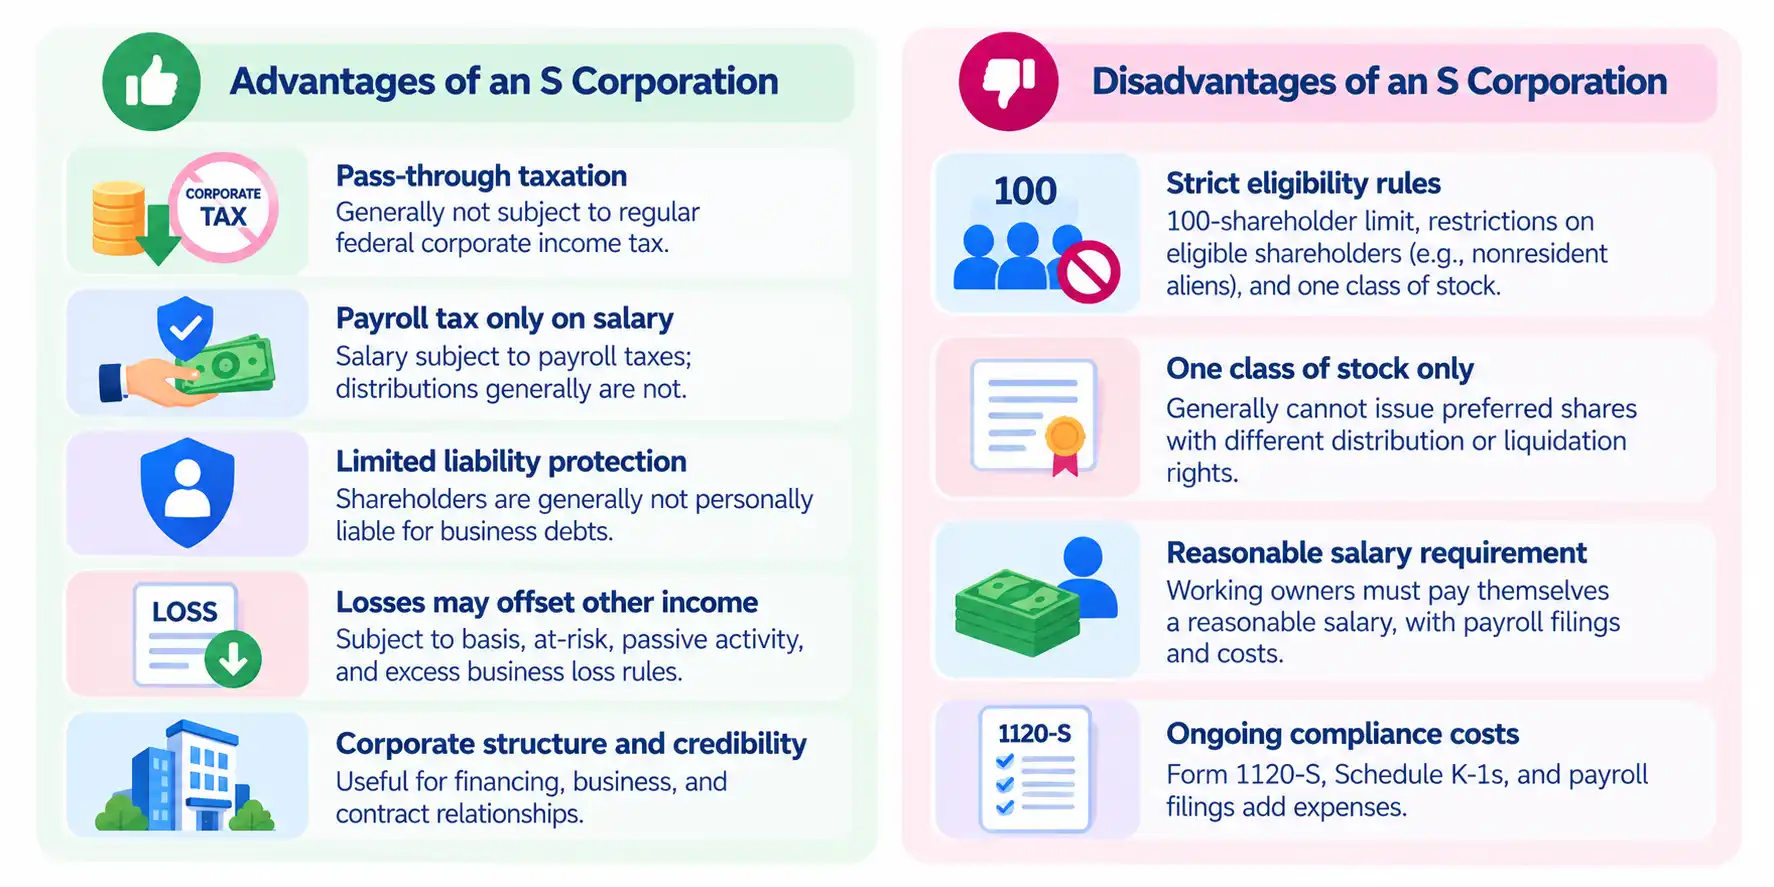
These are the S corporation advantages and disadvantages. Now, moving forward, let's learn the difference between an S corporation, an LLC, and a C corporation.
The table below showcases the differences between a C corporation, an S corporation, and an LLC.
| Basis | LLC | C Corporation | S Corporation |
|---|---|---|---|
| What is it | State-law business entity | Generally, a corporation taxed under Subchapter C | Federal tax status |
| Federal taxation | Depends on members and elections | Separate corporate taxpayer | Pass-through |
| Ownership restrictions | Flexible | More flexible | Strict eligibility rules |
| Non-resident alien owner | Subject to tax or reporting rules | Generally possible | Not permitted as shareholder |
| Number of owners | Depends on state/entity structure | No S corp-style 100-shareholder limit | Up to 100 shareholders |
| Stock classes | Generally, not structured under S corp stock rules | Generally, multiple stock classes possible | One stock class only |
| Owner working in business | Treatment depends on tax classification | Corporate employee compensation rules apply | Shareholder-employee compensation rules apply |
Further, an LLC is a business entity created under law; a C corporation is a separate legal business entity; and an S corporation is a special tax status taxed under Subchapter S. Moving ahead, let's know when forming an S corporation makes sense.
With Savetaxs, choose the right business structure according to your investments, requirements, and financial goals.
An S corporation makes sense when your business consistently generates profits, and you actively work in the company. For instance, a U.S. consulting business that operates as a single-member LLC. Assume it generates enough profit. In this situation, forming an S corp allows you to pay employees a salary for their work and distribute additional earnings to shareholders.
However, before forming an S corporation, compare the payroll tax savings with the additional costs. The additional costs include:
Further, an S corp may not be favorable if profits after reasonable owner compensation are insufficient to justify the additional costs, you need nonresident alien shareholders, you want multiple classes of stock with different economic rights, or you want to avoid administrative burden.
So, whether you should form an S corp depends on your ownership, business profit, growth plans, compensation, and compliance costs.
Lastly, an S corporation is a special tax status that allows eligible businesses to pass specified income, deductions, losses, and credits through to shareholders for federal tax purposes while retaining the underlying legal entity. Whether you should choose an S corporation depends entirely on your ownership, business profits, need for eligible shareholders, and whether you meet the requirements. However, before electing S corporation status, weigh both sides of the decision: ongoing compliance obligations and potential tax treatment.
Unsure whether to opt for S corporation status? Connect with Savetaxs for personalized guidance based on your situation, and clear up any doubts. We can also help you form an S corporation and manage the associated tax obligations.
This article is for general informational purposes only and does not constitute tax, legal, financial, or investment advice. Laws, regulations, rates, and procedures may change over time and may vary based on individual circumstances.
While SaveTaxs makes reasonable efforts to keep the information accurate and up to date, readers should verify applicable rules with official authorities or consult a qualified professional before making decisions based on this information.
Shubham Jain is the Founder of SaveTaxs and has extensive experience in Indian and NRI taxation. He advises individuals, NRIs, and businesses on tax filing, tax planning, capital gains, DTAA benefits, fund repatriation, and compliance matters. He regularly writes about taxation and related financial topics. His focus is on making complex tax concepts easy to understand. Through his articles, he helps taxpayers stay informed, avoid common mistakes, and stay compliant with Indian tax laws. See Full Bio

Want to read more? Explore Blogs